Our September Webinar Series is Here


Posted   Originally on Originally on Sep 4, 2026 by Martin Armstrong |  

What is a Webinar? How to Create an Effective Webinar?

Our September Webinar Series is here.

These are some of our long-running educational webinars that attendees have relied on for years to better understand Martin Armstrong’s methodology, models, and approach to the markets. The concepts may be familiar, but with everything unfolding across the global economy, markets, currencies, sovereign debt, and geopolitics, their application could hardly be more relevant.

And there is one major advantage to attending live: you can ask questions.

These webinars provide attendees with the opportunity to submit questions and receive answers live, allowing you to go beyond simply reading about these concepts and address the areas you want to better understand.

September 15 | 9:00 AM – 12:00 Noon EDT
Understanding the Economic Confidence Model

Learn the foundations of the ECM, how confidence drives the global economy, and how cyclical turning points can help us understand the seemingly disconnected events unfolding around the world.

September 16 | 9:00 AM – 11:00 AM EDT
Understanding the Monetary Crisis Cycle

Explore the recurring cycle behind monetary and sovereign debt crises and gain a deeper understanding of what happens when confidence in government and public debt begins to shift.

September 18–19
Advanced Techniques and Considerations for Using Reversals and Arrays

Designed for those looking to take their understanding further, this advanced webinar focuses on the practical application of Reversals and Arrays and the considerations involved when applying them to trading and market analysis.

Perhaps you have thought about attending one of these webinars in the past but never made the leap. Now is the time. With so many economic, political, and geopolitical shifts unfolding simultaneously, understanding the forces behind these events has become more important than ever. These webinars offer an opportunity not only to learn the models and methodology that Martin has developed over decades, but to participate LIVE and ask the questions you have always wanted answered. If you have been waiting for the right time to deepen your understanding, this September is an excellent place to start.

Reserve your place:

Understanding the Economic Confidence Model:
https://armstronginternational.ticketspice.com/q3-26-understanding-the-ecm-

Understanding the Monetary Crisis Cycle:
https://armstronginternational.ticketspice.com/q3-2026-understanding-the-monetary-crisis-cycle

Advanced Techniques and Considerations for Using Reversals and Arrays:
https://armstronginternational.ticketspice.com/q3-26-advanced-use-of-reversals-and-arrays-for-trading

Categories:Uncategorized

Here Comes the Future


Posted Sep  Originally on 3, 2026 by Martin Armstrong |  

2022 Liquidity Crisis

QUESTION: Marty, I’ve been reviewing all the reports you’ve distributed at the WECs. I wish Trump had attended—I recall he was in the next room one year. Not only have your war cycles been astonishing, but you also forecast this collapse in confidence in governments that would send long-term rates up. I remember back in 2022, you said 5.5% on the 30-year would be the breakout. I’ve reread your 2022 Liquidity Crisis report. Anyone who dares to question your forecasting is simply a troll for the Neocons.

Will you have any surprises at this year’s WEC? We have so much on the table—war, interest rates, sovereign defaults, stock markets, gold, not to mention the election craziness.

You moved to Florida back in 2016 and said your models were showing a long-term decline for the NY area, even predicting that Wall Street would leave. All of those things sounded nuts back then—and here we are today.

JB

Sovereign Debt Crisis 2

ANSWER: Well, we have everything from Sovereign Debt Crisis that has reached $400 trillion while everyone looks only at the USA at $40 trillion, the real threat of nuclear war, interest rates that the central banks have no control over and the morons who keep talking about inflation that a central bank raising rates will not make oil prices decline in the middle of a Cost-Push-Inflation. I warned that politics would become dramatic and showed the computer warned that the Democratic Party could split. Now even James Carville says it should split.

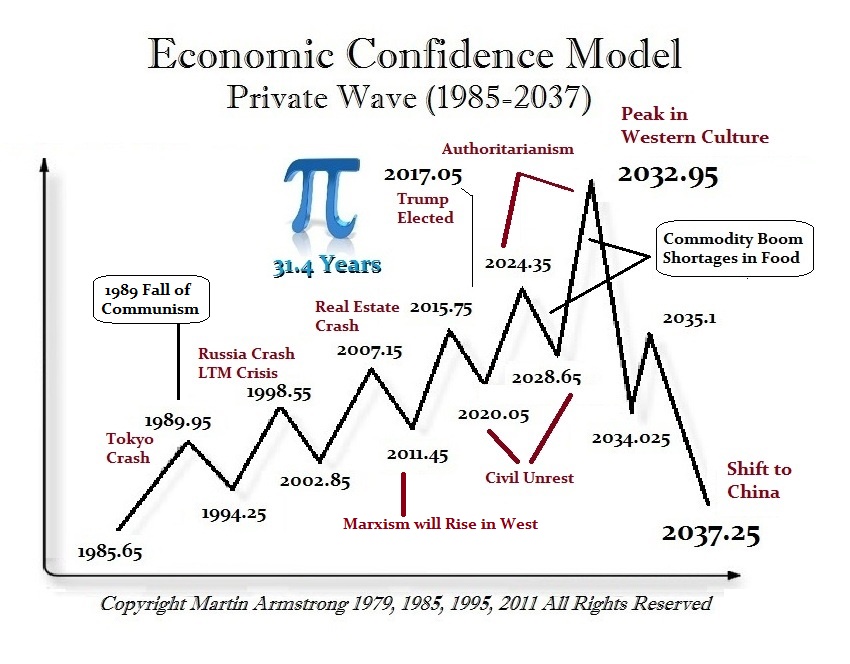
1 ECM 2032 Fall Communism

Besides the 72 Year Revolution Cycle of Russia starting in 1917 that coincided with the ECM 1989.95, and even the real estate crash of 2007 to the day when the floor traders were calling it Armstrong’s Revenge, The computer was correct on the Trump election and forecast the rise in civil unrest from 2020, the commodity boom, the rise in authoritarianism from 2020 into 2032, many overlook the 2011 forecast for the rise in Marxism in the West some call Progressivism.

The evidence strongly indicates that progressivism experienced a significant resurgence in 2011, driven by a wave of grassroots activism in response to economic inequality and conservative policy pushes. This was the prelude to our forecast that the Democratic Party would eventually split. Indeed, several key movements and events took place in 2011.

Occupy Wall Street 10 6 2011 Philadelphia

The Occupy Wall Street Movement was a big one. I remember walking out of the office in Philadelphia back then and the protesters screaming at me calling me a “corporate liberal” where they were just throwing words around that had no meaning.  Beginning in September 2011, this movement brought the national conversation around economic inequality—popularized by the slogan “We are the 99%”—to the forefront of American politics. It energized the progressive left and drew attention from labor unions and even some Democratic lawmakers.

The Wisconsin Capitol Protests also took place in 2011 earlier in the year. That was also massive protests that erupted in Wisconsin against Governor Scott Walker’s bill to curtail collective bargaining rights for public employees. The state, a historical birthplace of the progressive movement, saw tens of thousands of protesters, reinvigorating labor and progressive activism.

By November 2011, progressives celebrated several key electoral wins. Voters in Ohio decisively repealed an anti-union law, and in Mississippi, they rejected a “personhood” amendment that would have severely restricted abortion rights. These were seen as direct rebukes to conservative agendas.

The movements of 2011 received support from established progressive figures and institutions. The Congressional Progressive Caucus voiced solidarity with the Occupy protesters, and labor unions actively partnered with the movement. Publications like The Nation also highlighted the year’s activism as a significant moment for progressivism.

The rise of this progressive movement in 2011 was right on target. I have said many times that the last three wave of a 51.6-year cycle are always the most chaotic. We will have to review where to live for sure. We see the Great Migration in the USA from Blue States that have lost their mind like NYC and the flight to the red states like Tea=xas and Florida.

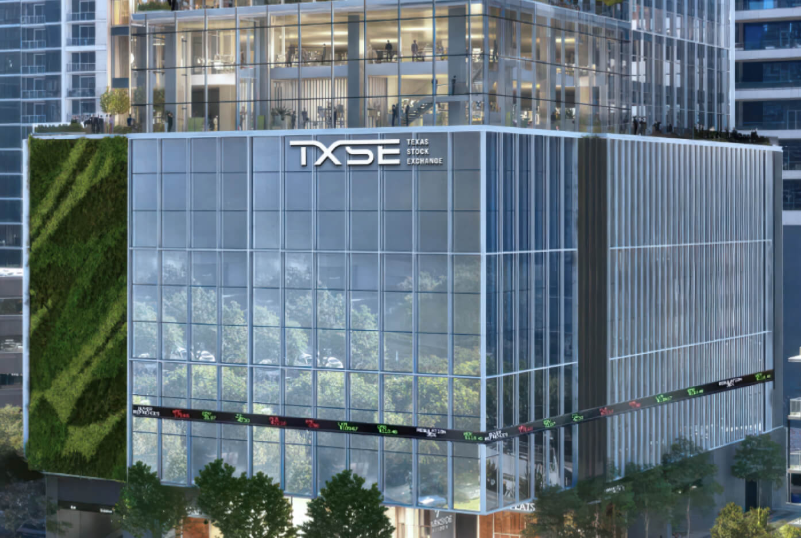
Texas_Stock_Exchange_TXSE

Texas has built a new stock exchange that is actively competing for business from New York. The Texas Stock Exchange (TXSE), based in Dallas, officially launched full trading on July 31, 2026, and it’s already making moves to challenge the long-standing dominance of the NYSE and Nasdaq. Philadelphia holds the title of the first stock exchange in the United States, with its origins tracing back to 1746 and its formal establishment in 1790. The New York Stock Exchange traces its founding to the Buttonwood Agreement in 1792, with its formal organization as a board occurring in 1817. The new TXSE will eventually dwarf NYC and they inevitably will seek to tax stock transactions etc.

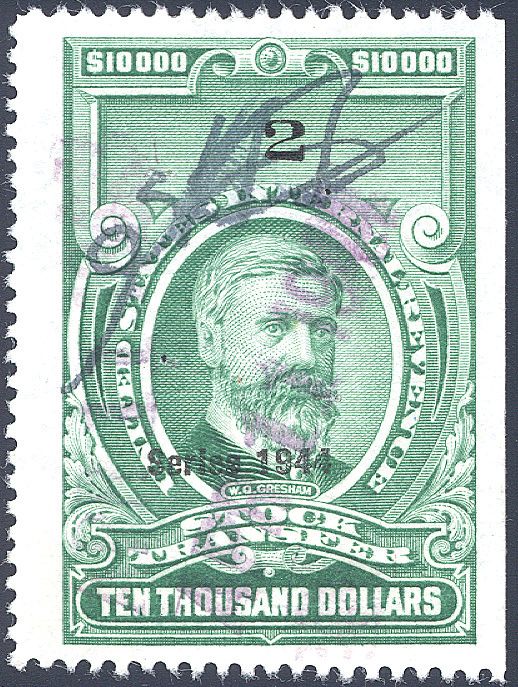
10000

Mayor Zohran Mamdani has actively considered and supported new taxes related to financial transactions. While his focus has been on high-value real estate rather than a general tax on all financial trades, he has supported proposals that function as transaction taxes on luxury property purchases. However, there was imposed during the rise of the progressive era that culminated in the Income Tax in 1913, taxes on financial transactions. New York State Stock Transfer Tax was created in 1905. New York State, in conjunction with New York City, enacted a tax on the transfer of stocks in 1905. This tax was initially a half-penny on stock trades, and it was collected until 1981, when it was eliminated. It has been a subject of ongoing political debate, with recent proposals to reinstate it.

Then there was the Federal Stock Transfer Excise Tax imposed in 1914 to pay for World War I. At the federal level, a stock transfer excise tax (sometimes called a documentary stamp tax) was imposed on the issuance and subsequent transfers of securities. This federal tax was in effect from 1914 to 1966.

Political War Dems vs Repu

We will have a full plate this year between war on 4 fronts, sovereign debts, bond crisis, rising interest rates that are NOT driven by inflation, three political elections, the Everything Bubble, and then political infighting, impeachments, and obstruction of everything.

Technical_Analysis_2026

Also due to popular request, I will include how to do Technical Analysis. I haven’t done that since 2011.

Categories:World Economic Conference

The Digital Euro Is Being Sold Through Fear of America


Posted  Originally on Sep 3, 2026 by Martin Armstrong |  

digitaleuro currency.5j

The European Union has finally admitted that it does not control its own payment infrastructure. Visa and Mastercard now process approximately 65% of card payments across the euro area, while 13 of the 20 eurozone countries depend entirely upon international card schemes for in-store transactions. Brussels spent decades allowing two American corporations to become the backbone of European commerce, and now it is using that dependence to frighten the public into accepting a digital euro controlled by the European Central Bank.

EU Economic Commissioner Valdis Dombrovskis said that Europe’s payment landscape is “highly dominated by non-European providers” and warned that this dependence could prevent the European Union from acting autonomously. He declared that surrendering such technological control to foreign companies poses “real threats to our resilience and economic security.” The concern is valid, but the solution Brussels is offering should alarm every European.

The European Union is presenting the digital euro as a defense against American economic coercion. Officials point out that Visa and Mastercard are American companies subject to American laws, sanctions, and political pressure. If relations between Washington and Brussels deteriorate, European businesses and citizens could theoretically find themselves trapped inside a payment infrastructure controlled from outside Europe.

The European Commission highlighted the case of International Criminal Court judges who faced American sanctions after the ICC issued an arrest warrant for Israeli Prime Minister Benjamin Netanyahu. Those sanctions reportedly interfered with their ability to use payment cards even while living in Europe. Brussels looked at that episode and realized that Washington could reach into the daily financial lives of European residents without controlling a single European government.

Addressing Europe's services dependencies | CEPR

This is the problem governments created when they transformed payment systems into instruments of foreign policy. Washington has used access to the dollar, SWIFT, correspondent banking, credit cards, and international reserves as weapons against targeted governments and individuals. Europe enthusiastically participated whenever the target was Russia, Iran, or another political opponent. Now European officials are suddenly offended because the same infrastructure could be used against them. Brussels never objected to financial warfare as a principle. It objected only when it discovered that someone else controls the weapon.

The digital euro is being marketed as “strategic autonomy.” The ECB claims it will provide a universally accepted European payment option that works in stores, online, between individuals, and even without an internet connection. The European Council agreed on its negotiating position in December 2025, and the ECB intends to be ready for a potential first issuance during 2029 if the required legislation is adopted in 2026. Pilot testing is expected to begin in 2027.

The politicians insist that the digital euro will merely complement cash rather than replace it. They promise that basic use will be free, merchants will be required to accept it, and consumers will retain the freedom to use other payment methods. They also say that the digital euro will not be programmable money, meaning public authorities supposedly will not be able to dictate where, when, or upon what it can be spent.

The ECB maintains that it would not be able to connect the identity of an individual directly to online digital-euro transactions. Offline payments are being designed to offer greater privacy, with transaction details supposedly known only to the payer and recipient. European officials repeatedly describe these safeguards as proof that fears of surveillance and government control are unfounded.

The issue is not what they promise today. The issue is what the infrastructure will permit tomorrow. Every system of government control begins with assurances that the new power will be narrow, temporary, and protected by law.

Europe Break Free From Visa and Mastercard in $24 Trillion Payments - MSME  Africa

The same argument will always be used. First, they will target terrorism, organized crime, sanctions evasion, and tax fraud because few people will publicly defend those activities. The controls will then expand to ordinary financial behavior. Governments will demand more reporting to fight the underground economy, more restrictions to enforce sanctions, and more visibility to collect taxes. During the next banking crisis, they will argue that holding limits or transfer restrictions are necessary to prevent instability.

The ECB will say that offline digital-euro payments offer cash-like privacy, but “cash-like” is not cash. The digital euro will still require an electronic device or card, a wallet, software, funding procedures, and rules governing maximum balances and transactions. The existence of an offline function does not transform a centrally issued electronic liability into a bearer instrument beyond the reach of the system.

Holding limits expose another contradiction. The ECB does not want people moving too much money from commercial banks into digital euros because that could drain bank deposits and destabilize the banking system. Authorities therefore intend to restrict how much digital currency an individual may hold. They are creating what they call digital cash while ensuring that citizens cannot freely hold it like cash.

Replacing Visa and Mastercard with a centralized public system does not eliminate concentrated power. It transfers that power from two American corporations to European political and monetary institutions. Visa cannot impose a negative interest rate upon the euro. Mastercard cannot establish capital controls across the continent. Neither corporation can inflate the currency, rescue insolvent governments, or change the legal definition of money. The ECB and European legislators possess powers far beyond anything available to a card company.

The same governments that froze reserves and expelled opponents from financial systems are asking the people to trust them with digital money. The same central banks buying and repositioning gold are telling citizens that electronic currency is the safe future. Europe is not escaping financial weaponization. It is bringing the weapon home and placing it under Brussels’ control.

Singapore: Capital Is Voting With Its Feet


Posted  Originally on Sep 3, 2026 by Martin Armstrong |  

Singapore Night scaled

Singapore’s economy expanded 5.9% year-over-year during the second quarter of 2026 after growing 6.3% in the first quarter. That brought growth for the first half of the year to 6.1%, an extraordinary performance for an already-developed economy. The government has now raised its full-year growth forecast to between 4.5% and 5.5%, substantially higher than its previous projection of 2% to 4%. This is not India or Vietnam starting from a low economic base. Singapore is already one of the wealthiest countries in the world.

I wrote earlier this year that Singaporeans were feeling their economy grow in real time. The latest numbers continue to confirm what is taking place there. Singapore has become one of the primary beneficiaries of global economic and geopolitical fragmentation because capital does not care about political speeches. It moves where it believes it will be safe, where business can operate, and where there is confidence in the future. Singapore understood this while much of the West decided that successful businesses and wealthy individuals were simply another source of revenue to be taxed.

Manufacturing has been one of the driving forces behind this expansion. Singapore positioned itself directly in the path of the semiconductor and artificial intelligence investment boom while Europe was debating how many regulations it could impose on technology. Electronics, precision engineering, semiconductors, pharmaceuticals, financial services, logistics, and information technology have all helped support the expansion. Singapore does not possess vast natural resources. It became wealthy by understanding that human capital, financial stability, infrastructure, and confidence are resources in themselves.

This is also a capital flow story. Singapore has become a magnet for wealth leaving other jurisdictions. More than 2,000 single-family offices are now operating there, compared with only a few hundred several years ago. Chinese wealth seeking diversification, Asian entrepreneurs, multinational corporations, and Western investors looking for stability have increasingly viewed Singapore as a safe place to establish businesses and preserve capital. Money does not need a passport. Politicians can erect barriers, impose taxes, and condemn people for moving their wealth, but capital will always seek the environment where it is treated best.

This is precisely what Western governments fail to understand. Britain believes it can continually increase taxes on capital without consequences. Brussels believes corporations will simply absorb higher energy costs and endless regulation because politicians command them to do so. Canada has attacked investment while expanding government spending and debt. France believes wealthy citizens exist merely to finance government promises. Then politicians express shock when businesses, entrepreneurs, and capital begin looking elsewhere.

Singapore took the opposite approach. It created a financial center where international companies could operate efficiently, built world-class infrastructure, maintained one of the busiest ports on the planet, developed Changi into a major international aviation hub, invested heavily in education and technology, and cultivated an environment where corruption remained comparatively low. None of this happened accidentally.

Geography has certainly helped. Singapore sits directly on one of the most important trade routes in the world. Yet countless countries possess favorable geography and squander it through corruption and political incompetence. Singapore turned its location into an economic weapon. As tensions between China and the United States intensify, multinational companies increasingly need Asian headquarters that can operate between both worlds. Singapore is becoming that neutral ground.

This is why the current transformation of the world economy is so fascinating. India is expanding at 7.8%. Vietnam has been growing above 8%. Mexico is benefiting from nearshoring and its proximity to the United States. Singapore is attracting capital and high-value industries as investors seek stability. These countries are not identical and they are certainly not without problems, but capital is increasingly migrating toward regions that are still building rather than those desperately taxing their populations to maintain systems created generations ago.

Singapore still has serious challenges. Housing is extremely expensive, the cost of living is high, the population is aging, and the economy remains extraordinarily dependent on international trade. A severe collapse in global commerce would certainly affect Singapore. No economy operates independently of the global cycle.

Yet Singapore demonstrates an important principle that governments continually refuse to understand. You do not create prosperity by attacking those who produce it. You create an environment where capital wants to come voluntarily.

The global economy is not simply rising or falling together. We are watching a geographic redistribution of wealth, production, technology, and confidence. India is rising through demographics and industrialization. Vietnam is rising through manufacturing and foreign investment. Mexico is benefiting from the reorganization of North American supply chains. Singapore is rising because global uncertainty itself is pushing capital toward stability. That is why Singaporeans can feel the economy growing in real time.

The Netherlands Is Moving Its Gold as Trust in the Financial System Collapses


Posted  Originally on Sep 3, 2026 by Martin Armstrong |  

gold reserve fort knox

The Netherlands is moving a substantial portion of its gold reserves out of the United States and Canada and placing it in London. De Nederlandsche Bank will dress this up as an exercise in “tradability,” geographical diversification, and crisis preparedness, but central banks do not quietly rearrange billions of euros in physical gold because everything is stable. This is a geopolitical decision forced by the realization that the international financial system has been weaponized and that access to national reserves can no longer be taken for granted.

NOS reported that approximately 86 tonnes of Dutch gold were relocated between March and August 2026. The Netherlands holds 612.4 tonnes in total, valued at €72.2 billion at the end of 2025. Before this operation, 31.3% was held in New York, 19.7% in Ottawa, 18.1% in London, and 30.8% at the Dutch central bank’s cash center in Zeist. The new distribution places 32.1% in London, 30.8% in the Netherlands, and 18.5% each in New York and Ottawa.

The amount held in New York has therefore been reduced from roughly 192 tonnes to 113 tonnes. London’s share has increased from around 111 tonnes to approximately 197 tonnes. DNB has not reduced the overall gold reserve, but it has deliberately reduced its exposure to North America and made London its largest foreign storage location.

This was not simply a fleet of armored trucks carrying 86 tonnes across the Atlantic. DNB sold nearly 59 tonnes of gold held in New York and purchased an equivalent quantity in London that conforms to modern international trading standards. Another 27 tonnes were physically moved from the United States and Canada to the Netherlands, while an equivalent amount of internationally tradable gold was transferred from Zeist to London. They avoided having to melt and recast older bars, reduced transportation risk, and tested multiple methods for moving gold during a future crisis.

DNB openly stated that this experience could prove useful if gold must be moved again during another crisis and one of the available methods is no longer possible. Central banks do not conduct emergency drills without contemplating the emergency. They are preparing for a world in which a traditional transportation route could suddenly become unavailable.

DNB President Olaf Sleijpen said, “We assume that we will never have to use the gold, but it is nevertheless necessary to strengthen our resilience and preparedness.” The bank also described gold as the “ultimate anchor of trust” capable of covering extreme systemic risks. These are extraordinary admissions from the same class of central bankers who spent decades pretending gold was an outdated relic while they created money without restraint and drove sovereign debt beyond any possibility of repayment.

The official explanation is that gold held at the Bank of England is more immediately tradable because London remains the world’s largest over-the-counter bullion market. Gold stored there meets the international Good Delivery standards needed for rapid settlement, lending, swaps, and outright sale. London’s bullion market processes enormous volumes, and its clearing infrastructure reportedly handles around $160 billion in transactions each day. If DNB needs liquidity during a systemic crisis, London provides the fastest route from physical metal into usable funds.

That explanation is technically valid, but it does not answer why the Dutch suddenly decided that they needed 86 additional tonnes positioned for immediate crisis deployment. The decision is explicitly linked to “increasing geopolitical unrest.”

The West destroyed the neutrality of the reserve system when it froze Russia’s foreign-exchange reserves after the invasion of Ukraine and later developed mechanisms to redirect the earnings from those assets. Whatever one thinks of Russia or the war is irrelevant to the monetary consequences. The United States and Europe demonstrated that foreign reserves held in their jurisdictions are conditional assets. They belong to another nation only for as long as Washington, Brussels, or London recognizes that government and approves of its conduct.

Moving the gold to London does not eliminate geopolitical risk. Britain has already demonstrated that custody does not guarantee access. The Bank of England refused to release Venezuelan gold after the British government ceased recognizing Nicolás Maduro’s authority. Dutch officials may regard Britain as a friend today, but alliances change, governments fall, and foreign policy can reverse overnight. If the purpose is absolute protection against extreme systemic risk, the only unquestionable location is inside the Netherlands.

Nevertheless, the Dutch move exposes the broader trend. Governments are no longer preparing merely for fluctuations in exchange rates or ordinary banking stress. They are preparing for fractured payment networks, sanctions between former partners, capital controls, sovereign defaults, and a breakdown in the political trust supporting the postwar financial order.

Trust is vanishing because governments themselves destroyed it. Once money became a weapon of war, every nation was forced to ask whether its reserves could be used against it. The Dutch have now answered by placing more of their gold where they believe it can be mobilized quickly and, as some put it, held among friends. The troubling part is that nations only begin identifying their true friends when they expect the system to fracture.

Bessent Destroying the Dollar


Posted Originally on Sep 2, 2026 by Martin Armstrong |  

Treasury Secretary Scott Bessent threatened the entire world in perhaps the most authoritative speech that makes other nations hate Americans for this arrogance.  Scott Bessent thinks he is still with Soros and can now really manipulate the world economy. Those who ask if I have any connection with him the answer is FLAT OUTRIGHT NO WAY!!!!! We are adversaries and he would sooner destroy the USA before ever consulting Socrates. He hates my guts.

Neocon Dividing World Economy

The arrogance of the United States is off the charts. Allowing Bessent and the Neocons to use the dollar as a weapon has already divided the world economy. China’s CIPS has been experiencing significant growth. It processed 175 trillion yuan (about $24.47 trillion) in 2024, with plans to expand to support multi-currency settlement. SWIFT is exclusively dollars. CIPS handles approximately 70% of all RMB cross-border payments, and its single-day transaction value has reached new highs, exceeding 1.22 trillion yuan in early 2026. That is 179.9 billion USD daily.

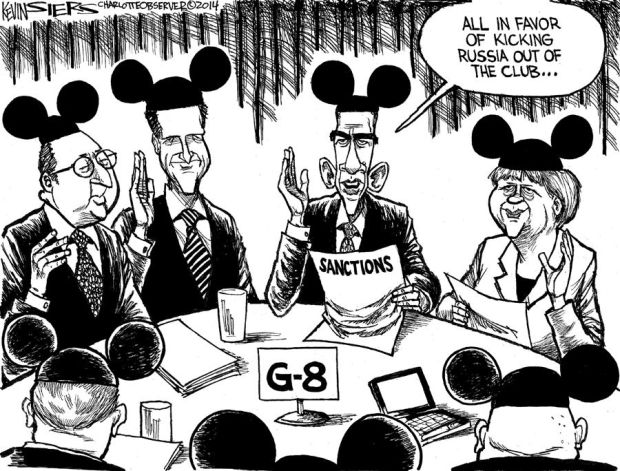
Obama G8 Micky Mouse Crimea Russia

Transforming the US dollar into a weapon is having devastating effects and underminded the FAITH in the US dollar. Obama started this insanity. When Russia came to the aid of Russians in Crimea, he went to SWIFT and insisted that they remove Russia from the system. They said no way. So they replaced the head of SWIFT as a puppet and they started weaponizing the dollar by removing Russia and then had the audacity to threaten China if they aided Russia against Ukraine.

Let’s expose the hypocrisy here. The United States has a well-established history of using military force to protect or rescue its citizens abroad, sometimes escalating to a full-scale invasion. This practice is rooted in the government’s view that it has a legal right—based on national “self-defense“—to protect its citizens wherever they are, and that this right has even been used to justify military intervention in foreign countries. They deny that to Russia.

The principle that the U.S. government can use force to protect its citizens abroad is long-standing. An 1860 U.S. Circuit Court case, Durand v. Hollins, established an important precedent by upholding a naval bombardment of Greytown, Nicaragua, as a reprisal for violence against U.S. nationals. The ruling stated that “the citizen abroad is as much entitled to protection as the citizen at home,” and that a government failing in this duty “is not worth preserving” .

This legal concept supports what has historically been called “gun-boat diplomacy“—the use of military force to protect citizens or their property in other countries . The US will invade and has done so but claim Russia coming to the aid of Russians in the Donbas is illegal?

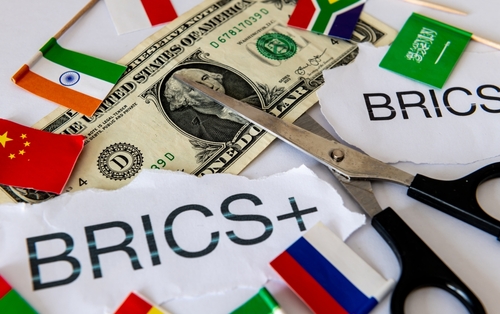
BRICS DeDollarization

These people who love power are so stupid that they cannot see that the more people they remove from SWIFT isolates the United States and in the process they are destroying the dollar. The DEDOLLARIZATION has nothing to do with debt, gold, or FIAT. Such arguments only reveal how little they know about how the world economy functions. This is geopolitical and this latest NONSENSE from Bessent will only fulfill our computer forecast that they are destroying the world economy and in the process the dollar as soon as 2030 where we have a Panic Cycle. These idiots are so arrogant and stupid, they cannot see that they are undermining not just the dollar, but the entire world economy. BRICS is a response to American arrogance.

Dethrone Dollar

They are guaranteeing that China will supplant the United States as the financial capital of the world for the yuan will become more trustworthy by the mere fact that China would not turn its currency into a weapon when they are benefitting every day the more the USA weaponizes the dollar.

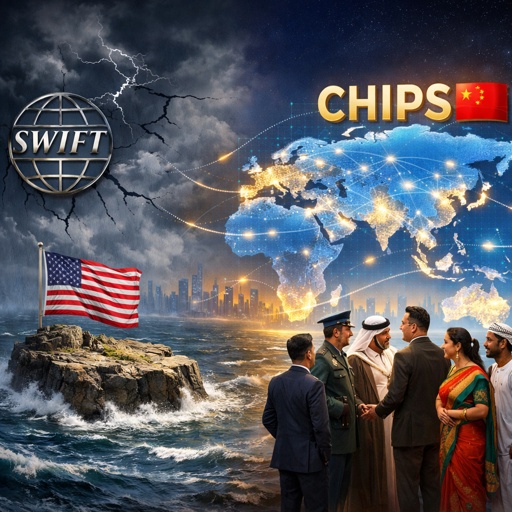
China vs US CHPS vs SWIFT

Categories:Sanctions

Vietnam: Another Economy Rising in Real Time


Posted  Originally on Sep 2, 2026 by Martin Armstrong |  

Vietnam Economy Outlook 2026: Growth and Investment Trends - uSafe Certified Public Accountants

I wrote only a few months ago that the Vietnamese were feeling their economy grow in real time. Now the numbers are becoming even stronger. Vietnam’s economy expanded 8.39% year-over-year during the second quarter of 2026, while GDP for the entire first half increased 8.18%, accelerating from 7.63% during the same period last year. This is not merely growth on paper. Industry is expanding, factories are producing more, exports are surging, foreign capital is pouring into the country, and infrastructure is being built around an economy that is rapidly becoming one of the major manufacturing centers of Asia.

Look beneath the GDP number and you can see where this growth is coming from. Industry and construction expanded 10.51% during the second quarter. Manufacturing grew 10.23% during the first half, while construction increased 9.51%. Vietnam’s Industrial Production Index rose 10.8% during the first six months, compared with 8.7% a year earlier. By June alone, industrial production was running 12.7% above the previous year. These are the numbers of an economy actually producing something.

Capital is following that production. Foreign investment commitments reached $34.65 billion through June, an astonishing 61% increase from the previous year, while actual disbursed foreign direct investment reached $13.03 billion, up 11.2%. Total investment throughout the economy increased 12.9%, and gross capital formation rose 15.2%. This is precisely what I have explained about international capital flows. Money does not remain permanently in London, Frankfurt, New York, Tokyo, or Beijing. It migrates wherever it sees opportunity, production, and the potential for a greater return.

Vietnam is benefiting tremendously from the reorganization of global manufacturing. Corporations do not necessarily need to abandon China entirely. They are diversifying production because concentrating an entire supply chain inside one geopolitical jurisdiction has become increasingly dangerous. Vietnam has emerged as one of the primary beneficiaries of that shift. Samsung has invested billions there, Apple suppliers have expanded production, and electronics, machinery, apparel, semiconductor, and technology companies continue building capacity throughout the country. Vietnam is now attempting to move even further up the value chain by attracting investment in semiconductors, artificial intelligence, and 5G rather than remaining merely a source of inexpensive labor.

Trade illustrates the scale of this transformation. Vietnamese goods exports reached $266.5 billion during the first half of the year, an increase of 21%. Exports of goods and services rose more than 20%, while the United States alone purchased $86.5 billion of Vietnamese goods. Imports surged even faster because Vietnam is bringing in machinery, components, energy, and intermediate goods needed by its expanding industrial base. China remains its largest import market, supplying $115.2 billion during the first half. This is why the simplistic Western argument that Vietnam must somehow replace China completely misses how economies actually develop. Vietnam can grow alongside China while becoming another critical manufacturing center in Asia.

The growth is also spreading beyond factories. Wholesale and retail trade expanded 9.67%, transportation and storage grew 10.18%, and financial, banking, and insurance activities increased 7.97%. Retail sales during the first half reached nearly 3.9 quadrillion dong, rising 12.9% in nominal terms and 7.3% after adjusting for prices. International arrivals reached 12.3 million, up nearly 15%, while freight volumes increased more than 13%. When production expands, transportation expands. When wages and employment improve, consumption expands. That is how economic growth begins feeding through an entire economy.

Compare that with what is happening across much of Europe. Governments there are borrowing enormous sums merely to maintain existing systems while businesses face high energy costs, taxation, regulation, aging populations, and geopolitical uncertainty. They are trying to redistribute wealth while simultaneously destroying the conditions necessary to create it. Vietnam is still building factories, ports, roads, airports, industrial parks, logistics networks, and productive capacity.

That does not mean Vietnam is immune from problems. Its rapid expansion is creating inflationary pressures, and its trade deficit has widened sharply as imports surge. By July, exports were up 21.7% for the year, but imports had risen 34.8%, producing a $20.5 billion trade deficit. Higher fuel costs are adding additional pressure, and Vietnam remains vulnerable to changes in US trade policy because America has become such an important destination for its exports. These are genuine risks that cannot simply be ignored.

Yet even July’s figures show that the underlying economy remains exceptionally strong. Industrial production increased 14.5% year-over-year, retail sales rose 14.5%, and foreign direct investment inflows increased 11.8% to $15.2 billion during the first seven months. Vietnam is not merely maintaining growth. It is still attracting capital while expanding production at double-digit rates.

This is the same broader transformation we are witnessing in India and Mexico. The global economy is not moving uniformly upward or downward. The economic center of gravity itself is changing. Some countries are burdened by mature welfare states, impossible sovereign debts, deteriorating demographics, and governments increasingly hostile toward private enterprise. Others are still moving through the productive phase of development where infrastructure, manufacturing, capital investment, and rising household incomes reinforce one another.

That is why I described this as growth people can feel in real time. You do not need some economist in Washington to tell you the economy is expanding when a factory opens down the road, a new highway appears, wages rise, airports expand, and your children have opportunities that did not exist for your generation. Confidence rises because people can physically see progress taking place around them.

Vietnam is becoming another example of what happens when productive capital is permitted to build rather than merely being taxed to sustain yesterday’s promises. The numbers are now confirming what the Vietnamese people have already been watching around them. Their economy is rising in real time.

Sanctions Undermining the US Economy Long Term


Posted  Originally on Sep 2, 2026 by Martin Armstrong |  

Sanctions Chains

I have warned, but nobody seems to listen, that war NEVER unfolds when everyone is fat an happy. This stupid decision of imposing sanction under the theory that they will punish the people and cause them to rise up and overthrow their governments fails to ever work Sanction were impose on Cuba in 1960 and are still there.

This stupid theory of imposing sanction assumes that economic pain will logically lead to political change. However, in reality, this often backfires. Instead of turning against their leaders, targeted populations (like in North Korea, Cuba, or Iran) often rally around the flag, viewing the sanctions as an external attack on their sovereignty. The sanctions imposed on Russia I found in a conversation with a Russia I was asked: “Why does the West hate us so much?” These sanctions are not causing the Russian people to rise as they do in theory only.

So, while the theory behind U.S. sanctions is to coerce, deter, and promote values, the outcome is frequently a form of containment, simply making it very expensive and difficult for a rival nation to operate globally, rather than actually forcing a regime change or policy reversal. This leads to creating permanent enemies.

Dollar Beat Up

Sanctions have become a permanent feature of U.S. foreign policy less because they perfectly achieve their goals, and more because they are a powerful, low-risk tool for expressing U.S. power in a multipolar world. However, this is entirely back by the fact that the dollar is the reserve currency and that the US is the largest economy. But imposing sanctions also reduces US economic growth the same as the current Tariff war.

Dethrone Dollar

Removing Russia from the SWIFT System and threats against China if they to not comply with US Neocon demands, has led to China creating s competing CHIPS system and the abuse of using the dollar as a weapon is actually setting the stage for the eventual decline of the dollar system.  These Neocons understand nothing about economics.

China vs US CHPS vs SWIFT

This is why our computer is projecting that China will Become the New Financial Capital of the World displacing the United States. If these stupid Neocon remove everyone from SWIFT who they do not like, guess what, the US becomes isolated and the dollar will no longer be the reserve because these morons have used it as a weapon.

China on the Rise Report - Hard Copy


We published that forecast back in 2018 and targeted 2027 as a critical turning point. We will update this for the 2026 WEC. The Export-Import Bank of China has a loan balance of over 2 trillion RMB dedicated to Belt and Road Initiative (BRI) countries, covering more than 130 nations . China has become the world’s largest bilateral official creditor.

The issuance of “panda bonds” in China’s financial market is a key mechanism for providing credit. Besides Egypt, other issuers include the African Export-Import Bank and the Brazilian company Suzano.

Dollar into Yuan

Shift to RMB lending is unfolding on a global scale and the Neocons are too stupid to look at economics. They were probably bullying kids in the school yard skipping economics altogether. There is a trend where China is encouraging, and in some cases requiring, borrowing countries to take on loans in RMB rather than USD. This helps protect borrowers from some currency risks but also creates new ones if their own currency weakens against the RMB.

China restructured Kenya’s loans which has prompted interest from other nations, including Ethiopia, Mozambique, Zambia, Pakistan, and Indonesia, who are reportedly considering similar restructuring to convert their USD debt to RMB debt.

China restructured Kenya’s loans primarily by converting three major railway loans from U.S. dollars to Chinese yuan, but combined this currency switch with traditional debt relief measures that provided the bulk of the financial benefit. The Restructuring Agreement was laid out:

  1. The restructuring applied to three loans from the China Exim Bank, totaling about $3.5 billion, which financed the construction of Kenya’s Standard Gauge Railway (SGR). The agreement involved:
  2. Currency Conversion: Switching the loans from U.S. dollars to Chinese yuan.
  3. Interest Rate Margin Removal: Waiving the original margins of 3% and 3.6% on two variable-rate loans.
  4. Extended Grace Period and Maturity: Adding new grace periods and extending the repayment terms.

China understands the game and they are leaving behind a bunch of Neocons who always impose sanctions, threaten to remove nations from the SWIFT system, and cannot see past their own nose that the world is moving away from these idiots who have used the dollar as a weapon in an international war that they are losing.

Market Talk – September 1, 2026


Posted  Originally on Sep 1, 2026 by Martin Armstrong |  

Market Talk 2017

ASIA:

The major Asian stock markets had a negative day today:

• NIKKEI 225 decreased 96.59 points or -0.15% to 66,215.34

• Shanghai decreased 6.41 points or -0.16% to 3,979.888

• Hang Seng decreased 237.26 points or -0.93% to 25,329.73

• ASX 200 decreased 9.30 points or -0.10% to 9,066.70

• SENSEX decreased 12.99 points or -0.02% to 76,944.28

• Nifty50 decreased 24.60 points or -0.10% to 24,055.80

The major Asian currency markets had a mixed day today:

• AUDUSD decreased 0.002 or -0.28% to 0.71467

• NZDUSD decreased 0.00245 or -0.41% to 0.58905

• USDJPY increased 0.499 or 0.31% to 160.238

• USDCNY increased 0.00451 or 0.07% to 6.72242

The above data was collected around 13:51 EST.

Precious Metals:

•  Gold decreased 99.42 USD/t oz. or -2.24% to 4,341.72

•  Silver decreased 1.934 USD/t. oz. or -2.91% to 64.586

The above data was collected around 13:53 EST.

EUROPE/EMEA:

The major Europe stock markets had a negative day today:

•  CAC 40 decreased 32.65 points or -0.39% to 8,301.85

•  FTSE 100 decreased 34.98 points or -0.32% to 10,789.28

•  DAX 30 decreased 288.00 points or -1.10% to 25,970.11

The major Europe currency markets had a mixed day today:

• EURUSD decreased 0.00302 or -0.26% to 1.15874

• GBPUSD decreased 0.00373 or -0.28% to 1.35116

• USDCHF increased 0.00392 or 0.48% to 0.81228

The above data was collected around 14:15 EST.

AMERICAS:

US Markets:

  • DJIA declined by 419.02 points (0.79%) to 52,766.88
  • S&P 500 declined by 54.67 points (0.71%) to 7,631.47
  • NASDAQ declined by 271.12 points (1.03%) to 26,099.774
  • Russell 2000 declined by 36.32 points (1.23%) to 2,920.132

Canada:

  • TSX Composite declined by 444.75 points (1.23%) to 35,825.73
  • TSX 60 declined by 20.95 points (0.98%) to 2,107.77

Brazil:

  • Bovespa advanced by 2,258 points (1.27%) to 179,676.78

ENERGY:

The oil markets had a mixed day today:

•  Crude Oil increased 4.265 USD/BBL or 4.97% to 90.025

•  Brent increased 3.975 USD/BBL or 4.39% to 94.466

•  Natural gas decreased 0.0291 USD/MMBtu or -0.99% to 2.9059

•  Gasoline increased 0.0581 USD/GAL 1.89% to 3.1351

•  Heating oil increased 0.2543 USD/GAL or 5.77% to 4.6649

The above data was collected around 14:18 EST.

•  Top commodity gainers: Heating Oil (5.77%), Crude Oil (4.97%), Brent (4.39%) and Orange Juice (5.58%)

•  Top commodity losers: Palladium (-4.24%), Cocoa (-3.81%), Silver (-2.91%) and Gold (-2.24%)

The above data was collected around 14:25 EST.

BONDS:

Japan 2.9960% (+4.87bp), US 2’s 4.40% (+0.042%), US 10’s 4.7920% (+3.6bps); US 30’s 5.26 (+0.019%), Bunds 3.3693% (+4.55bp), France 4.206% (+2.79bp), Italy 4.2020% (+3.66bp), Turkey 34.480% (+264bp), Greece 4.0190% (+2.64bp), Portugal 3.6940% (+0.14bp); Spain 3.827% (+5.3bp) and UK Gilts 5.2533% (+11.02bp)

The above data was collected around 14:28 EST.

Categories:Market Talk

Marine Le Pen and the Nationalist Trend the Establishment Cannot Stop


Posted  Originally on Sep 2, 2026 by Martin Armstrong |  

The far-right Marine Le Pen accuses the Sánchez Government of "encouraging the massive entry of migrants" into Ceuta and demands France reinforce controls

A new poll out of France should not be viewed as some sudden political awakening. It is confirmation that the nationalist trend we have been watching throughout Europe for years is continuing and becoming stronger. The poll places Marine Le Pen comfortably ahead in the first round of the 2027 presidential election, with roughly 36% support, far beyond any of the establishment candidates currently positioned against her. More importantly, the polling indicates that National Rally is no longer merely collecting an angry protest vote. Le Pen is increasingly competitive with, and in several scenarios ahead of, mainstream candidates in the second round where the French establishment historically united to prevent her from reaching the Élysée Palace.

This is the continuation of a political trend, not the beginning of one. Brexit was part of it. Trump was part of it. Giorgia Meloni’s victory in Italy was part of it. The Freedom Party winning the largest share of the vote in Austria was part of it, as has been the extraordinary expansion of AfD in Germany. Reform UK has disrupted the old Conservative-Labour structure in Britain, while nationalist and sovereignty movements have advanced across the Netherlands, Portugal, Romania, and elsewhere. Different countries have different grievances, but they are all reacting to the same fundamental problem: people are losing confidence in political establishments that transferred too much sovereignty away from the nation-state.

Le Pen fits directly into this trend because her opposition to Brussels has always been central to her political appeal. National Rally no longer advocates withdrawing France from the European Union or abandoning the euro, but Le Pen continues to argue that France must regain sovereignty from EU institutions. That is what terrifies the establishment far more than all the rhetoric about the “far right.” France is one of the pillars holding the European project together, and a French president willing to challenge the authority of unelected bureaucrats in Brussels would pose a threat to European centralization that Hungary or Slovakia simply cannot.

The EU was sold to Europeans as an economic union that would facilitate trade and prevent another European war. It has transformed itself into an enormous political bureaucracy regulating energy, agriculture, automobiles, immigration, environmental policy, trade, and increasingly defense and foreign affairs. The average French citizen cannot vote the European Commission out of office. Yet those bureaucrats can impose regulations that directly affect what car he drives, what his electricity costs, how farmers use their land, and what policies his national government is permitted to implement.

This is precisely why nationalism has continued gaining ground. The establishment insists that people voting for these parties have somehow become extremists, but perhaps they should look in the mirror. Trump did not create nationalism in America, Brexit did not create nationalism in Britain, and Le Pen did not create nationalism in France. These movements expanded because governments increasingly stopped representing the interests of the people who elected them.

France illustrates the trend perfectly. Le Pen received only 17.9% in the first round of the 2012 presidential election. She increased that to 21.3% in 2017 and then 23.2% in 2022. In the presidential runoff, she went from 33.9% against Macron in 2017 to 41.5% in 2022. Now she is polling around 36% before the first ballot is even cast in 2027. You do not need some complicated political theory to understand what is happening. The direction has been underway for more than a decade.

Nationalism

The establishment has nevertheless repeatedly attempted to contain nationalist parties rather than address why people are voting for them. Germany constructed its political “firewall” against AfD, whereby the traditional parties refuse cooperation regardless of how many Germans vote for it. Austria’s Freedom Party won the largest share of the vote in its 2024 parliamentary election yet initially found itself excluded while establishment parties attempted to construct a government without it. Millions of Europeans are effectively being told that they are free to vote for whomever they like, provided their vote does not actually change who governs.

Romania exposed how dangerous this mentality can become. Călin Georgescu unexpectedly won the first round of the presidential election in 2024 before the Constitutional Court annulled the election amid allegations of campaign irregularities and Russian interference. Georgescu was then barred from participating when the election was rerun. There were legal arguments behind those decisions, but politically the result was extraordinary: the man who won the first election was not permitted to compete in the replacement election. That does not restore confidence in democracy. It destroys it.

Now look at Le Pen. Her conviction in the European Parliament assistants case initially included an immediately prohibition on seeking public office that threatened her participation in 2027. Her legal position subsequently changed through the appeals process, leaving her able to run, but France came remarkably close to having the eligibility of its leading opposition candidate determined by the judiciary rather than the electorate.

Then there is campaign financing. National Rally has repeatedly struggled to obtain loans from French banks despite representing millions of French citizens. Le Pen was forced to seek financing outside France in previous elections, and Jordan Bardella has again complained about the difficulty of securing French bank financing for 2027. Each institution can offer its own explanation, but voters are not blind when they see the same political movement confronting obstacles from the courts, banks, bureaucracy, media, and traditional parties simultaneously.

This is why the latest poll matters. The old strategy is losing its effectiveness. For decades, the French establishment relied upon the Republican Front, whereby parties that despised each other would nevertheless unite in the second round to prevent National Rally from winning. That worked spectacularly in 2002 when Jacques Chirac defeated Jean-Marie Le Pen with more than 82% of the vote. By 2017, Marine Le Pen had increased the family’s runoff vote to nearly 34%. Five years later she reached 41.5%, and now polling suggests the barrier that once made a National Rally presidency virtually impossible is continuing to erode.

The establishment should ask WHY instead of trying to devise another method to stop the candidate. People throughout Europe are rejecting governments that demand endless sacrifices for Brussels while ignoring problems at home. They have watched uncontrolled immigration transform communities, Net Zero policies drive up energy costs, sovereign debt expand, taxes increase, and billions flow into foreign wars while governments insist there is no money for their own citizens. Then the same political class lectures voters that choosing anyone who challenges this arrangement represents a threat to democracy.

That has been the mistake throughout Europe. The establishment treats nationalist politicians as the cause when they are merely the political manifestation of a much broader collapse in confidence. You can investigate a politician, construct a firewall around a party, deny financing, or prevent coalition participation, but none of those measures addresses why voters abandoned the establishment in the first place.

France could become the decisive test because a nationalist victory there would have consequences far beyond French domestic politics. Brussels can isolate smaller states when they resist EU policy, but it cannot treat France as some troublesome peripheral member. If France begins demanding the restoration of national sovereignty, challenging centralized immigration policy, opposing further EU federalization, and refusing to blindly follow Brussels on foreign affairs, the entire political balance of the European Union changes.

Nationalism has already returned as a major political force, and France is demonstrating that the trend is continuing. The establishment can attempt to stop individual politicians, but it cannot indefinitely stop millions of people from demanding the return of sovereignty to the nation-state.