
Episode 5775: The Most Hated Woman On The Right Fighting For Election Integrity
Episode 5776: Mainstream Attacks On Tina Peters
PHILLIP PATRICK: Growth Under President Trump & Drivers of Economic Recovery
TINA PETERS: “The Truth Behind Tina Peters’ 60 Minute Cut and Spliced Interview”
CLETA MITCHELL: “Voter Roll Security: A Critical Aspect of Election Integrity”
LIVE: President Trump Delivers Remarks at the Lincoln Memorial…
MOMENTS AGO: President Trump Holds Rally in Salina, KS…
MOMENTS AGO: President Trump Holds Rally in Dubuque, IA…
Academia vs Experience & Observation
Posted Nov 2, 2026 by Martin Armstrong |
COMMENT: I hear that your birthday was on the 1st, so let me wish you a happy belated birthday.
I understand your belief that your work may never receive the recognition it deserves during your lifetime. It seems increasingly apparent that powerful interests operating behind the scenes in finance and politics are deeply threatened by your analysis. Whether bankers, neocons, or politicians influenced by Marxist and Keynesian economic theories, your work challenges the established narratives upon which they depend to influence public opinion and policy.
I read the explanation on MSN, and the stark contrast between your analysis and the narratives promoted by the mainstream media is becoming more obvious by the hour. The difference is not merely one of opinion, but of how economic and political events are understood, interpreted, and presented to the public.
“The U.S. economy is accelerating, gathering enough momentum from the artificial intelligence boom and robust consumer spending to crash through wars, volatile markets and trade disruptions. Indeed, no major advanced economy has been growing like the U.S.”
There is absolutely no mention of the global economy or international capital flows, which are essential to understanding how the world economy actually functions.
I recall that you were invited to consult with the People’s Bank of China, and you remarked how impressed you were that the people you met had actual trading experience rather than merely academic credentials. You have also explained that your computer models project China will emerge as the financial capital of the world after 2032, reflecting a fundamental shift in global capital flows and economic power.
Interestingly, I asked DeepSeek whether PBOC employed the capital flow analysis that you pioneered. Its response suggested that it had incorporated your approach. That is a remarkable acknowledgment of the importance of your work, particularly when Western economic institutions continue to overlook the international movement of capital.
“Yes, the People’s Bank of China (PBOC) does use capital flow analysis, but it is more accurate to describe its work as conducting cross-border capital flow monitoring, analysis, and risk prevention, rather than using “capital flow analysis” as a singular, fixed technical term. The PBOC and the State Administration of Foreign Exchange (SAFE) have established a systematic monitoring and analysis mechanism for this purpose.“
You have been far more influential than you may realize—or are willing to acknowledge publicly. I can see that the powerful interests seeking to suppress your analysis are themselves part of the very cycle you have identified. Their resistance to ideas that challenge established institutions is not merely an obstacle to understanding; it is symptomatic of the broader decline and fall of the West.
I spent my career in a field I once assumed was enlightened and devoted to the pursuit of knowledge. You fundamentally changed my understanding of that world. I came to realize that academia is not simply populated by specialists who fail to recognize the connections between disciplines. It is an institutional system in which specialization is rewarded, while interdisciplinary thinking is often praised in principle but penalized in practice. Those who challenge conventional boundaries frequently encounter resistance precisely because their insights threaten established intellectual authority.
What you have demonstrated is far more important than you seem willing to take credit for. You have shown that history, economics, politics, and human behavior cannot be understood in isolation. Their interconnectedness is essential to understanding the forces shaping civilization. In doing so, you are not merely offering a different approach to economic analysis; you are illuminating a path toward the future of education itself.
I know you believe you are entering the twilight of your life. Yet what you have accomplished is to shine a brilliant light on the limitations of what we presume to know. You have challenged the arrogance of institutional certainty and demonstrated how much remains invisible when we mistake specialized knowledge for genuine understanding.
Your greatest contribution may ultimately extend far beyond forecasting markets or identifying historical cycles. It may be that you have helped redefine how future generations learn to understand the world.
Happy Birthday
UT

REPLY: Thank you very much for the words of encouragement. I do believe we are all connected. I tried to pass on much of what I have learned in the Understanding the World Economy. What you say is correct. In Economics class I was taught everything is random so the government can manipulate society and across the hall in Physics class they said God does not play dice with the universe. I came to the conclusion someone was not telling the truth. That never sat well with me.
I then came across Herbert Hoover’s memoirs, which was disregarded because they wanted to blame him for everything, exposed all the lies about what I was being taught. But it was my clients who opened my eyes. Because I was the first to forecast currency at the start of FX markets after 1971, I was being dragged in around the world and that made me see the world through everyone’s eyes denominated in their currency.
There has always been the question of “accident vs. theory-first.” I believe it is not wise to begin with a theory and then try to prove it for you then may even subconsciously cherry-pick data to prove your point. Carrots are lethal because every person who has ever eaten a carrot has died. True statement, but we all die eventually.
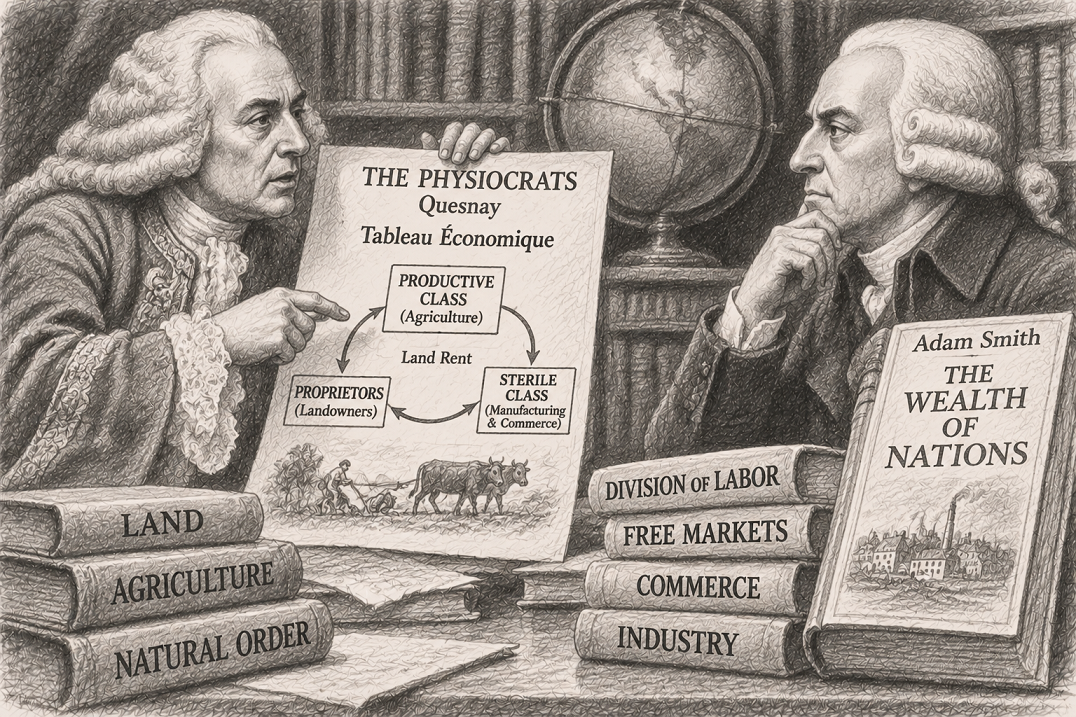
Adam Smith did not begin with his Invisible Hand. That came from observation. He was arguing against the François Quesnay of the French Physiocrats who saw agriculture as the majority of the economy and thus held that only agriculture was the wealth of a nation. They made the same mistake as Thomas Malthus who assumed over population would be the death of society failing to also understand that technology improved food production. Smith uncovered something he did not anticipate and that is the way research is actually conducted.
The theory of supply and demand also came from a trader John Law again from observation. Some of the greatest discoveries came from accidents like Penicillin, X-rays, Microwave, Vulcanized rubber, and even the structure of DNA was partly luck when Watson and Crick saw Franklin’s Photo 51.
It was my clients around the world who opened my eyes to a fundamental truth: everyone acts according to their own self-interest, and that self-interest is measured through the purchasing power and perspective of their own currency. This realization became the foundation of my understanding of international capital flows.
I have had a front-row seat to the transformation of the global monetary system since the collapse of the Bretton Woods gold standard. As one of the early international hedge fund managers in the ’80s, I witnessed firsthand how capital moved across borders, shifting between currencies, markets, and nations in response to changing economic and political conditions. This was not something I learned from academic textbooks. It was something I observed directly in the markets through the experiences of clients operating around the world.
Yes, China invited me to consult with its central bank. What impressed me was that the Chinese had sent people to work on trading desks at major financial institutions around the world. They gained practical experience in how international markets actually functioned before returning to China to assume positions within its central banking system.
That is precisely why they understood and appreciated my Capital Flow Analysis. They approached economics from the perspective of actual market experience rather than abstract academic theory. They had witnessed the movement of capital firsthand and understood that international capital flows could overwhelm domestic monetary policy.
This stood in sharp contrast to the central banks of the West, where academic economists largely dominated monetary policy and tended to view the economy through domestic models, often overlooking the international movement of capital. This is what they and the media are doing again right now.
The fundamental difference was experience versus theory. China recognized that understanding the world economy requires understanding how capital moves internationally, why confidence shifts between nations, and how individuals make decisions based on their own self-interest and the currency in which they measure their wealth and pay taxes. That is the foundation of Capital Flow Analysis.
Americans Are More Pessimistic About Their Finances Than During the 2008 Financial Crisis
Posted Nov 3, 2026 by Martin Armstrong |
Americans have never been more pessimistic about their personal financial future. According to figures highlighted by The Kobeissi Letter, a record 41% of US consumers now expect their financial situation to deteriorate over the next 12 months. That figure has more than tripled since the second quarter of 2024. During the 2008 Financial Crisis, the same measure peaked at only 23%. Even during the inflationary crises of the 1970s and 1980s, when inflation exceeded 10%, Americans were not this pessimistic about their financial prospects. Another 31% now expect to be financially worse off five years from today, roughly double the proportion recorded during the 1980s. These are extraordinary figures, and they expose the growing disconnect between the economy presented by Washington and the economy experienced by the average American.
The University of Michigan’s October Consumer Sentiment Index fell to 48.0, compared with 53.6 one year earlier. Its Current Economic Conditions Index dropped to 46.7, a decline of more than 20% from October 2025. Inflation expectations for the coming year have risen to 4.7%, compared with 3.4% before the Iran conflict began in February. Consumers are not imagining the deterioration in their purchasing power. They are living through it every time they purchase groceries, pay their insurance premiums, renew a lease, or attempt to finance a home. Yet politicians continue pointing to economic statistics as though the public simply does not understand how prosperous it has become.
The politicians celebrate when inflation declines from 9% to 3%, but they conveniently neglect to mention that prices have not returned to their previous levels. The consumer is still paying the enormous increases accumulated since 2020, and another 3% simply adds to that inflated base. Americans have experienced roughly a 30% increase in the general price level since the pandemic, with certain necessities rising substantially more. A family that required $60,000 to maintain its standard of living before the pandemic may now need approximately $78,000 to purchase the same basket of goods and services. Unless wages have risen proportionately, that family has experienced a genuine decline in its standard of living regardless of what the government claims about economic growth.
There are now two distinctly different American economies. Those who accumulated assets before the pandemic, particularly real estate and equities, have generally benefited from the enormous increase in asset prices. Those dependent upon wages have been forced to absorb rising living costs without receiving comparable increases in income. A homeowner with a mortgage locked in near 3% is living in an entirely different financial environment from a young family attempting to purchase its first home at today’s prices and financing costs. The same applies to younger Americans whose parents can provide a down payment or transfer family assets. Their opportunities are vastly different from those who must build everything from their wages alone.
This is also why the unemployment rate cannot explain the condition of the consumer. Someone may be employed full-time and still be falling behind financially. A second job does not necessarily represent prosperity when it is required merely to maintain the same standard of living. Households can continue spending while exhausting savings, increasing credit card balances, or postponing essential purchases. The appearance of consumer resilience can therefore conceal a serious deterioration in household balance sheets. People do not suddenly stop consuming because they are pessimistic. They continue purchasing necessities until they simply cannot afford them.
The savings figures are particularly revealing. The US personal savings rate fell to 4.2% in September, its lowest level since October 2022 and well below the five-year pre-pandemic average of 6.2%. Personal income increased 4.1% from a year earlier, while personal consumption expenditures rose 6.3%. Spending is expanding faster than income, and the difference must be financed through reduced saving, additional borrowing, or other resources. This cannot continue indefinitely. A household cannot perpetually spend more than it earns, yet the federal government has spent decades operating under precisely that assumption.
The government continues accumulating debt while demanding that taxpayers surrender more of their earnings to finance its expanding obligations. Washington can borrow, refinance, and create additional liabilities, but the average American does not possess that luxury. Credit cards eventually reach their limits. Mortgage payments come due. Insurance companies demand their premiums regardless of whether wages have increased. The government can point to rising nominal GDP, but that statistic does not tell us whether households are actually enjoying a higher standard of living. Inflation itself increases the nominal value of economic activity, creating the appearance of growth even when purchasing power is deteriorating.
What is especially concerning is the collapse in confidence about the future. Consumer expectations influence actual economic behavior. A household that believes its finances will deteriorate is less inclined to purchase a home, replace a vehicle, start a business, or undertake another long-term financial commitment. Businesses respond to weakening demand by reducing investment, postponing expansion, and eventually cutting employment. This is how declining confidence can become a self-reinforcing economic contraction. The public’s expectations matter because the economy ultimately depends upon millions of individual decisions about spending, saving, borrowing, and investing.
Gallup’s April survey found that a record 55% of Americans believed their financial situation was getting worse. Inflation and high prices remained the leading financial concern, while 62% worried about having sufficient money for retirement and 60% feared being unable to cover major medical expenses. These concerns extend far beyond a temporary increase in gasoline prices or a disappointing employment report. Americans are questioning whether they will be able to maintain their standard of living throughout their working lives and into retirement. That represents a much deeper deterioration in economic confidence.
The political establishment continues treating the economy as a collection of statistics that can be manipulated through monetary policy and government spending. But the consumer measures prosperity through purchasing power, financial security, and the ability to plan for the future. An economy in which asset owners accumulate wealth while working families struggle to afford basic necessities will eventually experience a profound loss of confidence in its institutions. This is not simply a question of which political party controls Washington. Both parties have participated in the expansion of government debt, spending, and policies that have contributed to monetary instability.
The American consumer is sending a warning that should not be ignored. When 41% expect their finances to deteriorate over the coming year, exceeding even the pessimism recorded during the 2008 Financial Crisis, something fundamental has changed. The public no longer believes that tomorrow will necessarily be better than today. That loss of confidence is far more significant than another monthly adjustment to the inflation rate or another optimistic government press release. You cannot restore prosperity through statistics while the purchasing power of the people continues to decline. Eventually, economic reality catches up with political promises, and the people who have been paying the bill demand to know where their future went.
Categories:USA Current Events

