The Black Sea Is Becoming Uninsurable


Posted Originally on: Oct 9, 2026 by Martin Armstrong |
Black Sea now the 'most dangerous commercial shipp... | myKN

The Black Sea is rapidly becoming too dangerous for international commerce. Commercial vessels have been attacked near Romania, Bulgaria, Ukraine, and Russia within days of one another. Ships carrying agricultural products and petroleum are being dragged into a war. Politicians seem to forget that global trade depends on moving goods safely between nations. Once commercial shipping becomes a target, the economic consequences extend far beyond Russia and Ukraine. Insurance premiums rise, freight rates increase, and eventually those additional costs are passed directly to consumers who have absolutely nothing to do with this war.

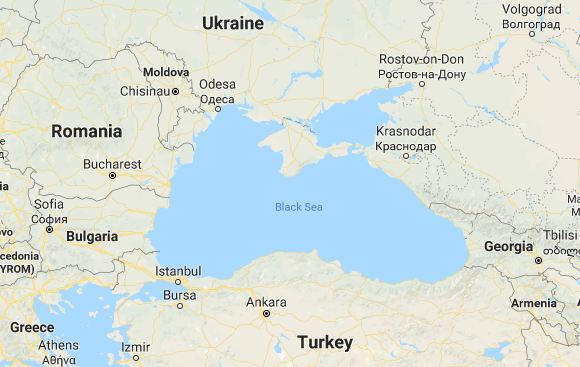
On October 5, a commercial vessel caught fire and sank off Romania, killing two people. The following day, two additional merchant vessels were struck by drones inside Bulgaria’s exclusive economic zone, with one reportedly sinking. Another vessel carrying agricultural oil was attacked near Odesa, while an oil tanker was struck off Russia’s Black Sea coast. Responsibility for some of these incidents remains disputed, but the economic consequences do not depend on which side launched the drones. Shipping companies must now calculate the possibility of losing an entire vessel and its cargo. Insurers must price that risk, and nobody in this business operates on charity.

People do not understand how quickly the cost of war moves through the global economy. A ship owner facing increased war-risk insurance premiums will demand higher compensation to enter dangerous waters. Charter rates rise, cargo owners seek alternative routes, and ports become increasingly expensive to operate. If insurance becomes unavailable at a commercially reasonable price, vessels simply stop sailing certain routes. Every additional expense becomes part of the final price, whether that means wheat, cooking oil, gasoline, or the thousands of other products.
Black Sea Map

The Black Sea is particularly important because Russia and Ukraine are major agricultural exporters. Egypt, Turkey, and numerous countries across Africa and the Middle East depend on grain moving through this region. These governments cannot simply replace millions of tonnes of wheat overnight without paying more. We have already seen how disruptions to food supplies can contribute to political instability. The Arab Spring was not merely some spontaneous movement for democracy. Rising food prices, unemployment, and deteriorating living standards helped create the conditions for unrest. When people cannot afford to feed their families, political stability becomes impossible.

The Black Sea provides access to important oil terminals and shipping routes, fueling the energy crisis. Attacking tankers and energy infrastructure increases the cost of transporting petroleum regardless of whether the underlying supply has been destroyed. Insurance companies do not distinguish between political propaganda and the actual probability of a vessel being struck.

What makes this especially absurd is that Europe is already struggling with the consequences of its own energy policies, sanctions, and declining industrial competitiveness. Germany has watched energy-intensive industries suffer while Brussels continues demanding greater military expenditure. Now the same geopolitical confrontation threatens to increase the cost of transporting energy and agricultural commodities. The public is expected to pay higher taxes to finance the war, higher energy bills because of the war, and higher food prices as the commercial consequences spread. These people in government never seem to consider that ordinary citizens must somehow pay for all of this.

The Black Sea does not have to be formally closed for the economic damage to become serious. It only has to become dangerous enough that commercial operators begin questioning whether the profits justify the risks. Once that happens, the market will make decisions that politicians cannot reverse with another press conference. The War Cycle is intensifying, and the consequences will not remain confined to the battlefield.

Categories:World Trade
Trucking Bankruptcies


Posted Originally on: Oct 9, 2026 by Martin Armstrong |

Truckers

At least 16 trucking, delivery, and transportation companies entered bankruptcy proceedings between late August and September 21. These filings extend across general freight, construction materials, agricultural hauling, and even an Amazon delivery contractor. Some are seeking Chapter 11 protection to reorganize; others have entered Chapter 7 liquidation. We should not pretend every filing means a company has closed, but we should certainly ask why businesses moving the goods this economy depends upon are struggling to remain solvent.

Globemaster reported between $500,000 and $1 million in assets against liabilities ranging from $1 million to $10 million. Pacer Transport listed less than $50,000 in assets against $1 million to $10 million in liabilities. FreightWaves also points to rising diesel prices and elevated operating costs. A trucker cannot pay for fuel with a politician’s speech about how well the economy is doing.

I keep coming back to the distinction between spending and prosperity. A household spending more money to obtain the same necessities has not become wealthier. Neither has a business whose revenue rises while its expenses rise faster. You can move more dollars through an economy while leaving the people doing the work with less. That is why aggregate figures can look respectable while the operator sitting at his kitchen table discovers there is nothing left after paying everybody else.

If customers resist higher freight charges, the carrier absorbs the pressure until there is no margin left. Borrowing may buy time, but another loan does not repair an operation that cannot consistently earn enough to meet its obligations. Eventually, the creditor wants cash.

Energy costs are part of this squeeze. Fuel must be paid for immediately, while payment for hauling a load may come later. A carrier can collect a fuel surcharge and still face a cash shortage before that money arrives. Add truck payments, insurance, maintenance, and wages, and there is very little room for error. If freight revenue cannot keep pace with those bills, running the truck may produce activity without producing a profit. That is how a business can remain busy right up to the day it goes bankrupt.

When smaller operators disappear, surviving businesses may acquire their equipment and customers. That can help restore balance in an overcrowded market, but the adjustment comes through lost businesses, damaged credit, and interrupted livelihoods. The man who spent years building a fleet does not experience this as an encouraging economic correction. He experiences it as the destruction of everything he worked for.

These bankruptcies alone do not prove the entire country is in recession. They do show why I would pay attention to the businesses carrying the goods rather than accept every reassuring national average at face value. An economy needs people willing to take risks and enough profit to justify taking them. Keep squeezing that profit and eventually the trucks, the jobs, and the tax revenue go with it. Washington can roll over its debts and congratulate itself on another spending package. The private businessman has to make payroll on Friday.

Categories:USA Current Events

The Energy Crisis Is Making Travel More Expensive


Posted Originally on: Oct 9, 2026 by Martin Armstrong |

plane

Ryanair chief Michael O’Leary says jet fuel is now about 50% more expensive than before the Iran war and expects those elevated costs to persist for another 12 to 18 months. Reuters reports that he has previously warned ticket prices could rise by as much as 20% next summer. These are forecasts, but the pressure on airline margins is already here. “We are all facing an enormous cost challenge next year,” O’Leary said.

People assume that once the fighting stops, everything returns to normal. A ceasefire does not repair a refinery or restore damaged infrastructure overnight. Nor does a retreat in crude oil automatically produce an equivalent decline in the price of usable aviation fuel. Airlines need the finished product, delivered where their aircraft operate. You cannot fly a plane on a press release announcing that the oil market has stabilized.

Fuel hedging can buy an airline time, but it cannot permanently insulate the business from higher costs. As those contracts expire, management must decide how much it can pass to passengers and which routes remain worth operating. Raise fares too far and customers reconsider the trip. Absorb the increase and profitability suffers. Cheap tickets depend upon the economics of providing them, however much politicians would like to pretend otherwise.

Lufthansa is facing the same squeeze. CEO Carsten Spohr expects this year’s additional fuel costs to exceed the €1.5 billion previously projected, despite extensive hedging. The airline maintained its operating profit forecast, but rising costs are weighing on its turnaround plans. You can have passengers willing to fly and still struggle to improve profitability when the cost of carrying them keeps climbing. Hedging buys time; it does not manufacture fuel or permanently remove the expense. Those who believe an airline can simply absorb every increase should try running one.

EasyJet is already responding by cutting flights. The Financial Times reports that the airline will remove another 600,000 to 700,000 seats from its winter schedule, following an earlier reduction of about 700,000, to limit spending on expensive fuel. Routes that made sense at one fuel price become less attractive at another, and management pulls back. Fewer seats mean fewer opportunities to travel, with potential consequences for the hotels, restaurants, and businesses waiting for those visitors. Governments authorize military operations, and a holiday business hundreds of miles away discovers that its customers have fewer flights available to reach it. The consequences reach well beyond the airline. That is how an energy shock works its way through an economy, taking income from one business after another.

I have little patience for governments that discuss war as though its economic consequences can be contained within the country being attacked. Energy moves across borders, and so does the damage when its supply is disrupted. The public pays through fuel bills, freight charges, food prices, and now the cost of visiting family or taking a holiday. Officials can authorize another operation with a signature. The businesses trying to remain profitable must work out how to pay for the consequences.

Categories:Energy

Market Talk – October 8, 2026


Posted Market Talk – October 8, 2026

Posted Originally on: Oct 8, 2026 by Martin Armstrong |

Market Talk 2017

ASIA:

The major Asian stock markets had a negative day today:

• NIKKEI 225 decreased 993.60 points or -1.42% to 69,042.11

• Shanghai decreased 30.29 points or -0.79% to 3,811.904

• Hang Seng decreased 344.71 points or -1.43% to 23,785.79

• ASX 200 decreased 66.80 points or -0.77% to 8,660.90

• SENSEX decreased 1,045.46 points or -1.44% to 71,593.24

• Nifty50 decreased 371.25 points or -1.64% to 22,231.80

The major Asian currency markets had a mixed day today:

• AUDUSD decreased 0.00166 or -0.24% to 0.69464

• NZDUSD decreased 0.00083 or -0.15% to 0.55917

• USDJPY increased 0.23 or 0.15% to 158.304

• USDCNY increased 0.00257 or 0.04% to 6.70523

The above data was collected around 12:10 EST.

Precious Metals:

•  Gold increased 1.08 USD/t oz. or 0.03% to 4,112.06

•  Silver decreased 1.02 USD/t. oz. or -1.71% to 58.728

The above data was collected around 12:13 EST.

EUROPE/EMEA:

The major Europe stock markets had a negative day today:

•  CAC 40 decreased 39.52 points or -0.51% to 7,729.69

•  FTSE 100 decreased 16.90 points or -0.16% to 10,441.60

•  DAX 30 decreased 297.39 points or -1.18% to 24,806.97

The major Europe currency markets had a negative day today:

• EURUSD decreased 0.00067 or -0.06% to 1.11898

• GBPUSD decreased 0.00044 or -0.03% to 1.32095

• USDCHF decreased 0.00002 or 0.00% to 0.83337

The above data was collected around 12:14 EST.

AMERICAS:

US Markets:

  • DJIA advanced by 51.77 points (0.1%) to 51,231.64
  • S&P 500 declined by 36.41 points (0.47%) to 7,765.36
  • NASDAQ declined by 345.35 points (1.25%) to 27,193.34
  • Russell 2000 advanced by 0.74 points (0.03%) to 2,793.941

Canada:

  • TSX Composite advanced by 102.65 points (0.29%) to 35,144.51
  • TSX 60 advanced by 5.78 points (0.28%) to 2,070.7

Brazil:

  • Bovespa advanced by 2,099.94 points (1.03%) to 206,402.27

ENERGY:

The oil markets had a mixed day today:

•  Crude Oil increased 3.054 USD/BBL or 3.46% to 91.334

•  Brent increased 3.996 USD/BBL or 3.99% to 104.196

•  Natural gas decreased 0.087 USD/MMBtu or -2.72% to 3.1160

•  Gasoline increased 0.09 USD/GAL 2.78% to 3.3242

•  Heating oil increased 0.223 USD/GAL or 4.82% to 4.8457

The above data was collected around 12:17 EST.

•  Top commodity gainers: Brent (3.99%), Heating Oil (4.82%), Crude Oil (3.46%) and Bitumen (6.59%)

•  Top commodity losers: Natural Gas (-2.72%), Aluminum (-2.44%), Sugar (-2.61%) and Silver (-1.71%)

The above data was collected around 12:29 EST.

BONDS:

Japan 3.0860% (-2.68bp), US 2’s 4.80% (+0.027%), US 10’s 5.2800% (-1.5bps); US 30’s 5.64 (-0.038%), Bunds 3.4645% (-1.6bp), France 4.8850% (-0.68bp), Italy 4.5970% (-4.56bp), Turkey 32.75% (-7bp), Greece 4.4590% (-6.35bp), Portugal 3.9970% (-1.19bp); Spain 4.114% (-3.18bp) and UK Gilts 5.4467% (+1.22bp)

The above data was collected around 12:32 EST.

Categories:Market Talk Oct 8, 2026 by Martin Armstrong |

Market Talk 2017

ASIA:

The major Asian stock markets had a negative day today:

• NIKKEI 225 decreased 993.60 points or -1.42% to 69,042.11

• Shanghai decreased 30.29 points or -0.79% to 3,811.904

• Hang Seng decreased 344.71 points or -1.43% to 23,785.79

• ASX 200 decreased 66.80 points or -0.77% to 8,660.90

• SENSEX decreased 1,045.46 points or -1.44% to 71,593.24

• Nifty50 decreased 371.25 points or -1.64% to 22,231.80

The major Asian currency markets had a mixed day today:

• AUDUSD decreased 0.00166 or -0.24% to 0.69464

• NZDUSD decreased 0.00083 or -0.15% to 0.55917

• USDJPY increased 0.23 or 0.15% to 158.304

• USDCNY increased 0.00257 or 0.04% to 6.70523

The above data was collected around 12:10 EST.

Precious Metals:

•  Gold increased 1.08 USD/t oz. or 0.03% to 4,112.06

•  Silver decreased 1.02 USD/t. oz. or -1.71% to 58.728

The above data was collected around 12:13 EST.

EUROPE/EMEA:

The major Europe stock markets had a negative day today:

•  CAC 40 decreased 39.52 points or -0.51% to 7,729.69

•  FTSE 100 decreased 16.90 points or -0.16% to 10,441.60

•  DAX 30 decreased 297.39 points or -1.18% to 24,806.97

The major Europe currency markets had a negative day today:

• EURUSD decreased 0.00067 or -0.06% to 1.11898

• GBPUSD decreased 0.00044 or -0.03% to 1.32095

• USDCHF decreased 0.00002 or 0.00% to 0.83337

The above data was collected around 12:14 EST.

AMERICAS:

US Markets:

  • DJIA advanced by 51.77 points (0.1%) to 51,231.64
  • S&P 500 declined by 36.41 points (0.47%) to 7,765.36
  • NASDAQ declined by 345.35 points (1.25%) to 27,193.34
  • Russell 2000 advanced by 0.74 points (0.03%) to 2,793.941

Canada:

  • TSX Composite advanced by 102.65 points (0.29%) to 35,144.51
  • TSX 60 advanced by 5.78 points (0.28%) to 2,070.7

Brazil:

  • Bovespa advanced by 2,099.94 points (1.03%) to 206,402.27

ENERGY:

The oil markets had a mixed day today:

•  Crude Oil increased 3.054 USD/BBL or 3.46% to 91.334

•  Brent increased 3.996 USD/BBL or 3.99% to 104.196

•  Natural gas decreased 0.087 USD/MMBtu or -2.72% to 3.1160

•  Gasoline increased 0.09 USD/GAL 2.78% to 3.3242

•  Heating oil increased 0.223 USD/GAL or 4.82% to 4.8457

The above data was collected around 12:17 EST.

•  Top commodity gainers: Brent (3.99%), Heating Oil (4.82%), Crude Oil (3.46%) and Bitumen (6.59%)

•  Top commodity losers: Natural Gas (-2.72%), Aluminum (-2.44%), Sugar (-2.61%) and Silver (-1.71%)

The above data was collected around 12:29 EST.

BONDS:

Japan 3.0860% (-2.68bp), US 2’s 4.80% (+0.027%), US 10’s 5.2800% (-1.5bps); US 30’s 5.64 (-0.038%), Bunds 3.4645% (-1.6bp), France 4.8850% (-0.68bp), Italy 4.5970% (-4.56bp), Turkey 32.75% (-7bp), Greece 4.4590% (-6.35bp), Portugal 3.9970% (-1.19bp); Spain 4.114% (-3.18bp) and UK Gilts 5.4467% (+1.22bp)

The above data was collected around 12:32 EST.

Categories:Market Talk

Market Talk – October 7, 2026


Posted Oct 7, 2026 by Martin Armstrong

Market Talk 2017

ASIA:

The major Asian stock markets had a negative day today:

• NIKKEI 225 decreased 648.27 points or -0.92% to 70,035.71

• Shanghai closed

• Hang Seng decreased 150.06 points or -0.62% to 24,130.50

• ASX 200 decreased 8.00 points or -0.09% to 8,727.70

• SENSEX decreased 429.10 points or -0.59% to 72,638.70

• Nifty50 decreased 173.05 points or -0.76% to 22,603.05

The major Asian currency markets had a negative day today:

• AUDUSD decreased 0.00158 or -0.23% to 0.69669

• NZDUSD decreased 0.00193 or -0.34% to 0.56047

• USDJPY decreased 0.192 or -0.12% to 157.906

• USDCNY decreased 0.00012 or -0.00% to 6.70146

The above data was collected around 14:49 EST.

Precious Metals:

•  Gold decreased 52.83 USD/t oz. or -1.27% to 4,111.72

•  Silver decreased 1.462 USD/t. oz. or -2.38% to 59.874

The above data was collected around 14:51 EST.

EUROPE/EMEA:

The major Europe stock markets had a negative day today:

•  CAC 40 decreased 95.86 points or -1.22% to 7,769.21

•  FTSE 100 decreased 83.19 points or -0.79% to 10,458.50

•  DAX 30 decreased 344.83 points or -1.35% to 25,104.36

The major Europe currency markets had a mixed day today:

• EURUSD decreased 0.00609 or -0.54% to 1.11985

• GBPUSD decreased 0.00566 or -0.43% to 1.32192

• USDCHF increased 0.0012 or 0.14% to 0.83290

The above data was collected around 14:57 EST.

AMERICAS:

US Markets:

  • DJIA declined by 341.41 points (0.66%) to 51,179.87
  • S&P 500 declined by 17.16 points (0.22%) to 7,801.77
  • NASDAQ declined by 61.2 points (0.22%) to 27,538.691
  • Russell 2000 declined by 37.82 points (1.34%) to 2,792.481

Canada:

  • TSX Composite declined by 606.46 points (1.7%) to 35,043.05
  • TSX 60 declined by 34.02 points (1.62%) to 2,065.04

Brazil:

  • Bovespa declined by 1,486.9 points (0.72%) to 204,348.39

ENERGY:

The oil markets had a mixed day today:

•  Crude Oil decreased 0.945 USD/BBL or -1.06% to 88.495

•  Brent decreased 0.127 USD/BBL or -0.13% to 100.453

•  Natural gas increased 0.0888 USD/MMBtu or 2.85% to 3.2028

•  Gasoline decreased 0.0355 USD/GAL -1.08% to 3.2377

•  Heating oil increased 0.0685 USD/GAL or 1.50% to 4.6379

The above data was collected around 15:00 EST.

•  Top commodity gainers: Natural Gas (2.85%), Heating Oil (1.50%), Rice (2.78%) and Lead (1.14%)

•  Top commodity losers: Platinum (-4.11%), Coffee (-3.47%), Palladium (-4.47%) and Cocoa (-3.04%)

The above data was collected around 15:05 EST.

BONDS:

Japan 3.1130% (+0.47bp), US 2’s 4.77% (-0.036%), US 10’s 5.2780% (-1.1bps); US 30’s 5.66 (+0.001%), Bunds 3.4727% (-0.81bp), France 4.8920% (+13.72bp), Italy 4.6396% (+10.44bp), Turkey 32.75% (-7bp), Greece 4.5225% (+11.06bp), Portugal 4.0089% (+5.63bp); Spain 4.146% (+7.06bp) and UK Gilts 5.4262% (+2.42bp)

The above data was collected around 15:08 EST.

Debt Crisis Reflected in Bond Market


Posted Oct 8, 2026 by Martin Armstrong |

Bond Yields Are the Highest in a Generation. How Much International  Exposure Makes Sense For Your Portfolio?

The bond market is beginning to expose what governments have desperately tried to hide. Britain’s 30-year yield has now reached 6.036%, the highest since 1998. The US 30-year yield reached 5.7041%, its highest level in 24 years, while France’s 10-year yield has pushed above 5%. This is happening across the developed world because governments borrowed endlessly when money was cheap and somehow convinced themselves that interest rates would remain artificially low forever.

This is precisely how a sovereign debt crisis begins. It does not require a government to announce that it is bankrupt. Capital simply begins demanding more interest to lend that government money. The higher the interest rate rises, the more expensive it becomes to refinance the existing debt, which creates an even larger deficit that requires even more borrowing. Government then enters a vicious cycle of borrowing simply to service what it already borrowed.

France is becoming the one to watch in Europe. Citadel’s Ken Griffin said France now has “no room for mistakes.” Investors are beginning to distinguish between European governments rather than treating every euro-denominated bond as essentially the same risk. Money has been moving toward Germany, Switzerland and the Netherlands while France comes under pressure. Italy and Spain are naturally being watched for contagion.

This exposes one of the fundamental flaws behind the euro. Brussels created one currency but never created one government, one debt, or one economy. A German bond is not a French bond simply because both are denominated in euros. When confidence begins to crack, capital looks at who actually owes the money. That is when spreads widen and all the political promises about European solidarity mean very little.

The same problem is unfolding in the United States. Washington has accumulated more than $40 trillion in debt and must continuously roll over enormous amounts of old debt while issuing still more to finance current deficits. The Treasury cannot dictate what investors must accept forever. If the market wants 5%, 6% or more to absorb government paper, then that becomes the cost of borrowing regardless of what some politician or central banker would prefer.

This is also why people waiting for the Fed to magically return everything to pandemic-era interest rates do not understand the bond market. The Fed controls the short end directly. It does not simply decree where the 10-year or 30-year Treasury must trade. Those rates reflect inflation, supply and demand for government debt, currency expectations, fiscal credibility and international capital flows. The government can intervene, buy bonds and manipulate the market temporarily, but eventually somebody has to own the debt.

Governments enjoyed decades of declining interest rates and behaved as if that were a permanent feature of civilization. They expanded welfare states, pensions, bureaucracies and military spending while refinancing yesterday’s promises at cheaper rates. Now the refinancing works in reverse. Debt issued at 1% or 2% matures and must be replaced at 4%, 5% or 6%. Nothing new has to be purchased for the interest expense to explode. They are simply paying more for the same old debt.

This is where the political crisis begins because governments will not voluntarily admit that they created promises they can no longer afford. They will raise taxes, cut services, raid pensions, impose regulations on capital, and blame speculators before admitting that the problem was their own borrowing. The taxpayer will be told to sacrifice because politicians spent money for decades without ever asking who would ultimately pay the bill.

The bond market is beginning to answer that question. It is pricing governments according to confidence, and confidence cannot be legislated into existence. When capital starts questioning sovereign debt, politicians can give all the speeches they want. The market ultimately decides what their promises are worth.

The Fed Does Not Control Your Mortgage


Posted Oct 8, 2026 by Martin Armstrong |

Home Mortgage - Overview, How It Works, Types, & Payments

The average 30-year mortgage has jumped to 7.49%, the highest since November 2023. This is happening while everyone continues to obsess over what the Federal Reserve will do at its next meeting as if the Fed chairman personally sets the mortgage rate at your local bank. He does not. Mortgage rates are tied far more closely to the bond market, particularly longer-term Treasury yields, and those yields have been rising because investors are demanding more to lend money long term.

The US 30-year Treasury yield has now reached its highest level in 24 years. That is the part most real estate salesmen conveniently leave out when they tell people to wait for the Fed to cut rates. The federal funds rate is an overnight rate. A mortgage may remain on the books for 30 years. Banks and investors therefore care about inflation, Treasury yields, government borrowing, credit risk and where interest rates may be years from now. Cutting the overnight rate does not magically erase those risks.

Washington has also become the largest competitor for capital in the room. The federal debt has exceeded $40 trillion and Treasury must continuously sell enormous quantities of securities to finance deficits and refinance maturing debt. Investors have choices. If they can earn around 5% lending to the US government, they are not going to finance somebody’s house for 3% simply because a realtor says mortgage rates should come down.

The pandemic housing market was an anomaly. The Fed drove rates to zero, bought trillions in securities, and helped push mortgage rates below 3%. Buyers became accustomed to borrowing money at rates that made no economic sense over the long term. That distorted home prices, encouraged speculation and created today’s lock-in problem because millions of homeowners understandably refuse to surrender mortgages carrying rates that may never return in their lifetimes.

Even if the Fed suddenly cut rates to zero at its next meeting, that would not automatically return mortgage rates to 3%. If investors believed such a move would reignite inflation, long-term Treasury yields could actually rise. The bond market is not obligated to follow the Fed blindly, and right now the market is looking at enormous government deficits, higher energy costs, persistent inflation, and an endless supply of new sovereign debt.

Warsh could walk into the Fed tomorrow and slash short-term rates dramatically, and he still could not order mortgage rates back to 3%. He does not control the 10-year Treasury or control what investors demand to hold mortgage-backed securities, and he certainly cannot force private capital to lend money for 30 years at a rate it considers too low. If the bond market believes inflation, government borrowing, or geopolitical risk requires a higher return, long-term yields can rise even as the Fed cuts. Warsh can influence the cost of money at the short end, but he cannot repeal the market. Washington may believe it controls interest rates. Capital ultimately decides what it is willing to accept.

The obsession with the Fed is therefore misplaced. The problem is much larger than one central bank meeting. Government debt is competing for capital, the long end of the bond market is demanding higher yields, and the era of virtually free money distorted housing for more than a decade. Mortgage rates are simply reflecting that reality.

Merz – Follow the Money


Posted Oct 8, 2026 by Martin Armstrong |

Diplomacy Merz_on_Ukraine_No_hope_left_for_a_diplomatic_solution_t

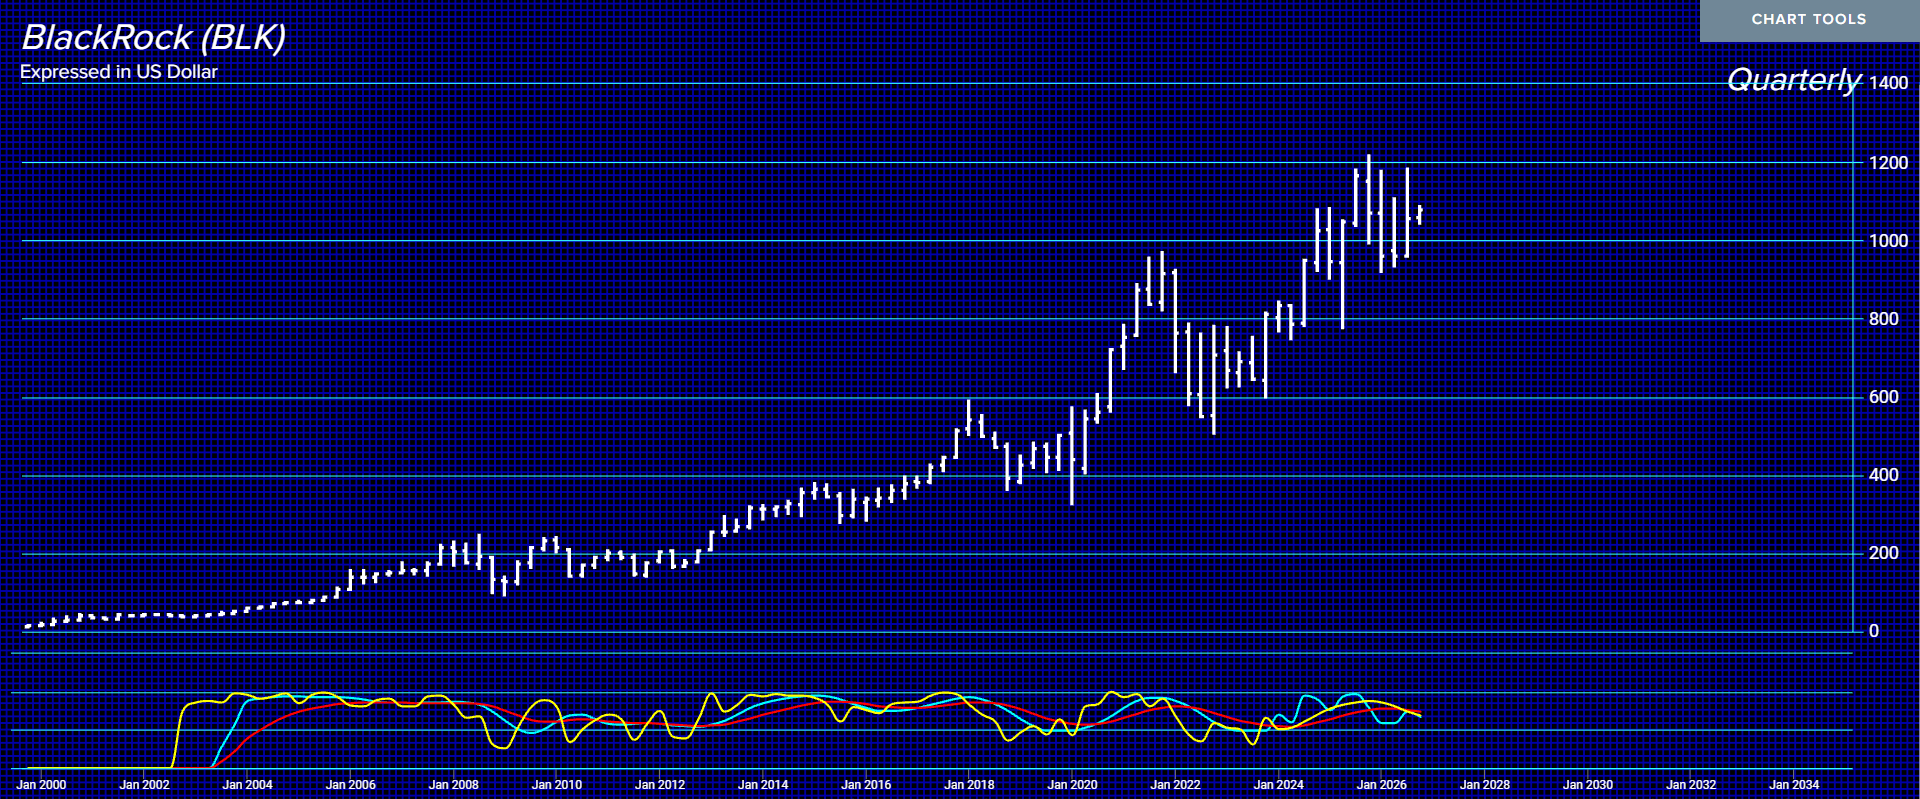
Merz, former BlackRock chairman in Germany, I believe has a serious conflict of interest. I know, people point out that he is the grandson of Nazi party official, Josef Paul Sauvigny, who joined the SA in 1933. However, if Ukraine loses the war, BlackRock’s $800 billion fund to “rebuild Ukraine” will become one of the biggest losses in financial history. European Business Magazine, February 28, 2026 wrote: “BlackRock is leading an $800 billion investment framework to rebuild Ukraine, focusing on agriculture, critical minerals, energy and infrastructure. They intend to to inject private capital into reconstruction projects in exchange for long-term concessions and resource extraction rights. Yet, on the other side of the monopoly board, they have nearly $40 billion invested in the military establishment.

BlackRock’s Stake (% of Outstanding)
RTX Corporation (formerly Raytheon) 8.10% $21.1 billion
Northrop Grumman 8.29% $3.9 billion
Lockheed Martin 7.73% $5.78 billion
General Dynamics 6.4%

Blackrock Q Tec 10 7 26
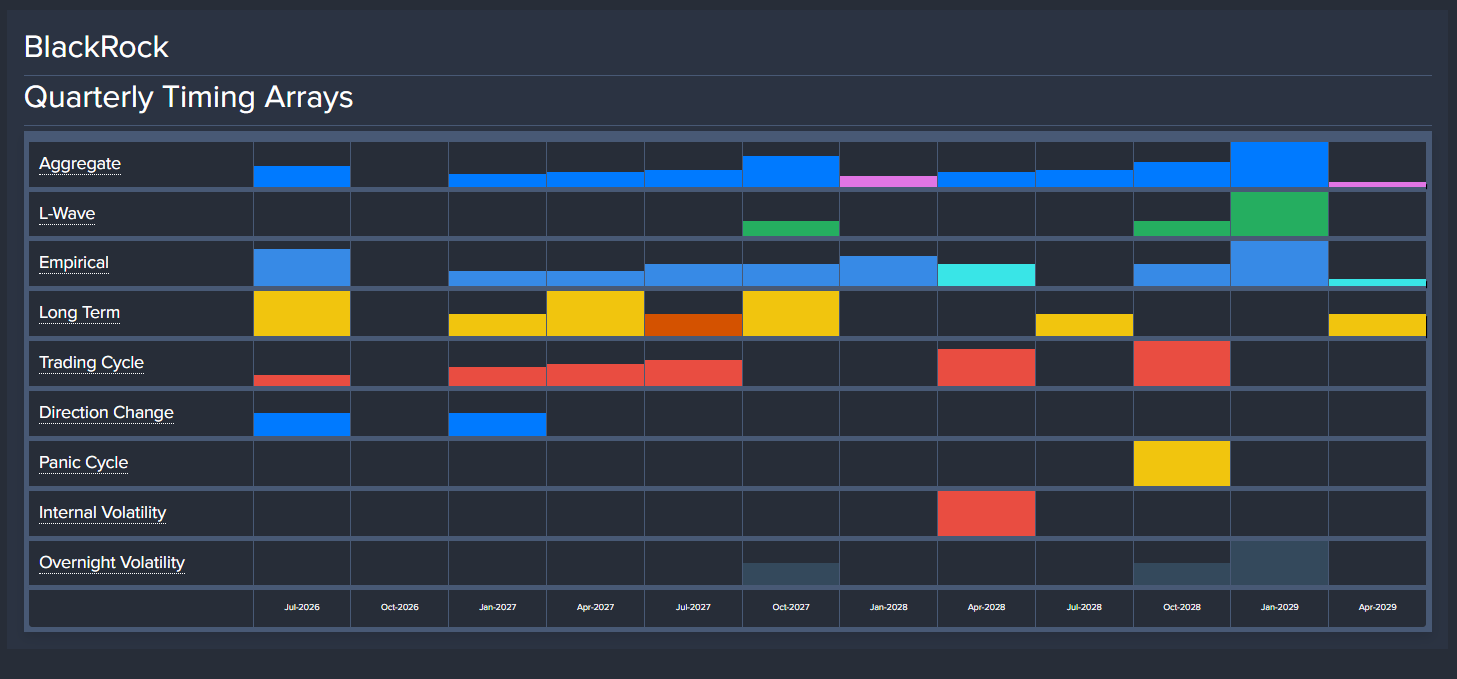
Blackrock Q Arrary 10 7 26
ECM Ukraine 8.6 R

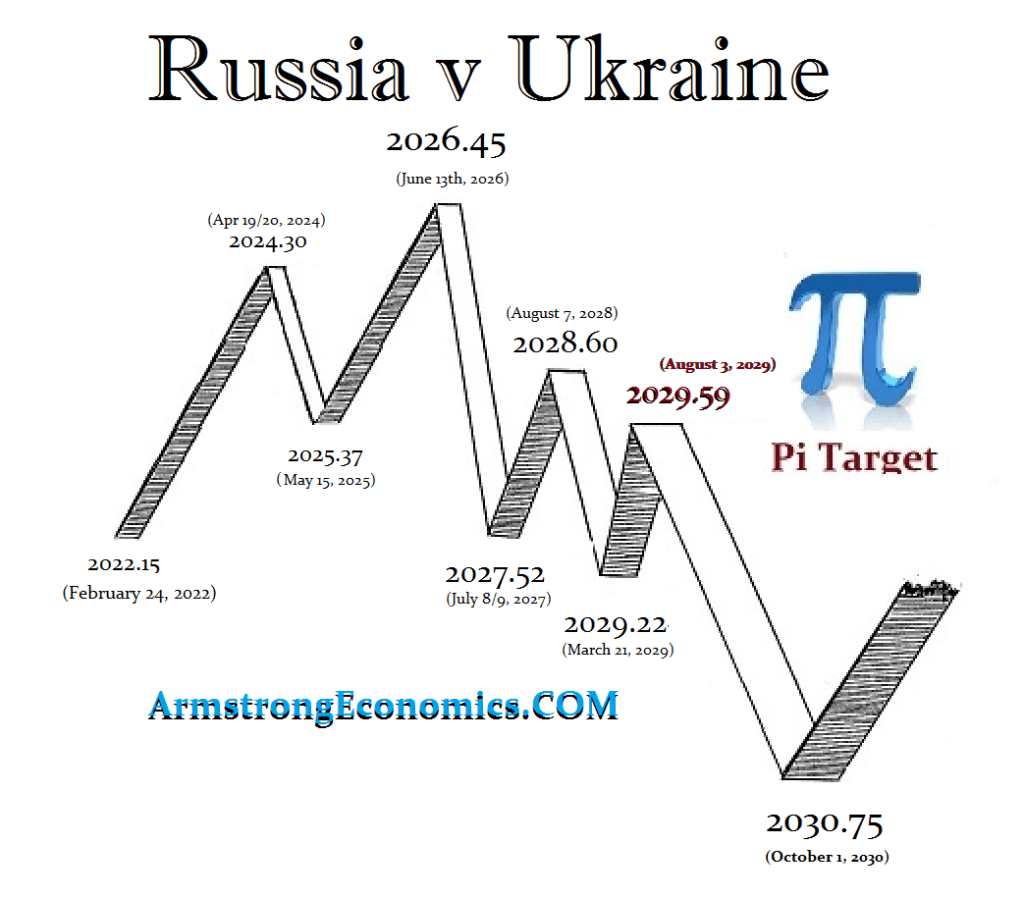
As I have warned, Ukraine will lose this war and it does not appear it will even be able to survive beyond the Pit target for the 3rd quarter 2029. We see even a major turning point on Blackrock at that time as well. Merz seems to be puttin Blackrock before Germany. You cannot claim you are already at war with Russia, risk the destruction of Germany, and have Blackrock making a profit. We saw Dick Cheney get his old company Halliburton the contracts for the Iraq War and when it came time to investigate, on March 11, 2007, Halliburton announced it would open a corporate headquarters in Dubai and relocate its CEO, David Lesar, there.

IMF Dinner National Gallery

I fought against the “CLUB” and they were NEVER actually traders. They ALWAYS sought the guaranteed trades. They routinely rigged markets and bribed officials. As I have said, I was invited to a black-tie dinner where they rented the entire National Galley to put on a dinner for the IMF. I was invited to show me that they had the IMF in their back pocket. This is the real world. You can bet that there is a lot riding on this war and it is NEVER about what they claim – DEMOCRACY. They could care less about that. The EU was established to eliminate democracy. Ursula is appointed – not elected.

Follow the Money

Just Follow the Money

Does Ukraine have to Win for the Blackrock $800 Billion Deal?

Has Poland Announced It Will Keep All Russian Money Even if They Agreed to Peace Somehow Connected?

Radoslaw Sikorski

Polish FM Radosław Sikorski who is a huge NEOCON has declared:

  • “Kremlin’s assets frozen in Europe and never going back to Russia”
  • “They can be used [the assets] now to help prevent further destruction and make future reconstruction cheaper”
  • “If the war ends tomorrow, Russia will remain a threat. We cannot afford to once again underestimate the danger of Moscow’s militarism.”

Categories:Uncategorized

Blog Alerts

Envelop Subscribe to alerts for each new postEmail *
Related posts
market-talk-2017

Market Talk – October 5, 2026

October 5, 2026

mob riot -2

European Population Replacement Going Spectacular

October 4, 2026

Democrates Senate Tech 2026F

The ’26 Midterms – the Demise of Both Republicans & Democrats

October 2, 2026

Human,Silhouette,In,Back,Lighting,In,Tunnel,Exit

The Light at The End of the Tunnel – It’s Not All Doom & Gloom

October 1, 2026

PRIVATE BLOG

PRIVATE BLOG – Why WWIII Comes in 2027

September 24, 2026

Blog Categories
Promotions

Market Talk

Market Talk

Models

Models

Events

Events

Socrates

Socrates

Blog Archives

The Fed Cannot Bring Back the Pandemic Housing Market


Posted Oct 8, 2026 by Martin Armstrong |

An Introduction to Real Estate Sector Strategy - Discovery Tools للتدريب  والاستشارات وتنظيم المؤتمرات

QUESTION: My realtor says the Fed is keeping rates high until the November midterms to punish Trump. He insists inflation has subsided and expects another rate cut to bring mortgage rates down and buyers back. He claims I will have better luck listing the property after midterms. Is there any substance to this argument?

ANSWER: No. Your realtor is asking you to stake a financial decision on his political opinion. Where is his evidence that the Fed is setting rates to punish Trump? The Fed makes monetary policy independently of the White House. You can criticize its decisions without inventing motives. Someone advising you on the sale of your home should understand the financing market well enough to explain why buyers are struggling, instead of blaming everything on a personal vendetta.

Investors consider the future course of inflation, economic growth, interest rates, and the supply of competing investments. The Fed controls an overnight policy rate. A 30-year mortgage must attract money from investors who have other places to put it. They are concerned with what their return will buy and whether another investment offers better compensation. Your realtor cannot make that calculation disappear by circling the next Fed meeting on a calendar.

Treasury debt competes for that same capital. When the government borrows, investors must absorb the securities it issues, and the yield required depends on demand. Mortgage securities must remain competitive with those alternatives. The 10-year Treasury is an important benchmark, but mortgage rates also carry a spread reflecting repayment uncertainty, market volatility, and the costs of making and servicing loans. That spread can widen enough to offset a decline in Treasury yields. There is no rule requiring a lender to pass through a Fed cut point for point.

The borrower also holds an option that costs the investor money. When rates fall, homeowners refinance and repay mortgages that investors would prefer to keep. When rates rise, homeowners hold on to their cheap loans, extending the investor’s exposure to an unattractive yield. Investors demand compensation for that arrangement. Greater uncertainty about interest rates can increase the compensation they require.

Even cutting the federal funds target to zero would not guarantee a return to pandemic mortgage rates. Markets would ask why the Fed had taken such an extraordinary step. If it signaled a severe economic contraction, long-term yields might decline, but lending could tighten and buyers could fear for their jobs. If investors believed the Fed had abandoned inflation discipline, longer-term yields could rise. The Fed cannot order capital to accept a return investors consider inadequate.

People also keep confusing lower inflation with lower prices. The price increases accumulated since 2020 remain embedded in household budgets. Overall U.S. consumer prices are up about 29.9% from January 2020 through August 2026. That calculation uses the BLS index’s rise from 257.971 to 334.980. Slower inflation does not restore the purchasing power already lost, and it does not reverse the increase in the income required to support the same standard of living.

Housing carries an even larger accumulated increase. The national Case-Shiller index was roughly 59% above January 2020 by July 2026. Buyers are therefore confronting a much higher purchase price alongside more expensive financing. A quarter-point reduction in the overnight rate cannot repair that arithmetic. Sellers may remember what somebody paid during the frenzy, but the next buyer must qualify against today’s payment and today’s income.

My view is that exceptionally cheap money persisted far too long and distorted expectations. The 30-year mortgage average reached 2.65% in January 2021. That year, the Fed added $80 billion in Treasuries and $40 billion in agency mortgage-backed securities to its holdings each month. Direct purchases of mortgage securities supported financing conditions in a way that an ordinary policy-rate cut does not replicate. People took an extraordinary intervention and assumed it established the normal cost of borrowing forever.

That left us with two real estate economies. Existing owners with cheap fixed mortgages possess a financing advantage that a new buyer cannot obtain merely by purchasing their house. Those owners may have considerable equity and little incentive to move, because moving means surrendering the old loan. New buyers must finance elevated prices at current rates. Cash buyers operate under another set of constraints altogether. Talking about “the housing market” as though everyone faces the same circumstances conceals the problem. The low-rate mortgage has become an asset worth holding on to.

Weak employment makes the situation harder. A buyer concerned about losing income will not necessarily take on a large mortgage because rates decline modestly. Lower borrowing costs cannot substitute for a dependable paycheck, and falling rates during a downturn need not produce rising sales. When homes sit longer, sellers have to assess actual buyer demand and competing inventory. Sometimes the adjustment has to come through the asking price. Expecting cheaper credit to rescue every valuation is precisely how people avoid confronting what the market is telling them.

Buyers who need to purchase now must qualify at the financing terms available now, negotiate a price they can support, or choose a less expensive property. Sellers should not base their decisions on another 2% or 3% mortgage boom because, sorry, that was a once-in-a-lifetime event. Nobody can prove those rates will never appear again, but another emergency producing them would not necessarily reproduce the pandemic buying frenzy. Your realtor sounds like an idiot. You are paying the carrying costs while he waits for Washington to deliver the market he would prefer.

Plagues & Election Cycle?


Posted Hurry up – We need a new Pandemic for another Lockdown to Justify Mail-in Ballots Again

Posted originally on: Oct 7, 2026 by Martin Armstrong |

Plague Scientist 2

Hurry up – We need a new Pandemic for another Lockdown to Justify Mail-in Ballots Again