LIVE: AG Todd Blanche Holds News Conference.


Posted originally on: rumble by BREITBART News Network on Aug 27, 2026

They Will Do Anything to Avoid Returning to Cash


Posted  Originally on Aug 28, 2026 by Martin Armstrong |  

What is a cashless society and how does it work? | myPOS

Switzerland is developing a nationwide system that will allow consumers to make card payments even when internet and telecommunications networks are unavailable. The government, Swiss National Bank, commercial banks, payment providers, terminal manufacturers, and major retailers are working together to make approximately 16.5 million debit and credit cards capable of operating offline, with broad deployment planned by the end of 2027. They are constructing an entirely new emergency payment infrastructure to create “offline payments” that are still under government’s watchful eye.

Cash does not need authorization, a PIN, a working terminal, a battery, a generator, or a promise that the banking network will return. It settles the transaction immediately and leaves no unfinished claim waiting to be processed. Yet the Swiss Federal Office for National Economic Supply declared that while cash is an alternative, it is “always advisable” to be able to complete purchases without it.

Under the proposed system, the customer must use a physical card and enter a PIN. Authorization occurs locally between the chip and the terminal, which stores the transaction until communications are restored. The account is debited later after the terminal finally reconnects to the payment system. This means the payment is not truly settled offline. It is merely recorded offline and submitted to the banks later, ensuring that the transaction eventually returns to the same centralized financial network government claims was temporarily unavailable.

The terminal must still have electricity from the grid, a battery, or a generator. Therefore, if the emergency is prolonged, cash remains the only reliable option. The system will also be restricted initially to retailers selling government-defined essential goods. A person may be permitted to purchase food, medicine, and fuel but not necessarily repair equipment, obtain supplies from a small independent business, or pay another individual. Cash does not ask a bureaucrat whether the merchant or product belongs to an approved category.

A society dependent entirely upon banks, cards, telecommunications, and electricity is fragile regardless of whether the terminal can temporarily store transactions. Cash creates an entirely separate payment channel outside the electronic network. It works when banks fail, cards are blocked, systems are hacked, power disappears, or government declares an emergency.

The objective is to ensure that money never truly leaves the banking system. When people hold cash, banks cannot use those funds, governments cannot instantly observe transactions, payment providers cannot collect fees, and monetary authorities cannot impose negative rates or control how quickly money circulates. Cash gives the individual direct possession of money. A card provides access to a liability recorded on someone else’s computer, subject to contractual terms, technical limits, institutional solvency, and government regulation.

Sweden also expanded offline card payments in July 2026 to cover communications disruptions lasting as long as seven days, and Finland, Norway, and Estonia are developing similar arrangements. The same pattern is spreading across nations that allowed cash usage to decline and then discovered that their digital economies could stop functioning during a cyberattack, telecommunications failure, power interruption, or war. Rather than admit that abandoning cash was reckless, they are building another layer of technology to keep everyone inside the electronic cage.

The War Cycle makes this particularly disturbing because payment infrastructure will become an obvious target during any major conflict. Cyberattacks can cripple banks, communications networks, power grids, and payment processors without a single soldier crossing a border. Governments know this, which is why they are suddenly concerned about emergency payment resilience. Nevertheless, the solution remains controlled by the same banks, card networks, and state institutions whose failure would trigger the emergency. That is not independence from the system. It is a delayed connection to the system.

This also provides the bridge toward CBDCs. Once the public accepts that offline electronic payments are safer and more convenient than maintaining cash, central banks can claim that digital currency offers every benefit of banknotes without the physical inconvenience. The digital euro is already being designed with offline functionality, and the ECB promotes it as providing “cash-like” privacy. Cash-like is not cash.

Governments want the public to believe that the future of money is inevitable and that cash has become an obsolete nuisance. It is not obsolete to possess an asset that cannot be remotely frozen, rejected by a terminal, erased by a software error, or made inaccessible because a bank’s server failed. Cash remains dangerous only to those who want every unit of currency deposited, traceable, taxable, and ultimately controllable.

The Swiss plan may provide a useful emergency service, and nobody should object to having an additional payment option during a temporary outage. The issue is the relentless refusal to treat cash as the primary layer of financial resilience. They will redesign cards, reconfigure millions of terminals, coordinate banks and retailers, install backup power, and store transactions for later surveillance, but they will not simply encourage people and businesses to keep enough physical currency available for an emergency. They will do anything to keep your money inside the system because once you hold cash, you no longer need their permission to use it.

The Entire Financial System Is Chained to Government Debt


Posted  Originally on Aug 28, 2026 by Martin Armstrong |  

Debt Crisis

The Bank for International Settlements is warning that near-record public debt and the growing role of hedge funds and other nonbank financial institutions have created what it calls a “fiscal-financial stability nexus.” That is sanitized bureaucratic language for a system in which governments, banks, pension funds, insurers, hedge funds, and central banks are all chained to the same mountain of sovereign debt. If government bonds begin to fail, the losses will not remain confined to some account at the Treasury. They will spread through the institutions holding the public’s savings and eventually force central banks to choose between the currency and the financial system.

Government debt is treated as the foundation of modern finance. Banks use sovereign bonds as collateral, pension funds hold them to match future obligations, insurers depend on them for income, and hedge funds trade them using enormous leverage through repurchase markets. Regulators assign government debt privileged treatment because they have declared it “risk-free,” but no investment is free of risk. The label exists because government needs financial institutions to purchase its bonds, and admitting that sovereign debt can become unstable would expose the fraud supporting the entire system.

The BIS estimates that the probability of a financial-stress event comparable to the Global Financial Crisis occurring within three months is roughly ten times higher when public debt relative to GDP is elevated. The probability rises from approximately 0.3% under lower-debt conditions to 3.8% when government debt is high. The risk increases further when nonbank financial institutions hold a larger share of the market because many depend on leverage and short-term funding that can disappear the moment bond prices move against them.

This is how a routine selloff can become a systemic event. Government bonds decline, yields rise, and leveraged funds suffer losses. Lenders demand additional collateral, forcing those funds to sell more securities into a falling market. Liquidity disappears, borrowing costs surge, and the losses spread to banks and other institutions connected through funding markets. Government then complains that the market is “dysfunctional” because investors are no longer purchasing its debt at politically convenient prices.

The central bank is forced to intervene because allowing the bond market to clear naturally could bring down the financial system. It purchases government securities, supplies emergency liquidity, and claims that the operation is temporary and has nothing to do with financing the state. Yet every rescue teaches the market that excessive leverage will be protected and teaches politicians that reckless borrowing carries no immediate consequence. This creates the next crisis by encouraging the exact behavior that caused the first one.

The BIS openly admits that repeated central-bank interventions can weaken market discipline over government spending. This is the vicious circle they cannot escape. Governments borrow excessively, bond markets become unstable, central banks suppress the instability, and politicians interpret the rescue as permission to borrow even more. The debt increases until each attempt to restore honest interest rates threatens the banks, pensions, and funds that were encouraged to hold it.

The Federal Reserve and other central banks are therefore losing control of monetary policy. Raising rates to fight inflation reduces bond prices and inflicts losses on financial institutions while simultaneously increasing the government’s interest expense. Lowering rates or purchasing bonds protects the debt structure but risks weakening the currency and reigniting inflation. They can defend the purchasing power of money or defend the government bond market, but the size of the debt will eventually make it impossible to defend both.

Shorter debt maturities make this trap even worse. Governments have moved toward short-term borrowing to avoid paying higher long-term rates, but that means more debt must be refinanced sooner. Every rate increase passes through to the government’s interest bill more quickly. If investors suddenly question fiscal sustainability, the state must return to the market repeatedly while buyers demand increasing compensation for the risk. The rollover mechanism that once concealed insolvency then accelerates it.

The BIS expects debt pressure to continue beyond 2031 as aging populations increase pension and healthcare costs while governments demand more money for infrastructure, renewable energy, and defense. This is precisely why the War Cycle and Sovereign Debt Crisis are converging. Governments already cannot finance their domestic promises, yet they are expanding military budgets, subsidizing strategic industries, and preparing for prolonged geopolitical conflict. War does not eliminate old obligations. It piles new debt on top of them.

Pensioners and ordinary savers will ultimately be trapped in the middle. Their retirement funds hold government bonds because regulators call them safe, but those same bonds lose value when rates rise or inflation accelerates. If funds experience losses, government will use the crisis to justify additional regulation, mandatory asset allocations, restrictions on withdrawals, or public bailouts financed through still more debt. The citizen will be taxed to rescue an institution that lost money financing the government that imposed the tax.

This is also where digital currencies and capital controls enter the picture. When voluntary demand for government debt becomes insufficient, the state will search for methods to direct private savings into approved securities. A financial system built around identified digital wallets and programmable payment rails would make it far easier to restrict capital movement, limit withdrawals, and steer money toward government obligations. They will call it financial stability because admitting that the objective is financial repression would provoke revolt.

The Sovereign Debt Crisis will spread through the financial system because sovereign bonds have been embedded into everything. The state borrowed the money, regulators declared the debt safe, institutions bought it with the public’s savings, and central banks promised to rescue the market if anything went wrong. The entire structure depends upon confidence that government will always honor its obligations without destroying the value of the currency used to repay them. Once that confidence breaks, there will be nowhere inside the conventional financial system to hide.

Washington Wants to Turn Chinese Banks Into the Next Battlefield


Posted  Originally on Aug 28, 2026 by Martin Armstrong |  

US Sanctions

Lawmakers from both parties are pressing the Treasury to target Chinese banks over their business with Iran. Washington is taking a confrontation it has failed to resolve and looking for ways to extend it into the financial system of another major power. The assumption is that Beijing will eventually surrender its commercial interests rather than risk losing access to American finance. What happens if China decides that accepting Washington’s authority over its banks is more dangerous than resisting it? That is the question missing from the tough talk about making other countries pay.

Lawmakers are demanding action against Chinese banks that facilitate Iranian business. Supporters argue that cutting off financing would weaken Tehran’s ability to sustain its military activities. That argument deserves to be examined, but so does the mechanism. Sanctioning a major bank can affect far more than the transactions officials intend to stop. Depending on the restrictions imposed, unrelated importers, exporters, lenders, and investors could suddenly find payments delayed, credit withdrawn, or counterparties unwilling to deal with them. The politicians announce the punishment while businesses discover how widely the damage spreads.

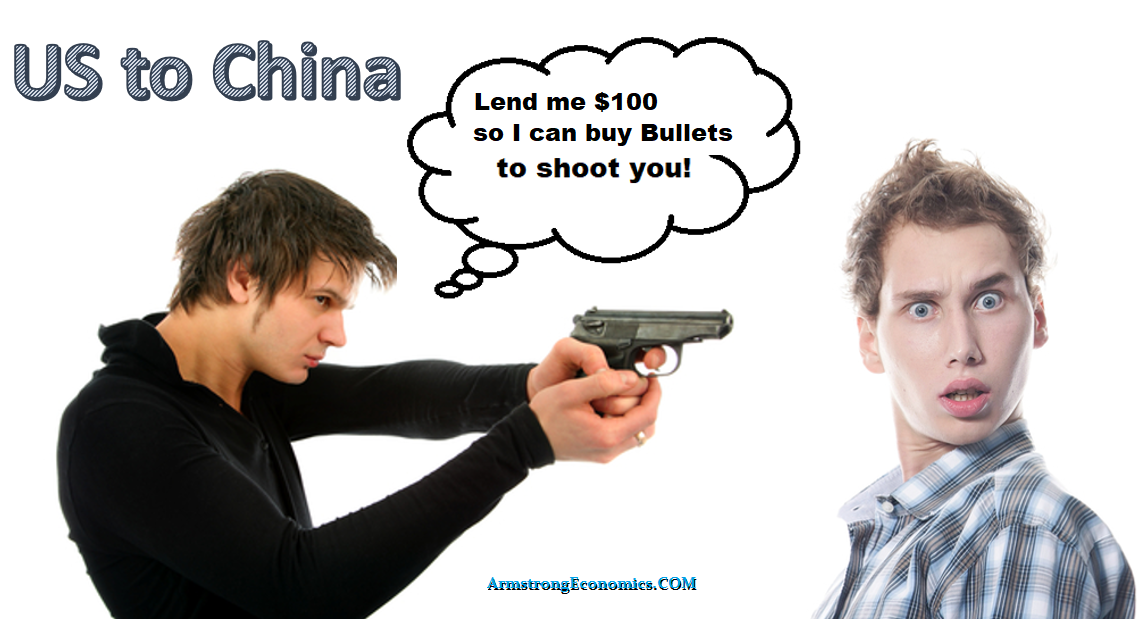
US debt to China Buy Bullets

Treasury has already laid the groundwork. In April, it warned financial institutions about transactions involving Chinese independent refineries purchasing Iranian oil and explicitly raised the possibility of secondary sanctions. These measures pressure foreign institutions to comply with American restrictions by threatening their access to American finance. Washington is effectively telling a Chinese bank that its business with Iran can jeopardize its business with the United States. That is considerable leverage, but exercising it against a major financial institution carries a different order of risk from sanctioning an obscure trading company.

The administration has so far stopped short of that broader confrontation. Reuters reported that the August 24 sanctions package targeted 60 individuals, entities, and vessels but did not include major Chinese financial institutions. There is still a consequential decision ahead: whether to escalate against institutions whose connections extend well beyond Iran.

Dennis Wilder, a former National Security Council director for China, shared a passage from the Politico report describing action against large Chinese banks as the “nuclear economic weapon.” That description ought to make people pause. A major bank is part of the machinery through which companies obtain financing, settle invoices, manage currencies, and pay suppliers. Threatening that machinery introduces uncertainty into transactions that have nothing whatsoever to do with Tehran. Even before restrictions take effect, banks may retreat from permissible business because the cost of accidentally violating a sanction appears greater than the profit from serving the customer.

China warned of retaliation if its companies were affected by expanded sanctions, while major Chinese financial institutions remained outside the latest measures. China has economic pressure points of its own, including critical minerals and access to its domestic market. Washington cannot assume that financial coercion will produce a response confined to banking. A dispute over Iranian oil could become another confrontation over industrial supplies, export restrictions, and the ability of American companies to conduct business.

The connection to sovereign debt is equally uncomfortable. Governments want dependable access to international capital while making international finance more political and less dependable. If restrictions disrupt supplies or raise transaction costs, businesses face higher expenses and governments face pressure to subsidize the damage. If confrontation then produces additional military commitments, borrowing rises again. None of this guarantees a debt crisis, but it adds costs and uncertainty to fiscal systems already burdened by competing promises.

Economic warfare has given foreign governments another reason to question the safety of keeping their national wealth in Western financial assets. When selected Russian banks were disconnected from SWIFT and Russia’s central-bank reserves were frozen in 2022, the message extended far beyond Moscow: access to your money can depend on your relationship with the governments controlling the system. That has strengthened the incentive to diversify reserves, accumulate gold, and reduce exposure to assets that could become inaccessible during a political confrontation.

China understands that vulnerability and has been building greater industrial self-reliance while seeking ways to reduce its dependence on dollar finance. Beijing is working toward becoming self-sufficient and independent of the West for it knows the relationship is taken lightly. Washington wants other nations to trust its financial system with their savings while threatening to exclude them whenever their foreign policy conflicts with American demands. Every additional threat gives Beijing another argument for reducing the dependence that makes those threats effective.

Categories:War

LAWFARE: Federal Judge Again Blocks USPS Mail Ballot Requirement


Posted originally on the CTH on August 27, 2026 | sundance 

The same federal judge who had her injunction overturned by the Supreme Court has again blocked the United States Postal Service requirement for mail-in ballots.  The Lawfare communists refiled their lawsuit today, the judge ruled within hours. [Ruling Here]

The issue is at the core of leftist manipulation of elections as the blue states refuse to comply with DHS and Social Security cross-checks for voter eligibility prior to sending out mail-in ballots.  The blue states do not want their voter rolls cross-checked to verify citizenship status and voter eligibility. We can only guess the number of illegal aliens on the voter rolls.

(VIA AP) – A federal judge on Thursday halted — at least for now — attempts to implement President Donald Trump’s executive order limiting mail voting.

The move stalled the directive for a second time only about a week before the first mail ballots are due to be sent out for the rapidly approaching midterm elections. U.S. District Court Judge Indira Talwani blocked the government from implementing the order for two weeks.

The case could soon be appealed back to the Supreme Court, days after the justices handed down a procedural decision that allowed the administration to move ahead.

The ruling Thursday came after Democrats and voting rights groups refiled their lawsuits to comply with the recent Supreme Court decision. The high court’s conservative majority did not rule on the legality of Trump’s executive order, instead saying Talwani had acted too soon.

Now the administration has issued a formal rule governing whether the U.S. Postal Service will deliver states’ mail ballots, effectively restarting the legal fight.

The whipsawing legal battle has major ramifications for the midterms. Nearly one-third of Americans vote by mail and election officials contend there isn’t enough time to revise their systems to comply with the new Postal Service directives.

The Postal Service says it won’t deliver mail ballots unless states provide a list of voters who should receive them and format the envelopes in a certain way. (read more)

Russian Airforce Lt Col Killed in St Petersburg Car Bomb Attack


Posted originally on the CTH onAugust 27, 2026 | sundance |

Deep breath.  Yesterday, CTH noted to pay close attention to the Finland-Russia border region and the areas in/around St Petersburg.  There has been a visible coordination between Finland and Ukraine in the attacks against Russia.  I would not be surprised to hear this terrorist crossed that border region.

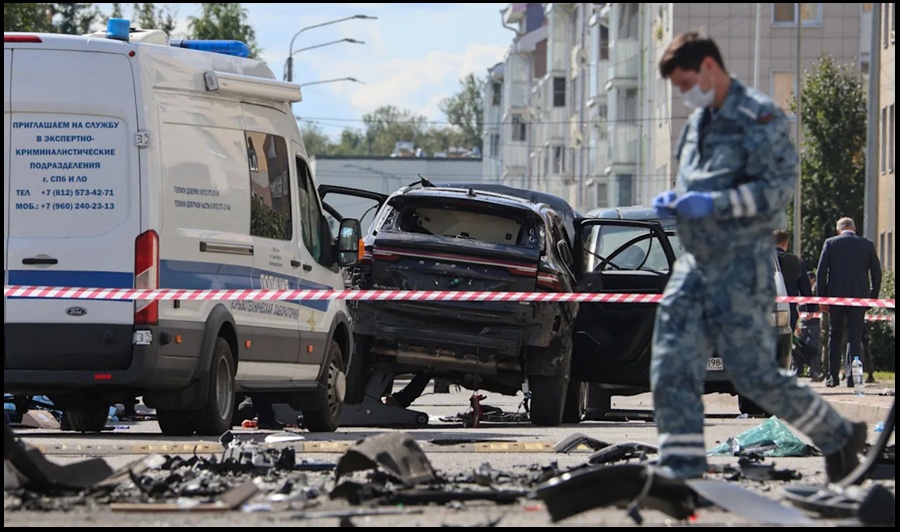
A Lt Col in the Russian Airforce was killed immediately when a car bomb exploded that also severely injured his wife.  As you are reading this there are also reports of thousands of Ukraine civilians fleeing Kiev ahead of Russia’s predicted retaliation.  The serviceman was killed in an area heavily occupied by military personnel and their families.

This is the fourth car bomb in the past few months and the seventh Ukraine car/parcel bombing in the last few years. Zelenskyy is in Moldova today organizing new attacks against Russia.

RUSSIA – A senior Russian officer has been killed by a car bomb in St Petersburg, Russian media reported.

Footage posted on Telegram showed emergency workers and police flooding a street littered with the debris of an exploded vehicle and cordoning it off from the public.

An explosion sounded at around 10am near a Magnit supermarket in the suburban neighbourhood of Shushary, killing the lieutenant colonel and badly injuring his wife, according to Fontanka, a St Petersburg news publication, which cited eyewitnesses.

The outlet claimed that both had lost their legs in the blast, which took place as they began driving away from their home. (read more)

Canadian State Media Tells Journalists: “Do not refer to the Sept. 11 attacks as terrorist attacks”


Posted originally on the CTH on August 27, 2026 | sundance |

The Canadian state media outlet, the Canadian Broadcasting Corporation (CBC), responds to the tensions of the Canada-USA relationship by telling all state funded journalists: “Do not refer to the Sept. 11 attacks as terrorist attacks.”

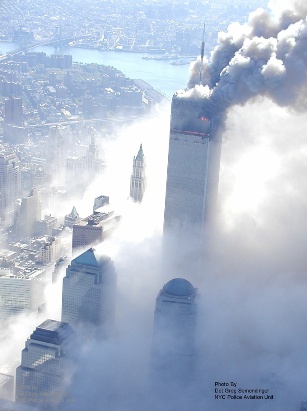
According to the internal communication: “The memo instead described the 9-11 events as hijackings that led to passenger jet crashes in Washington, D.C., Pennsylvania and Manhattan. It also said the World Trade Center was destroyed. {citation}

CANADA – The Canadian Broadcasting Corporation on Thursday defended an internal memo directing its reporters and editors to refrain from describing the Sept. 11, 2001, attacks as “terrorist attacks,” telling Fox News Digital the guidance reflected its longstanding practice of attributing terms it considers politically and emotionally loaded.

“It is the practice of the CBC to exercise extreme caution before using the words ‘terrorist’ and ‘terrorism,’” CBC Public Affairs Director Kerry Kelly said in a statement to Fox News Digital. “The memo was a reminder of the longstanding practice that favours the use of these terms with attribution in our reporting.”

The memo was authored by Basem Boshra, CBC News’ senior director of journalistic standards and public trust, and surfaced ahead of the attacks’ 25th anniversary. The directive was first reported by Toronto Sun columnist Warren Kinsella, who said it was addressed to CBC News staff. “Do not refer to the Sept. 11 attacks as terrorist attacks,” the memo said.

The memo instead described the events as hijackings that led to passenger jet crashes in Washington, D.C., Pennsylvania and Manhattan. It also said the World Trade Center was destroyed. (read more)

There is nothing more typically representative of a Canadian than taking the petty approach on any issue.

TRUE STORY:  A hotel manager in Europe once asked me, “are you Canadian?” I replied, no, I’m American. We then struck up a conversation. He was a polite fellow.  After some small talk he told me he knew I was American, but the general rule of thumb is to always ask if a person is Canadian because if you ask an American if they are Canadian, they will simply reply as I did.  However, if you ask a Canadian if they are American the guest will go bananas.  So, they just ask everyone if they are Canadian.

The Canadians will tell you that everyone around the world loves them.  Maybe that’s true, but everyone I’ve ever talked to said they don’t like Canadians because they’re self-centered and complain about stuff.  Terrible tippers too.

President Trump and USGS Officially Change Name of Lake Ontario to Lake America


Posted originally on the CTH on August 27, 2026 | sundance 

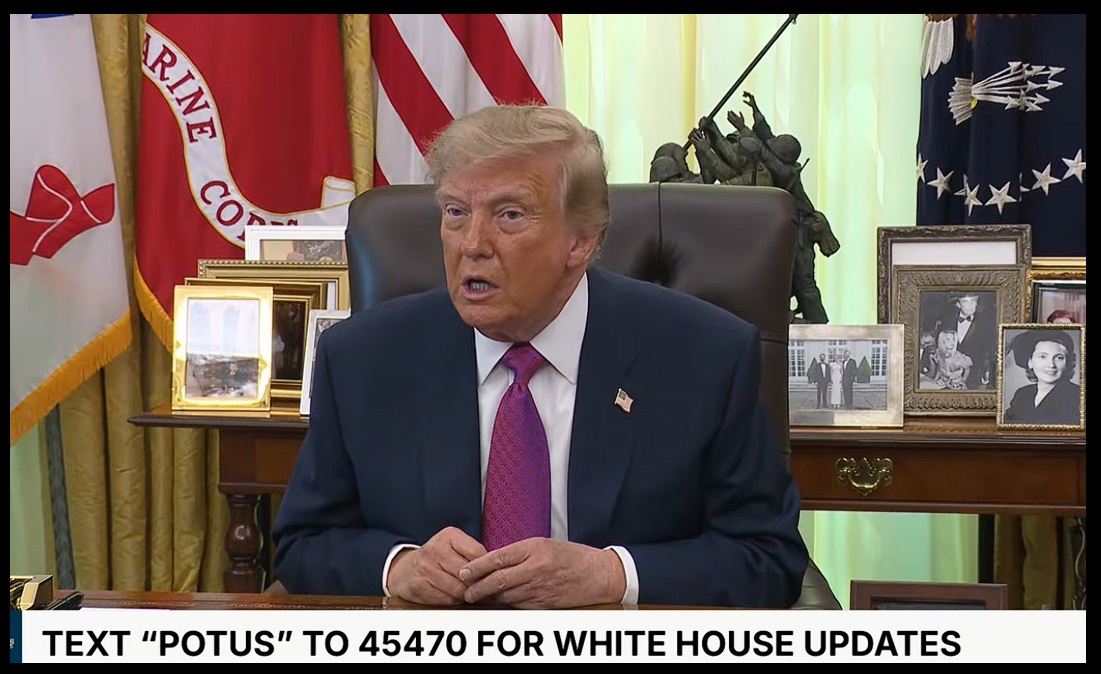
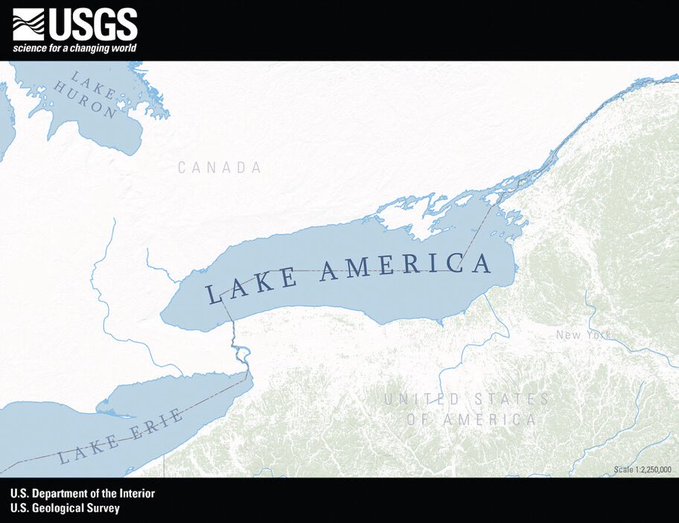
President Trump holds a press availability in the oval office for a signing ceremony changing the name of Lake Ontario to Lake America.  Additionally, President Trump answered questions about the U.S relationship with the Canadian government.

Listen to the presser and you fully understand President Trump’s position on U.S-Canadian trade and the trilateral NAFTA/USMCA agreement.  Trump noted he is now finishing the North American trade and economic policy that he began in his first term.  There is not a single moment of hesitation in his responses.  WATCH:

President Trump also fielded questions about the Ukraine war and the status of relationship with Russian Federation President Vladimir Putin.  President Trump succinctly said, “he’s not going to attack NATO.”

TO: Office of the Secretary, Department of the Interior
FROM: Director, U.S. Geological Survey
RE: Lake America rename

Sir,

As of 4:30 pm today the U.S. Geological Survey has officially designated the former Lake Ontario to be renamed as Lake America in all official USGS electronic documents.

The change will begin occurring in printed documents over the next several days.

This change has also been made official in the Geographic Names Information System.

Should you have any further questions please contact me for clarification.

Thank you
Ned

Dr. Ned Mamula
Director, U.S. Geological Survey
United States Department of the Interior

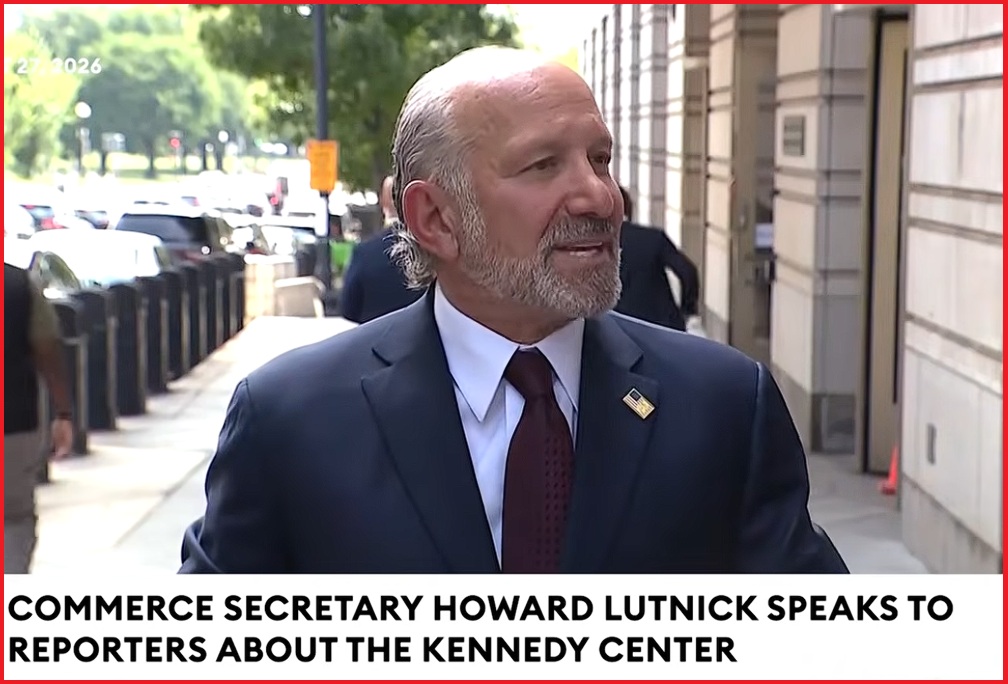
Commerce Secretary Howard Lutnick Outlines How Canada Manufactured Political Outrage for Domestic Consumption


Posted originally on the CTH on August 27, 2026 | sundance |

As we have all learned in the past week, Canadian Prime Minister Mark Carney manufactured an oppositional narrative to the U.S-Canada trade deal in order to say no. Today, Commerce Secretary Howard Lutnick gave specifics about the last-minute Canadian demands that blew up the trade agreement.

Secretary Lutnick has a long-standing relationship with Prime Minister Mark Carney and during the negotiations he talked at length to both Canada’s primary trade negotiator, Dominick LeBlanc as well as Prime Minister Carney. Lutnick notes the issues Carney claimed were too much for Canada to agree to were entirely manufactured at the last minute in order to say no.

At no point was the French language ever mentioned in the trade discussions. At no time was the trade sector that involves U.S. tariffs against heavy-duty trucks and semi tractor trailers ever mentioned, until Friday at 4:00pm when Carney brought up that issue. The agreement was outlined and agreed by all parties prior to Friday; Howard Lutnick speaking twice to Prime Minister Carney personally. There was no issue until the last minute when Canada chose to make issues.

As Lutnick notes, this is all political on the Canadian side. Prime Minister Carney needed domestic political leverage to manipulate his constituents. This is worth watching:

.

The full presser is below that covers other topics including the Kennedy Center.  In the longer video the Canada issue comes up at 18:38.

.

LIVE: Sec. of War Pete Hegseth Awards Marines for Service in Afghanistan…


Posted originally on: rumble by BREITBART News Network on Aug 25, 2026