BANNON: If We Can’t Expedite The SAVE America Act, Then The President Has An Obligation And A Duty To Declare A National Security Emergency And Protect The Vote!


Posted originally on rumble on Bannons War Room on: July 9, 2026

BANNON: Get That Big-Mouth Mark Levin In A Front Tank. He Talks A Big Game; Why Isn’t He Over There Fighting?


Posted originally on rumble on Bannons War Room on: July 9, 2026

Episode 5502: Day 3 Of The Charlie Kirk Assassination Trial


Posted originally on rumble on Bannons War Room on: July 9, 2026

Bannon: We’ve been told that not simply the Iranian Air force and the Navy, but all missiles are gone, and it’s obviously not the case. They still have the ability to deliver a punch.


Posted originally on rumble on Bannons War Room on: July 9, 2026

Wendy Patrick: Not Every Forensic Detail Yet — The “Strongest” Autopsy and Ballistics Evidence Will Be Saved for Trial


Posted originally on rumble on Bannons War Room on: July 9, 2026

Episode 5500: Making Birth Tourism A State Felony


Posted originally on rumble on Bannons War Room on: July 9, 2026

LIVE: Preliminary Hearing for Tyler Robinson Continues…


Posted originally on Network on: July Rumble on Bright Bart News on July 9, 2026

LIVE: Preliminary Hearing in Tyler Robinson Murder Trial…


Posted originally on Network on: July Rumble on Bright Bart News on July 9, 2026

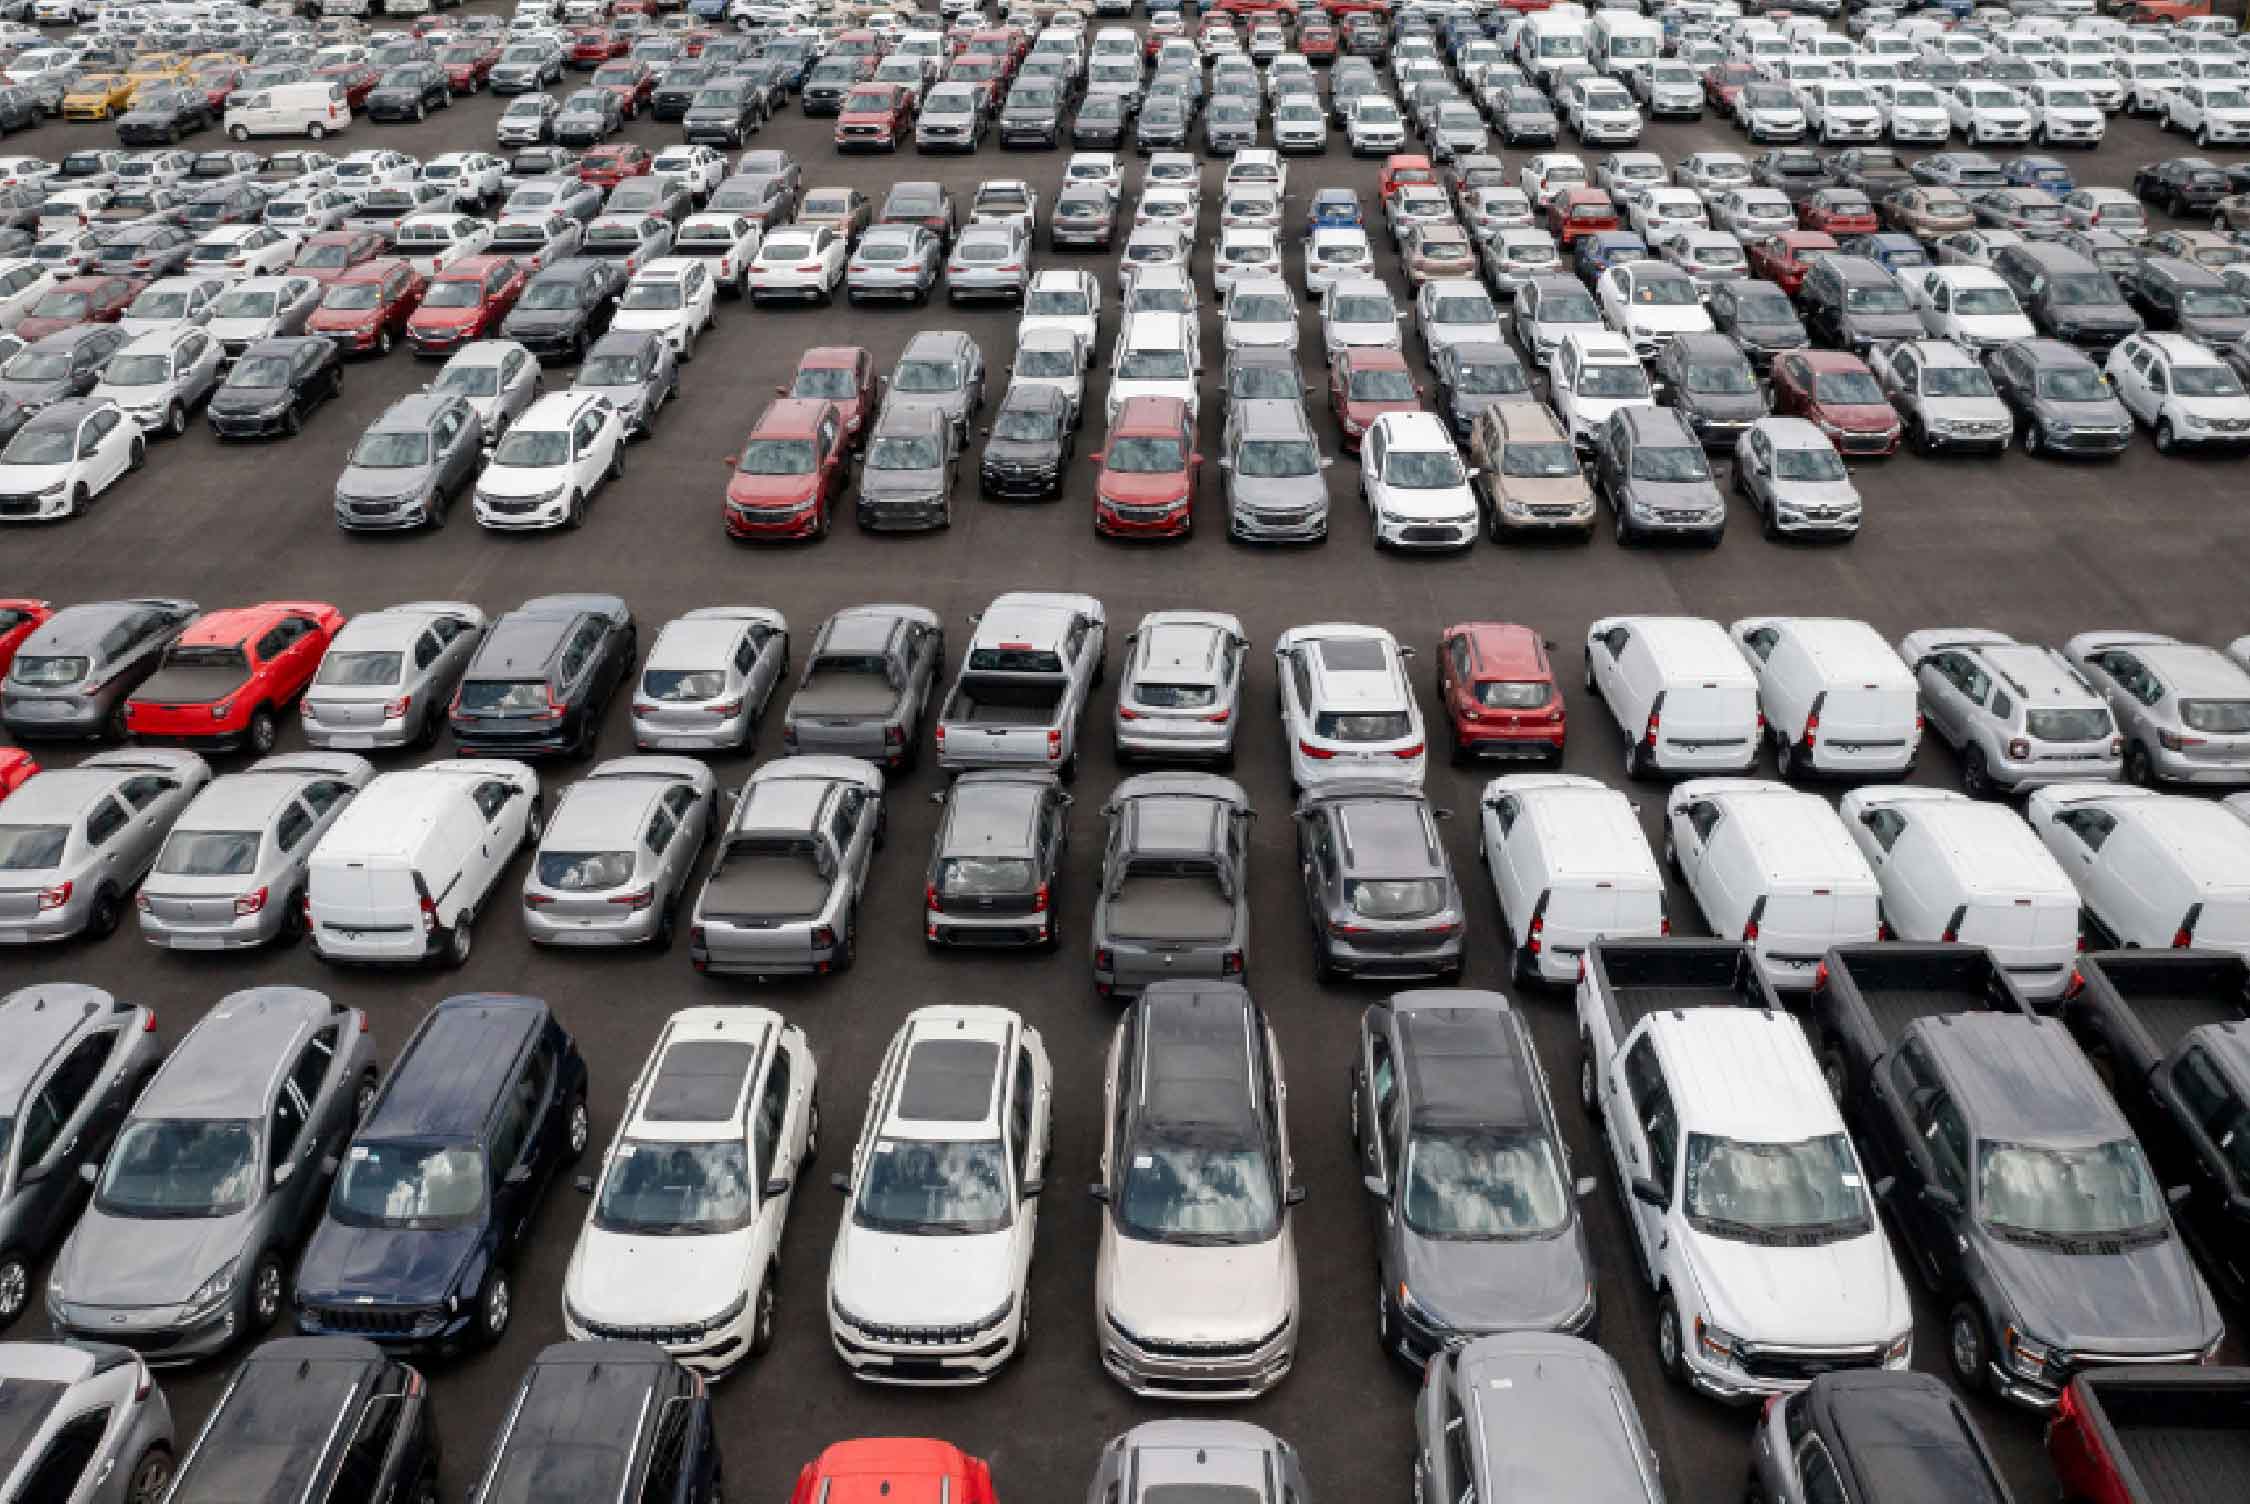
The American Dream Now Comes with an $800 Monthly Car Payment


Posted originally on Jul 10, 2026 by Martin Armstrong |  

Joliet Used Cars | Low Priced High Quality Pre Owned

FOX Business reported that the average monthly payment for a new vehicle reached a record $770 during the first quarter of 2026, according to LendingTree’s analysis of Experian data. Lease payments climbed to $619 per month, while used vehicle payments reached $531. The average amount financed for a new vehicle rose to $43,925, and outstanding auto loan debt surged to a record $1.685 trillion, exceeding the nation’s total student loan debt for the first time. This is not merely an automobile story. It is another warning that the purchasing power of the average American continues to deteriorate.

The average family is financing nearly $44,000 just to buy a depreciating asset because wages have failed to keep pace with the real cost of living. Government tells us inflation is under control, yet Americans are borrowing more money than ever simply to drive to work. If inflation were truly only 2%, car payments would not have doubled over the past generation while household budgets continue to buckle under the weight of necessities.

The debt statistics are becoming alarming. Auto loan balances have risen from $1.071 trillion in 2016 to $1.685 trillion today, an increase of more than 57% in just ten years. Auto debt now represents roughly 9% of all consumer debt, narrowly surpassing student loans. Americans originated another $182.1 billion in auto loans during the first quarter alone. We are borrowing at record levels to finance assets that lose value the moment they leave the dealership.

Borrowers with credit scores between 601 and 660 actually carried the highest average monthly payment at $811, while even subprime borrowers averaged $792. The system is trapping the middle class in perpetual debt. The better your credit, the lower your payment. Those already struggling financially are paying the greatest monthly burden, making it even harder to escape.

Edmunds found that the average financed amount for new vehicles reached another record of nearly $44,000, while average monthly payments climbed to approximately $773. One out of every five financed new vehicles now carries a monthly payment of at least $1,000. Buyers are responding the only way they can. Down payments are shrinking while loan terms continue stretching to seven and even eight years. Nearly one-quarter of new-car buyers are now taking loans lasting 84 months or longer. It is financing transportation like a mortgage.

Negative equity is becoming another hidden crisis. Edmunds reported that nearly 31% of trade-ins involved owners who owed more than their vehicles were worth, with the average underwater balance exceeding $7,100. Consumers are rolling debt from one vehicle into the next. They are not buying newer cars because they are wealthier. They are borrowing more because they have no alternative.

This is precisely what happens during the late stages of a debt cycle. Governments celebrate rising consumer spending while ignoring that it is financed with ever-larger amounts of borrowed money. The economy appears healthy because credit continues expanding, not because the average citizen has become more prosperous. Eventually there comes a point where consumers simply cannot borrow any more. That is when demand collapses, defaults accelerate, and politicians inevitably look for someone else to blame.

Categories:Inflation

Housing Costs Soared Throughout EU in Q1


Posted originally on Jul 10, 2026 by Martin Armstrong |  

https://www.instagram.com/p/DaSOEI7gaAB/embed/captioned/?cr=1&v=14&wp=500&rd=https%3A%2F%2Fwww.armstrongeconomics.com&rp=%2Freal-estate%2Fhousing-costs-soared-throughout-eu-in-q1%2F#%7B%22ci%22%3A0%2C%22os%22%3A918.7000000476837%7D

Europe’s housing market is not recovering, it is becoming unlivable. Eurostat reported that in Q1 2026, EU house prices rose 5.1% from Q1 2025, while rents increased 3.0%. Compared with Q4 2025, house prices rose another 1.2% and rents increased 0.7%. Between the 2025 average and Q1 2026, house prices climbed 2.9% and rents 1.8%. Wages do not keep pace with this, and young families are being priced out of the future.

A house is no longer a home, it has become a political and financial instrument. Europe buried its people under taxes, regulation, Net Zero costs, energy insanity, and mass migration pressure on housing supply, then acts surprised when people cannot afford to live. The state creates the crisis, then demands more power to solve it.

The worst house-price increases between 2025 and Q1 2026 were in Portugal at 10.3%, Bulgaria at 9.4%, Slovakia at 9.1%, Croatia at 8.4%, Spain at 7.5%, and Lithuania at 7.4%. France fell 0.5% and Finland fell 1.8%, but that does not mean affordability has returned. It means confidence is collapsing in places where the economy is already under strain.

Rents increased in almost every EU country. Croatia was the disaster, rents exploded 21.9% in just that comparison period. Bulgaria rose 6.4%, Greece 5.0%, Romania 4.5%, Czechia 4.1%, Slovakia 3.5%, and Portugal 3.3%. Slovenia was the only country where rents fell, down 0.9%, while Finland was basically flat.

This is the consequence of centralized planning. Brussels wants open borders, climate mandates, expensive energy, endless regulation, and then wonders why the average person cannot rent an apartment or buy a home. The private citizen is being squeezed from every side while governments protect bondholders, banks, and their own failed social experiments.

The sovereign debt crisis and housing crisis are connected. Governments need rising asset values to keep the illusion of solvency alive. They tax property, they borrow against inflated economies, and they pretend rising home prices mean prosperity. But when housing becomes unaffordable, birth rates collapse, civil unrest rises, and capital begins to flee. That is where Europe is heading. This is not a housing boom, it is another warning sign of a system that is breaking apart.