Tucker Carlson Discusses FBI Politicization and Special Agent Peter Strzok…


Deputy Head of Counterintelligence – FBI Agent Peter Strzok is either the hardest working politically-biased FBI investigator in the history of the agency, or he’s being set-up as a scapegoat.

Consider:  •Peter Strzok was the lead FBI agent in charge of the 2015/2016 Hillary Clinton email investigation. •Agent Strzok was one of a small group who actually interviewed Hillary Clinton. •Agent Strzok was also the person who interviewed Huma Abedin and Cheryl Mills, granting them immunity. •Agent Strzok created the wording for the Comey/Clinton exoneration

•Strzok was the counterintelligence investigator for the 2016 ‘vast Russian conspiracy’, narrative. •Agent Strzok was also the FBI contact person to receive the Russian Dossier and interview the author Christopher Steele.

•Agent Peter Strzok was then hired by Robert Mueller to lead the FBI investigative efforts into  the “Russian Election Collusion/Conspiracy.” •Agent Strzok was the person who interviewed National Security Advisor Michael Flynn.

•Agent Strzok was then removed from the Mueller Team after the anti-Trump/pro-Clinton content of his internal communications were discovered by the ongoing Inspector General investigation.

The structure of this narrative surrounding Peter Strzok is discussed by Tucker Carlson:

.

Additional Background:

♦Here’s CTH Twitter Thread on “WHY FLYNN LIED” – CLICK HERE

♦Here’s CTH Twitter Thread on “IG STATEMENT IMPORTANCE” – SEE HERE

♦Here’s CTH Twitter Thread on “DEEP STATE SCAPEGOAT” – SEE HERE

Supreme Court Upholds Trump’s Travel Ban


NYT Protest Immigrants

I have warned that all the protests against Trump’s Travel Ban were just politics. It was by no means discriminatory against Muslims, it was targeting the countries where terrorists come from. As I have said before, we employ people of every race and religion. We have no problem with our Muslim staff flying in from Europe for meetings. It was never targeting a religion, but a culture specific to nations that support terrorism. So the Supreme Court ruling is the correct ruling when the duty of the President is to protect the state and close borders to specific groups for national security. The Travel Ban has been just an excuse to attack Trump on every possible thing he does.  That is expected to continue.

Denmark Central Warns Next Financial Crisis is Coming


The Danish Central Bank has come out to warn that there is another financial crisis ahead. The central bank identified several indicators that point to growing risks from its analysis perspective. It is recommending that the banks in Denmark begin to raise their capital risk buffer.

The primary concern centers on household credit where banks have lent out money to gain interest in the midst of negative interest rates. The drive to create income has led the banks to lend to people with poor credit ratings. They also fear that the banks have lent too much to companies that suffer from the business cycle.

This is the consequence of negative interest rates. The banks lent out money at higher rates to those who have poor credit. As I have warned, every solution sets up the next crisis.

Bitcoin to be Declared a Financial Institution — Beware!


The risk with Bitcoin is that the government could simply change the definition of money. That is what they did to me back in 1980 because I was one of the three main market-makers in gold (perhaps the biggest). It was all a hunt for taxes, not concerning me but my clients. I have explained before why I retired from making markets in gold — the IRS declared me to be a BANK!  When gold was legalized in 1975 and began trading on the COMEX in New York, the New Jersey Senate asked me to write the law on gold to make sure it would not be taxable to buy and sell gold bullion. I worked with Senator Foran and developed the language that “gold was not taxable unless converted to use.”

I was making the market to buy gold scrap from all the stores you see with “WE BUY GOLD” signs. They buy the jewelry and it has to be refined. To do that, you needed a minimum lot of 100 ounces, which was the contract size on COMEX. When gold was $800, that meant one 100 ounce bar was valued at $80,000. The refining period was 6 weeks. Therefore, all of these small operations could not afford the float. If they bought 100 ounces per week, then they would need $560,000 in working capital. That would not work for most of these small shops buying gold.

I made the market. The shops could ship whatever they bought that day and I would buy it at the daily price. I gathered all the gold sold by countless stores. The gold was shipped by armored cars to Englehard for refining (PhiBro or Philipps Brothers who eventually bought Saloman Brothers). I was doing tens of millions per week back then and refined a mountain of gold.

First, the NJ tax authorities walked in and declared me to be a merchant. I said gold was not taxable unless converted to a usable product. They said their “interpretation” was that the “use” was investment.  I refused to pay and opted for a trial. Of course, you do not get a jury, just a judge who rules always for the government. I was not allowed to testify at my own trial for they said whatever the Senate had asked me to write, I may have misinterpreted their intention. Senator Foran was so angry that he demanded to testify at my trial. The government objected and he was allowed to testify ONLY as a private individual citizen. I moved to subpoena the full Senate. The judge denied me, and I lost.

Simultaneously, the Feds walked in and declared me to be a BANK. They then declared that I had to file forms to report when my clients bought or sold more than $10,000. Their interpretation was that gold was NEVER formally declared not to be money in 1971, so I was a BANK. They threatened me saying that the fine was $50,000 up to the full amount of every transaction I failed to report. They said they knew I perhaps did not “realize” I was a BANK and would forego the fines if I would allow them access to audit all my clients. I had no choice. They set up shop in my office. I walked by, noticing that they were pulling out names of those whose transaction were even $5,000, and I asked what was going on. The agent turned to me and said very aggressively, “You have a problem, keep your mouth shut!” The next day in rolled the vans and they took all my business records and began an audit over 3,000 of my clients for the next three years.

That is why I retired. I neither wanted to collect sales taxes on bullion nor be a BANK and report on my clients. Since I was the biggest, they were starting with me. People doing business outside of New Jersey would not have the sales tax problem and the IRS was interested in me because of my size. They would not do the same for small shops. So it was time to get out of the business. Clients wanted the research to continue, so that was spun-off as a new company in 1981.

Now comes Bitcoin. The Judiciary Committee of the United States Senate is currently working on Bill S.1241 that aims to criminalize deliberate concealment of property or the control of a financial account. The bill was submitted in June, and the law would change the definition of “financial account” and “financial institution,” and thus also cover digital currencies and digital exchanges. Who is pushing it? None other than California’s Senator Dianne Feinstein, who maintains that the bill is needed to update existing money laundering laws because of terrorists.

This means that the miners of Bitcoin will become a “bank,” as I was declared. The operators of the trading platform Coinbase were forced by court ruling to notify the IRS of the identity of over 14,000 investors who were trading $20,000 in Bitcoin. Users were affected if their trading volume had exceeded $20,000 at the beginning of 2013 by the end of 2015. So this is NOT a single transaction, but accumulative. The IRS will now “presume” tax evasion. This is what I warned would happen. Been there done that! They can shut down Bitcoin in the blink of an eye by simply defining anyone who is a miner to be a financial institution.

The bill will change the definition of “financial institution” in Section 53412 (a) of Title 31 , United States Code. The text will read:

“An exhibitor, a redeemer or a cashier of prepaid access devices, digital currency or a digital exchanger or a digital currency.”

The regulation will remove the anonymity of Bitcoin and other cryptocurrencies defeating this idea that there is an alternative-financial-universe separate from government.


Good Grief – Fired FBI Investigator Was The Person Who Interviewed Flynn…


OK, before going further, we need to step back and take a look at how deeply enmeshed Deputy Head of Counterintelligence FBI Agent Peter Strzok was to this entire FBI investigative enterprise.

•Peter Strzok was the lead FBI agent in charge of the Hillary Clinton email investigation. •Agent Peter Strzok was one of a small group who interviewed Hillary Clinton. •Agent Strzok was also the FBI contact person to receive the Russian Dossier and interview the author Christopher Steele.  [Remember, Hillary Clinton’s team paid Christopher Steele (via Fusion GPS) to create the dossier.] •Agent Strzok was the primary counterintelligence investigator for the ‘vast Russian conspiracy’, narrative.  •Agent Strzok was then hired by Robert Mueller to lead the FBI investigative efforts into  the “Russian Election Collusion/Conspiracy.”  •Agent Strzok was removed from the Mueller Team after the anti-Trump/pro-Clinton content of his internal communications were discovered by the current Inspector General investigation….

…and today we discover that Deputy Head of Counterintelligence, FBI Agent Peter Strzok was the person who interviewed National Security Advisor General Michael Flynn on January 24th, 2017.  An interview, that blindsided Flynn because there was no advanced notification…. And an interview that was the basis for the recent Robert Mueller charging of Flynn.

Good grief, it’s no wonder why the FBI desperately tried to control a pending IG release by advance-scripting a narrative, via leaks to the New York Times and Washington Post.

If FBI Agent Strzok can be shown to have conflicting political and institutional bias, then every aspect of the investigation he was involved in comes into question… and Agent Strzok is at the EPICENTER of every angle, within every aspect, of EVERY investigation.

SARA CARTER – A supervisory special agent who is now under scrutiny after being removed from Robert Mueller’s Special Counsel’s Office for alleged bias against President Trump also oversaw the bureau’s interviews of embattled former National Security advisor Michael Flynn, this reporter has learned.


FBI agent Peter Strzok was one of two FBI agents who interviewed Flynn, which took place on Jan. 24, at the White House, said several sources. The other FBI special agent, who interviewed Flynn, is described by sources as a field supervisor in the “Russian Squad, at the FBI’s Washington Field Office,” according to a former intelligence official, with knowledge of the interview.

[…]  The former U.S. intelligence official told this reporter, “with the recent revelation that Strzok was removed from the Special Counsel investigation for making anti-Trump text messages it seems likely that the accuracy and veracity of the 302 of Flynn’s interview as a whole should be reviewed and called into question.”

“The most logical thing to happen would be to call the other FBI Special Agent present during Flynn’s interview before the Grand Jury to recount his version,” the former intelligence official added.

[…]  According to another source, with direct knowledge of the Jan. 24 interview, McCabe had contacted Flynn by phone directly at the White House. White House officials had spent the “earlier part of the week with the FBI overseeing training and security measures associated with their new roles so it was no surprise to Flynn that McCabe had called,” the source said.

McCabe told Flynn “some agents were heading over (to the White House) but Flynn thought it was part of the routine work the FBI had been doing and said they would be cleared at the gate,” the source said.

“It wasn’t until after they were already in (Flynn’s) office that he realized he was being formally interviewed. He didn’t have an attorney with him,” they added.  Flynn’s attorney Robert Kelner did not respond for comment.

… [Justice Department Spokesperson] Isgur Flores said in a written statement to this reporter that the Justice Department provided the House Intelligence committee and leadership with “several hundred pages of classified documents and multiple briefings—including, for example, clear answers as to whether any FBI payments were made to a source in question related to the dossier—and has more recently cleared key witnesses they have requested to testify, including Mr. McCabe, Mr. Strzok, and the alleged handler in question.”  (read more)

Many people have asked the question why would Michael Flynn have lied about talking to Russian Ambassador Sergey Kislyak in the first place?

It’s a great question.

The Occam’s Razor answer is the toxic political environment that existed in January 2017, where the administration was being hammered by a tsunami of media narratives and political opposition claiming that any scintilla of contact with anything Russian meant that Putin and Trump were “colluding” BFFs,…. and Flynn didn’t want to fuel that nonsense.

That’s really the only reason to mislead about Russian contacts.

And/or once Vice-President Mike Pence made the statement that Flynn had no contact with anyone from Russia etc. any contradictory statement from Flynn would make Pence appear compromised; so Flynn had to stick to it without clarification.

Reminder:

•Sunday January 15th – VP-elect Mike Pence appears on Face The Nation. [Transcript Here]

JOHN DICKERSON: But there’s a distinction between that feeling about the press and legitimate inquiry, as you say, that the Senate Intelligence Committee is doing. Just to button up one question, did any advisor or anybody in the Trump campaign have any contact with the Russians who were trying to meddle in the election?

MIKE PENCE: Of course not. And I think to suggest that is to give credence to some of these bizarre rumors that have swirled around the candidacy. (link)

[*NOTE* Notice the narrative questioning at the time (early Jan) was framed that ‘any contact’ with Russians was evidence of meddling/election-collusion with Russians.]

•Friday January 20th – Inauguration

•Tuesday January 24th – Lt. Gen. Mike Flynn was interviewed at the WH by the FBI.

♦[Either Flynn contradicts Pence, or he tells a lie, those were his options.]

•Wednesday January 25th –  The Department of Justice received a detailed readout from the FBI agents who had interviewed Flynn. Yates said she felt “it was important to get this information to the White House as quickly as possible.”

•Thursday January 26th – (morning) Yates called McGahn first thing that morning to tell him she had “a very sensitive matter” that had to be discussed face to face. McGahn agreed to meet with Yates later that afternoon.

•Thursday January 26th – (afternoon)  Sally Yates traveled to the White House along with a senior member of the DOJ’s National Security Division, Bill Priestap, who was overseeing the matter.  This was Yates’ first meeting with McGahn in his office, which also acts as a sensitive compartmented information facility (SCIF).

Yates said she began their meeting by laying out the media accounts and media statements made by Vice President Mike Pence and other high-ranking White House officials about General Flynn’s activity “that we knew not to be the truth.”

According to Sally Yates testimony, she and Bill Priestap reportedly presented all the information to McGahn so the White House could take action that they deemed appropriate.  When asked by McGahn if Flynn should be fired, Yates answered, “that really wasn’t our call.”

Yates also said her decision to notify the White House counsel had been discussed “at great length.”  According to her testimony: “Certainly leading up to our notification on the 26th, it was a topic of a whole lot of discussion in DOJ and with other members of the intel community.”

•Friday January 27th – (morning)  White House Counsel Don McGahn called Yates in the morning and asked if she could come back to his office.

•Friday January 27th – (late afternoon) According to her testimony, Sally Yates returned to the White House late that afternoon.  One of McGahn’s topics discussed was whether Flynn could be prosecuted for his conduct.

Specifically, according to Yates, one of the questions McGahn asked Yates was, “Why does it matter to DOJ if one White House official lies to another?” She explained that it “was a whole lot more than that,” and reviewed the same issues outlined the prior day.

McGahn expressed his concern that taking action might interfere with the FBI investigation of Flynn, and Yates said it wouldn’t. “It wouldn’t really be fair of us to tell you this and then expect you to sit on your hands,” Yates had told McGahn.

McGahn asked if he could look at the underlying evidence of Flynn’s conduct, and she said they would work with the FBI over the weekend and “get back with him on Monday morning.”

•Friday January 27th – (evening) In what appears to be only a few hours later, President Trump is having dinner with FBI Director James Comey where President Trump asked if he was under investigation.

Now, accepting the politicization of the entire Russian Conspiracy Narrative that was leading the headlines for the two months prior to this dinner; and knowing moments earlier your Chief White House counsel informs you that two political operatives (Yates and Priestap) within the DOJ were providing classified intelligence reports about General Flynn; and knowing the prior months (Nov/Dec/Jan) were fraught with leaks from intelligence reports identical to those discussed;  wouldn’t you perhaps think that any action you take could be utilized to add fuel to this Russian narrative?  And/Or be used by these same leak facilitators to make something seem like something it is not?

Think about it.

Special Counsel Robert Mueller has charged Flynn (full pdf below) with falsely telling FBI agents that he did not ask the ambassador “to refrain from escalating the situation” in response to the sanctions.

According to the plea, while being questioned by FBI agents on January 24, 2017, Flynn also lied when he claimed he could not recall a subsequent conversation with Kislyak, in which the ambassador told Flynn that the Putin regime had “chosen to moderate its response to those sanctions as a result of [Flynn’s] request.”

Furthermore, a week before the sanctions were imposed, Flynn had also spoken to Kislyak, asking the ambassador to delay or defeat a vote on a pending United Nations resolution. The criminal information charges that Flynn lied to the FBI by denying both that he’d made this request and that he’d spoken afterward with Kislyak about Russia’s response to it.

There was nothing wrong with the incoming national-security adviser’s having meetings with foreign counterparts or discussing such matters as the sanctions in those meetings. However, lying to the FBI is the process crime that has led to Flynn’s admissions herein:

https://www.scribd.com/embeds/366062176/content?start_page=1&view_mode=&access_key=key-QHaNTpsHk3My0BRqqECU

As we have shared from the beginning – this is all about DC politics, not judicial crimes in the same vein as everyone else would be charged.

You cannot view the current action through the transactional prism of modern judicial proceedings as they relate to you and me. These are political struggles taking place inside the venue of the legal system. The players use the legal system to game out the optics and narrative of political battles for ideological wins and losses.

In essence, this is about leverage for political use.

Nothing about the current dynamic is factually encompassing President Trump; it is all about optics, narratives and political leverage. However, everything about this dynamic is factually encompassing the existential threat that outsider Trump represents to the established way of life in the DC Swamp.

Again, if you drop the legal prism and review everything from the perspective of gaining or losing political leverage it all makes sense.

♦Here’s my Twitter Thread on “WHY FLYNN LIED” – CLICK HERE

♦Here’s my Twitter Thread on “WHY RECENT IG STATEMENT IS IMPORTANT” – HERE

Germany Companies Demand German Tax Cuts


COMMENT: Mr. Armstrong; It is so clear you understand the basic human response that drives the economy. It is amazing why the entire world does not listen to you. Within 24 hours, German companies are demanding tax cuts to compete with the Trump tax cuts. They realize what you have been saying. The USA will suck in all the business with a low corporate tax rate and they cannot compete. As you say, this is not Noble Prize-winning analysis. Perhaps you should get the Noble Prize even if it is so basic an idiot should understand it.

KL from Germany

REPLY: Good point. I suppose what you are really saying is that common sense is actually rare. I am in Europe for the week and requests for meetings have suddenly skyrocketed. Following the approval in the US Senate for the Trump tax reform, alarm bells are blaring from the German economy. The industry association BDI has come out and already warned on Sunday no less that there will be massive disadvantages for European companies. It is fundamental. The more you raise taxes, the higher the unemployment, and the lower the economic growth. But if you are a politician, it puts more money in your pocket. So they act only in self-interest.

Those countries which do not engage in structural reforms in corporate taxation will watch their economies implode over time. It will be a very hard time ahead into 2021.

Why Socialists Prefer to Take Bribes from the Rich than Let the People Get a Tax Break


The tax cut critics are really just morons if not outright evil people who just want to rob anyone who has more than them. Their analysis put the bill’s total price at $1 trillion, contradicting the Republican argument that the measure would essentially pay for itself. They act as if this is somehow different than Obama, who increased spending that went into the pockets of the bankers.

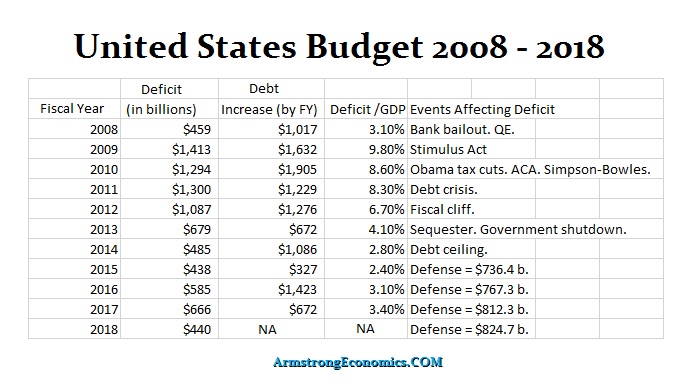
Obama took the budget in his first year from a $459 billion deficit to $1,413 billion and that was OK. His deficits dramatically increased the national debt in his first four years 400% times greater than the Trump tax cut. So why do these people hate tax cuts and constantly point to the rich?

As long as the socialists are taking bribes from the rich and the money goes out the back-door, that is OK because it is not in your face. As soon as we talk about giving the people a DIRECT tax break, then the socialists just cannot stand letting the people actually benefit directly just for once.

The Trump Tax Cut, the Pass-Through, & Multinationals


The Trump Tax Reform is a very major deal. There are seven brackets in today’s individual tax code. The Senate version of the Trump Reform is not a windfall for the rich lowering their bracket from 39.6% to just 38.5%. The seven tax brackets currently are:

10%, 15%, 25%, 28%, 33%, 35%, and 39.6%.

Changes individual income tax brackets will be:


– 10% (income up to $9,525 for individuals; up to $19,050 for married couples filing jointly)
– 12% (over $9,525 to $38,700; over $19,050 to $77,400 for couples)
– 22% (over $38,700 to $70,000; over $77,400 to $140,000 for couples)
– 24% (over $70,000 to $160,000; over $140,000 to $320,000 for couples)
– 32% (over $160,000 to $200,000; over $320,000 to $400,000 for couples)
– 35% (over $200,000 to $500,000; over $400,000 to $1 million for couples
– 38.5% (over $500,000; over $1 million for couples)

The House bill, by contrast, only calls for four brackets: 12%, 25%, 35% and 39.6%.

Both the House and Senate bills nearly double the standard deduction. For single filers, the Senate bill increases the standard deduction to $12,000 from $6,350 currently; and it raises it for married couples filing jointly to $24,000 from $12,700. This will be a very big tax benefit for the low end. It will also reduce the number of people who itemize their deductions to get more deductions which complicate matters for most people.

However, currently, you’re allowed to claim a $4,050 personal exemption for yourself, your spouse and each of your dependents. Both the Senate and House bills eliminate that option. Large families with three or more children will probably not benefit from this change. The Average number of people per household in an American family in the United States from 1960 to 2016 consisted of 2.53 people. So for the average household, this will still be a tax cut.

Nevertheless, the Senate bill increases the child tax credit to $2,000 per child, up from $1,000 today, and above the $1,600 proposed in the House bill. This will help ease the pain for bigger families. The age limit will be available for any children under 18, up from today’s under-17 age limit. But it reverts to under 17 again in 2025, a year before the increase is set to expire on the bill. This is crazy since the 17-year old cannot vote and cannot be drafted. Yet, the Senate bill also greatly expanded the eligibility for the credit by raising the ceiling on the income thresholds. Currently, the credit starts to phase out in the higher brackets. For married tax filers, that ceiling was set at $110,000 and the Senate has raised it substantially to $500,000. What does change is the subsidy. If you pay no tax, you get no credit whereas today you get $1,000 even if you pay no taxes. 

For the first time, people taking care of their parents as dependents in old age have not been able to deduct them from the children credits. Now, these people will get a new $500 nonrefundable credit per dependent. Under the House bill, there would be a new $300 per person credit for parents and dependents over 17.
The biggest controversial provision is eliminating the deduction for state income tax. This has been bantered around for decades. It has finally come to reality. I recall in New Jersey when the income tax was put in, the sales promotion was it would cost you nothing because you would be able to deduct it from the federal income tax. This has been a major gripe in Washington for it has unjustly incentified states to spend without limit increasing state income tax at the expense of other states. So this will finally eliminate that deduction and at last, those living in insanely taxed states like New England area and California, will wake up and realize their local government has been squandering the money on themselves. With a rise in population, taxes should decline, but they only keep going up in New York and California without end.
The real estate killer is also here. Up to now, those who itemize deduction have been deducting their property taxes as well as their state and local income or sales taxes. There have been many who called for this to be eliminated for it too is subsidizing reckless local spending with no accountability. Every municipal government has usually all the top management expenses for salaries and pensions. This has driven so many to abuse the legal process transforming their police into revenue agents who no longer protect society, but exploit it for their own salaries with tickets and fines.

While the original Senate bill called for a full repeal of the property tax deduction, it was amended to preserve an itemized deduction for property taxes but only up to $10,000, which is identical to the House measure. Once again, those in big houses or the high taxed states paying more than $10,000 in property taxes will for the first time feel the real cost of their local corruption.

The Senate bill would still let you claim a deduction for the interest you pay on mortgage debt up to $1 million. The House wants to cap the loan limit at $500,000 for new mortgages. Since the House and Senate bills both sharply increase the standard deduction, the percent of filers who claim the mortgage deduction would decline significantly anyway. If this were eliminated along with property taxes, we would see a real estate crash that would make the S&L Crisis look trial run. No doubt, Trump understand that one unlike the Democrats back in the 1980s.

Interestingly, there are some changes that will impact the real estate market and take the froth off the surface. The Senate bill makes two important changes on home-related financing. It disallows interest deductions for home equity loans. And it lengthens the time you must live in a home to get the full tax-free exclusion on your gains when you sell it. Therefore, this will impact the borrow against your home market all over the radio if they tell the consumer the truth that a home equity loan will NOT BE DEDUCTIBLE. Additionally, this will impact the home-flippers as well who have been calling their income capital gains when they are flipping homes as a business.

The Senate kept the Alternative Minimum Tax (AMT), but it raises the amount of income exempt from it. The AMT originally was intended to ensure the richest tax filers pay at least some tax by disallowing many tax breaks at the high end. Now filers making between $200,000 and $1 million today will have to pay the tax. So once again, it is not a windfall for the rich.

The clash between the Senat and the House comes into play really with the death tax. Unlike the House bill, Senate Republicans have not proposed repealing the estate tax. Instead, the Senate proposed to double the exemption levels. Death Taxes have been destructive when it comes to trying to keep a family small business or farm going. The founder has paid taxes their whole life. Then when they die, the government wants to prevent you from saving for your family after you are gone. This has resulted in selling off farmland to pay taxes and the consolidation of farming into the hands of big corporations. Likewise, small businesses are in the same boat.
The other clash between the Senate and the House is medical expenses. Currently, those who itemize their deductions may include their medical and dental expenses that exceed 10% of their adjusted gross income. The House bill eliminates that deduction, while the Senate bill retains it and temporarily lowers that 10% threshold to 7.5% for tax years 2017 and 2018.

Obamacare mandate to buy health insurance is included as a repeal to reduce the taxes on the youth. It is estimated to save money since fewer people who qualify for subsidies if they actually bought insurance. Currently, they pay the Obamacare Tax and are subsidized.
 

The big issue will be with business. The Senate bill, like the House bill, cuts the corporate tax rate to 20% from 35% today. But the 20% rate would not take effect until 2019 under the Senate proposal. The delay would reduce the cost of the measure in the first 10 years. But this will also reduce the likelihood of an economic boom short-term. The Senate Republicans did make it possible for businesses to immediately and entirely expense new equipment for five years. This the morons think will be beneficial to the economy. Not everyone is into heavy equipment. Reducing the corporate tax rate will allow companies to expand and hire more high-end staff rather than buy equipment. They are obviously living still in the old world of heavy manufacture.

Most U.S. businesses are set up as pass-throughs, and not corporations. That means their profits are passed through to the owners, shareholders, and partners, who pay tax on them on their personal returns under ordinary income tax rates. Both the Senate and House bills lower taxes on the business portion of a filer’s pass-through income. The House bill dropped the top income tax rate to 25% from 39.6%, while prohibiting anyone providing professional services, which will include lawyers and accountants. The professional services groups will not be allowed to take advantage of the lower rate. It also phases in a lower rate of 9% for businesses that earn less than $75,000.

The Senate bill lowers taxes on filers who pass-through their business earnings by letting them deduct 23% of their income, up from 17.4% originally. The 23% deduction would be prohibited for anyone in a service business — except those with taxable incomes under $500,000 if married ($250,000 if single). There is a carve-out. Should the owner or partner of a pass-through operation also draws a salary from the business, that money would be subject to ordinary income tax rates.

In order to curb people from recharacterizing their wage income as business profits to get the benefit of the pass-through deduction, the Senate bill would automatically limit the deduction to half of the W-2 wages of the pass-through entity or its share to the individual taxpayer. The W-2 rule would not apply, however, if the filer’s taxable income is under $500,000 if married, $250,000 if single.
The big change will be how the US-based multinational corporations will be taxed. Currently, U.S. companies pay taxes on all their profits, regardless of where the income is earned. They’re allowed to defer paying U.S. tax on their foreign profits until they bring the money home. This is why there is such a vast hoard of about $3 trillion overseas.

Without question, the “worldwide” tax system puts American businesses and citizens at a huge disadvantage when other nations (except Japan) tax income earned in the place you are domiciled. The theory is fair. Taxes are supposed to be for your “fair share” of services provided by the government. If you are not living there, then what is your fair share of services that you do not use? ZERO! Foreign competitors come from countries that do not tax worldwide income and they can compete to get projects to build dams in China and beat American firms every time. I testified before that very issue in front of the House Ways and Means Committee back in the 1990s.

The Supreme Court in 2015 held that the Maryland income tax was unconstitutional because it did not allow a resident or corporation to deduct taxes paid to other territories on its income derived out of the state (See: COMPTROLLER OF THE TREASURY OF MARYLAND v. WYNNE ET UX., 575 US _ (2015)). The Supreme Court previously held in  Central Greyhound Lines, Inc. v. Mealey, 334 US 653, 662 (1948), which invalidated state tax schemes that might lead to double taxation of out-of-state income in violation of the Commerce Clause.

The entire problem stems from the fact that Congress never defined “income” in the legislation. That left the door open for the Supreme Court to determine what was and what was not income. As a result, the Court decided in Eisner v. Macomber 252 US 189 (1920) to address that question. The starting point was their reference to the dictionary. “Income may be defined as the gain derived from capital, from labor, or from both combined, provided it be understood to include profit gained through a sale or conversion of capital assets.” The Court then went into a lengthy explanation as to how this definition applies to a stock dividend which the case was all about. In the end, the Court decided that the stock dividend was not taxable because it was merely a book adjustment and was not “severable” from the underlying stock. In other words, income would not be realized until the stock itself was sold.

After the Eisner decision, what emerged was a new question. The next challenge reached a climax in 1924 when the Supreme Court ruled in COOK v. TAIT, 265 U.S. 47 (1924) brought by a U.S. citizen living in Mexico that taxing non-resident citizens on their global income was indeed constitutional. This is the paragraph that has severely ignored the foundation of territorial jurisdiction recognized by the entire world.

“The contention was rejected that a citizen’s property without the limits of the United States derives no benefit from the United States. The contention, it was said, came from the confusion of thought in ‘mistaking the scope and extent of the sovereign power of the United States as a nation and its relations to its citizens and their relation to it.’ And that power in its scope and extent, it was decided, is based on the presumption that government by its very nature benefits the citizen and his property wherever found, and that opposition to it holds on to citizenship while it ‘belittles and destroys its advantages and blessings by denying the possession by government of an essential power required to make citizenship completely beneficial.’ In other words, the principle was declared that the government, by its very nature, benefits the citizen and his property wherever found, and therefore has the power to make the benefit complete. Or, to express it another way, the basis of the power to tax was not and cannot be made dependent upon the situs of the property in all cases, it being in or out of the United States, nor was not and cannot be made dependent upon the domicile of the citizen, that being in or out of the United States, but upon his relation as citizen to the United States and the relation of the latter to him as citizen. The consequence of the relations is that the native citizen who is taxed may have domicile, and the property from which his income is derived may have situs, in a foreign country and the tax be legal-the government having power to impose the tax.”
This holding that a citizen of the United States is forever an indentured servant of the country and can never escape taxes even if they left the country permanently. This defies every principle of the Constitution and the American Revolution for previously, if you were British and killed someone in Paris, the French could not prosecute you because you were the “property” of the king. They sent you back in chains and told the English king what you did and beg his vengeance. The ruling in Cook goes against territorial jurisdiction and is inconsistent with every other ruling on jurisdiction since inception. But once it is concerning taxes, the Supreme Court reverted to you are the property of the state.

With that Eisner definition of income, was any income not clearly covered by its terms deemed to be nontaxable? In Helvering v. Bruun, 309 U.S. 461 (1940), the Court addressed the question of whether or not a lessor recognizes income from the receipt of a leasehold improvement made by a lessee during the lease when the improvement reverts to the lessor at the end of the lease. The Court ruled that the value of the improvement was taxable, noting that NOT every gain need be realized in cash to be taxable. There was a clear increase in the taxpayer’s wealth, and this increase did not have to be severed to recognize such increase as income for federal income tax purposes. This ruling could wipe out profits in BitCoin since it is marketed as a currency and that means it would be taxable even if you did not cash-in BitCoin. Then in Commissioner v. Glenshaw Glass Co., 348 U.S. 426 (1955), the Court severely qualified Eisner ruling that punitive damages recovered under a violation of anti-trust laws were included in gross income.

The Senate bill proposes changes to move the U.S. to a territorial system. which is long overdue. Congress NEVER authorized worldwide income taxes. That was the Supreme Court which simply ruled that they never said no. It also includes a number of anti-abuse provisions to prevent corporations with foreign profits from gaming the system. Companies will be required to pay a one-time low tax rate on their existing overseas profits — 14.5% on cash assets and 7.5% on non-cash assets such as equipment abroad in which profits were invested. This is slightly higher than the 14% and 7% rates in the House bill.


While the Trump Tax Reform will certainly not benefit the rich, the critics who simply argue the national debt will rise are just arguing nonsense. The national debt will continually rise because there is NEVER a balanced budget and there is NEVER any intent to ever pay off the debt. Up to now, the benefits go to the rich who donate big bucks to both parties and never to small business who do not lobby or to the average person. This is a much fairer way of dealing with the issues and of course, the Democrats will vote against it simply because they like the high taxes and handout tax exceptions behind the curtain for donations and law revisions like Hillary promising the bankers the moon.

Politicians & Kicking the Can Down the Road


QUESTION: Hi Marty,

Thank you for replying to my earlier question about The Crash & No Bid. It as very insightful towards the mechanics of markets. I have a new question for you regarding how Politicians “kick the can” as long as they can expecting the next people in line to pick up the tab… and never pay!

I was told by my uncle that the reason why politicians were lowering interest rates was so that they could keep increasing their perpetual deficit. But- since we have hit the turning point in interest rates and that rates are on the rise do you foresee politicians promoting hyper-inflation while fixing payable amounts on things like “pensions”? I believe that if they can dilute / water down money through inflation that the pension funds would then appear to “be on budget” (kicking the can further down the road, and also creating civil unrest)?

The way I see it is that if politicians were using low-interest rates to create cheaper money, could their next move potentially be diluting the huge quantity of money ….. cause they have nowhere else to go! (along with the hunt for taxes)

NG From Vancouver Island, Canada

ANSWER: I completely understand that from the outside looking in, it appears that the politicians are kicking the can down the road because they KNOW what will happen. It also appears that they have created lower interest rates to allow them to reduce their borrowing costs and spend more. I hate to burst everyone’s bubble here, but the truth is MUCH WORSE. All of these assumptions and conspiracy theories are based upon the common foundation that they PRESUME the politicians even understand what they are doing. They are NOT that intelligent. Sorry!

Politicians have absolutely ZERO perspectives on the future. They assume that whatever trend is in motion, will remain in motion. When I have been in meetings around the world and asked about the policy of borrowing year after year with no intention of paying anything back, I get the blank stare as their eyes glaze over. I then point out again, there is absolutely no plan to ever pay down even a small portion of the national debt. I then state you do know you cannot keep borrowing like this forever? I follow this up with the question, you do know that at some point you will not be able to see public debt? That finally gets the response! Yes, a company or individual cannot do that, but we are the government.

They actually believe their own lies. They believe that their debt is AAA and people will buy it forever above all else no matter what they do. When I say that have never been the historical case, I get the classic statement – this time it’s different!

The lower rates have been maintained by7 the central banks. But the Fed is caught between a rock and a hard-headed place called Congress. The Fed cannot control long-term rates. The best they can do is try to “influence” long-term rates and they did that by buying in 30-year bonds. The understands that the lower rates are undermining the pension system. It may be helping government spend more, but politicians control fiscal policy and the central bank controls only monetary policy. No central bank can stabilize the fiscal spending.

Therefore, this will simply erupt like a financial volcano and that is when my phone turns red hot. All of a sudden, the screams all sound the same. You can tell them this will happen. Nobody will risk their career to prevent a crisis. They love the crisis for they then promise to always get the guy that caused it even when it is them. There are no mirrors. They simply blame people in the private sector every single time.


Attorney General Jeff Sessions, FBI Spox and Office of DOJ Inspector General Release Statements


Did you know the DOJ has been investigating the FBI for 11 months…. wait, what?

Hold-up on the criticism folks.  Three important statements today from the DOJ, FBI and OIG indicate there have been ongoing investigations and reviews of conduct within the upper tiers of leadership within the Department of Justice and the FBI.

Given the nature of the leaked IG investigation to the Washington Post and New York times; surrounding apex investigator and deputy head of counterintelligence at the FBI Peter Strzok; and accepting the direct approach of President Trump in his tweets toward that revelation; and adding the layer of Intel Chairman Devin Nunes threatening to file ‘contempt of congress charges‘; there is every indication something is about to break – very soon.

(L-R) Attorney General Jeff Sessions – FBI Director Christopher Wray

“[The allegations] if proven to be true, would raise serious questions of public trust. I look forward to receiving the Inspector General’s report. We will ensure that anyone who works on any investigation in the Department of Justice does so objectively and free from bias or favoritism.”

“My job is to restore confidence in the Department of Justice in all aspects of our work and I intend to do so. As such, I have directed that the FBI Director review the information available on this and other matters and promptly make any necessary changes to his management and investigative teams consistent with the highest professional standards.”

~ Attorney General Jeff Sessions

“When the FBI first learned of the allegations, the employees involved were immediately reassigned, consistent with practices involving employee matters.”

~ FBI Spokesperson

Here’s the critical OIG statement:

“The January 2017 statement issued by the Department of Justice Office of the Inspector General (OIG) announcing its review of allegations regarding various actions of the Department of Justice and the Federal Bureau of Investigation in advance of the 2016 election stated that the OIG review would, among other things, consider whether certain underlying investigative decisions were based on improper considerations and that we also would include issues that might arise during the course of the review.

The OIG has been reviewing allegations involving communications between certain individuals, and will report its findings regarding those allegations promptly upon completion of the review of them.”

~ Justice Department Office of the Inspector General

What the OIG statement is saying is that for 11 months the Dept of Justice OIG office has been investigating the politicization within the DOJ and FBI and deciding if the actions, or lack of action, was driven by the political ideology of the participants therein.

I was not aware this investigation was taking place, were you?

Apparently the DOJ-OIG is close to “reporting its findings.”

It would be prudent to withhold negative opinion of AG Sessions and FBI Director Wray until we can see the outcome of the Inspector General findings – which will, given the duration of the investigation, likely be a very lengthy and extensive report.

All of a sudden the recent FBI leaks to the Washington Post and New York Times make more sense.  All of the embedded political agents within the DOJ and FBI are quite possibly about to be exposed.  This would explains a lot of the current activity and visible angst from within the participants of the professional administrative state.

This year-long OIG investigation could possibly explain a great deal of the current headlines on all sides of the DC spectrum.  The black hats are on the cusp of being exposed.