Dow Surges With Biggest Gains on News of Best Holiday Shopping Season…


…The Dow Jones Industrial Average rose 5%, or more than 1,000 points, and recorded the largest daily point gain in its history. Meanwhile, the S&P 500 climbed 4.9%…. (more)

(Via CNBC) Retail is having its best holiday shopping season in six years, according to early data tracking consumers’ purchases.

Sales in the U.S. from Nov. 1 through Christmas Eve were up 5.1 percent to more than $850 billion, according to Mastercard SpendingPulse, which monitors spending both in stores and online via all forms of payment. Mastercard also said online sales during that time frame were up 19.1 percent from a year ago, in line with earlier reports that showed robust growth in e-commerce this holiday season.

And this all comes amid the latest fluctuations in the stock market, worries on Wall Street about a potentially slowing economy and a partial government shutdown. Consumer confidence remains strong, translating into robust retail sales, said Steve Sadove, former CEO of Saks and currently advisor for Mastercard.  (read more)

CEA Chairman Kevin Hassett Discusses Main Street Growth and Fed Impacts…


Council of Economic Advisers Chairman Kevin Hassett appears on Fox Business news to discuss the impact of the Federal Reserve’s interest rate hikes on the Main Street economy and the state of the Wall Street stocks.

The key metric is to accept what’s happening around us.  Fed rate hikes are hurting Wall Street (investment class).  However, Fed activity is not yet impacting Main Street.  This is because the two economic engines (Wall St. -vs- Main St.) are so far apart.

.

Part Two of this interview (and expanded review) is below:

.

Three decades of monetary and administrative policy has favored Wall Street (globalism) over Main Street (nationalism).  Decades ago… Main Street and Wall Street used to be connected; stocks were evaluated on company performance; the companies were mostly American, and invested in the success of USA (middle class).

However, changes in monetary policy and political priorities, specifically to the benefit of Wall Street investment instruments (multinational global expansion), drove Wall Steet and Main Street ever further apart.

As a direct result when the Main Street economic engine becomes the focus of favorable policies (trade policy, energy policy, manufacturing policy, tax policy, deregulation etc.), the domestic US economy expands… bigly…

….AND now the Fed takes action in response to ever-expanding strength in our Main Street economy; but, that Fed action will take time to traverse the decades-wide gap… and the first impact will be negative to the original benefactor; the one closer to the actual monetary policy, that’s Wall Street.

I hate to keep harping the point, but this was predicted two years ago:

Understanding the distance between the real Main Street economic engine and the false Wall Street economic engine will help all of us to understand the scope of an upcoming economic lag; which, rather remarkably I would add, is a very interesting dynamic.

Think about these engines doing a turn about and beginning a rapid reverse. GDP can, and in my opinion, will, expand quickly. However, any interest rate hikes (monetary policy) intended to cool down that expansion -fearful of inflation- will take a long time to traverse the divide.  (more)

The Fed is using the opportunity of a strong national U.S. economy, and strong growth in U.S. wealth, to withdraw all of the underlying stimulus money (cheap money) that was needed to fill the gap during the global exfiltration of wealth under prior administration policies.

During the Bush, Clinton-Clinton, Bush-Bush, Obama-Obama years, Main Street middle-class Americans became more poor.   Wall Street investment class became more rich. Multinational corporate globalism drove the policy. The wealth gap is a direct result.

Over the past 30-years, increased income subsidies became a part of administration policy in an effort to fill a void from depressed wage growth. Welfare and food stamp distribution necessarily expanded.

President Trump’s economic policies are the exact opposite of globalism.  Policy to the benefit of working middle-class Americans (ie. America-First nationalism) is against the interests of the corporate multinationals.

Yes, it is unfair to President Donald Trump for the Federal Reserve to essentially buy back all the cheaply printed money used to prop up Wall Street’s schemes.  After all, it is a Fed action only possible because the U.S. economy is so strong.  President Trump’s success is essentially providing the Fed the opportunity to strengthen dollars and make them more valuable.  However, it is what it is…. though Trump’s annoyance is well understood.

Wall Street is getting hurt most; there is more pain ahead for those investment instruments on Wall Street that are dependent on globalism; but the negative Fed impacts to Main Street –as a whole– will not be felt in the aggregate until the two engines once again gain parity.

Again, as predicted: “Those who benefit from high-yield international investment instruments will see less wealth. Those who live on savings will see a benefit.  Those living day-to-day and week-to-week on their paychecks will see more income and wealth.”

2016 – […] Those global manufacturing economies will first respond to any increases in export costs (tariffs etc.), by driving their own productivity higher as an initial offset, in the same manner American workers went through in the past two decades.  The manufacturing enterprise and the financial sector remain focused on the pricing.

♦ Inflation on imported durable goods sold in America, while necessary, will ultimately be minimal during this initial period; and expand more significantly as time progresses and off-shored manufacturing finds less and less ways to be productive.   Over time, durable good prices will increase – but it will come much later.

♦ Inflation on domestic consumable goods ‘may‘ indeed rise at a faster pace. However, it can be expected that U.S. wage rates will respond faster, naturally faster, than any monetary policy because inflation on fast-turn consumable goods becomes re-coupled to the ability of wage rates to afford them.

The monetary policy impact lag, caused by the distance between federal fiscal action and the domestic Main Street economy, will now work in our favor.  That is, in favor of the middle-class.

President Trump and First Lady Melania Make Surprise Trip to Middle-East…


Speculation of President Trump heading to visit troops began early this morning as an overnight takeoff for Air Force-One was strongly rumored.  Additionally the White House press room has been silent and POTUS Trump has been unusually quiet on his social media.

In a statement posted on Twitter, White House Press Secretary Sarah Sanders confirmed the visit in a tweet shortly after Reuters shared the photos of the president in Iraq.

President Trump and the First Lady traveled to Iraq late on Christmas night to visit with our troops and Senior Military leadership to thank them for their service, their success, and their sacrifice and to wish them a Merry Christmas.  (Link)

Additionally, the Daily Mail has more pictures  in Iraq.

Advertisements

Trump v the Federal Reserve


QUESTION: Mr. Armstrong; A spectacular call. You gave the day and the market bottomed within 100 points of your number. You always nail it. I find it curious how they blamed Trump and the Fed. Can Trump fire the head of the Fed? I really think he seriously needs to attend your WEC. He would have seen this move coming.

Congrats!

FG

ANSWER: No. President Trump’s comments about firing Federal Reserve Chairman Jerome Powell are really off the wall. The problem is he has the classic TV talking heads view that stocks will crash with higher interest rates. Trump’s frustration with the central bank chief intensified following the interest-rate increase and months of stock-market losses. He is oblivious to the real crisis which is the low-interest rates are destroying the pension funds.

Meanwhile, the media blames Trump for his tweets and the talking heads attribute the decline to interest rates. Powell cannot publicly state why rates have to rise or he would create a real debt panic. Trump is clueless as is Capitol Hill with the monumental crisis in global debt.

For now, the news will bash the stocks when down, and when investors/traders see there can be no flight to bonds as quality, the real panic will begin. I wish I could reverse this mess, but reality states Trump’s handlers are rooting for the Deep State and would never let me near him.

The Democrats want the stocks to crash for they can blame Trump and try to win the losers to vote for their team. The shame here is this is not about running the nation or the economy to benefit all, it is just about winning the 2020 election. Since the ECM turns in January 2020 rather than the elections in November 2020, this is indicating that we may have a psychological shift prior to the elections.

MAGAnomics: Mastercard Releases First Tabulated Holiday Sales Report With Whopping 5.1% Increase


As CTH anticipated the first tabulated holiday sales report via Mastercard® shows the results of a very strong consumer confidence level.  The first report highlights a very strong 5.1% increase in holiday purchases:

“Wall Street is running around like a chicken with its head cut off, while Mr. and Mrs. Main Street are happy with their jobs, enjoying their best wage increases in a decade”…

~ Craig Johnson, president of Customer Growth Partners

(Via Wall Street Journal)  Shoppers delivered the strongest holiday sales increase for U.S. retailers in six years, according to early data.

Total U.S. retail sales, excluding automobiles, rose 5.1% between Nov. 1 and Dec. 24 from a year earlier, according to Mastercard SpendingPulse, which tracks both online and in-store spending with all forms of payment. Overall, U.S. consumers spent over $850 billion this holiday season, according to Mastercard.

[…] Retailers entered the holidays with momentum as online sales jumped 26.4% from a year earlier between the Wednesday before Thanksgiving through Black Friday.

[…] Sales at department stores fell 1.3% in the period tracked by Mastercard, in part due to store closings. Stores that mainly sell apparel, however, experienced robust sales, growing 7.9% during the same period. Overall, sales from bricks-and-mortar stores rose 3.3%.  (read more)

It will be interesting to see how the fourth quarter GDP growth is impacted by strong consumer sales.  Generally consumer sales make up two-thirds of GDP calculations; however, there was a strong front-loading of imported inventory at the end of the 3rd quarter (Sept).

The preliminary data suggests Main Street is indeed benefiting from a strong domestic economy.  Low unemployment, lower taxes and higher wages equals more disposable income.  That foundation likely fueled the increase in consumer spending throughout the holidays.

Wall Street is being impacted by their multinational reliance which is heavily weighted toward global investments.  Main Street is driven by the actual U.S.A. checkbook economic factors.  This is the modern disconnect.  After decades of Wall Street companies investing overseas, and generating investment products that are fundamentally detached from the U.S. economy, they do not benefit from a strong U.S. economy.  However, Main Street directly gains from internal U.S. economic growth.

It is likely retail stocks with a heavy weight on the U.S. consumer market will see a resurgence in stock market value.  Last year’s 2017 holiday sales were approximately $598 billion as measured by Consumer Growth Partners.  This year’s holiday sales look to be around $850 billion, as measured by the same data firm.

There really is a big disconnect between Wall Street and Main Street.

If you understand the basic elements behind the new dimension in American economics, you already understand how three decades of DC legislative, monetary and regulatory policy was structured to benefit Wall Street and not Main Street. The intentional shift in monetary policy is what created the distance between two entirely divergent economic engines.

REMEMBER […] there had to be a point where the value of the second economy (Wall Street) surpassed the value of the first economy (Main Street).

Investments, and the bets therein, needed to expand outside of the USA. hence, globalist investing.

However, a second more consequential aspect happened simultaneously. The politicians became more valuable to the Wall Street team than the Main Street team; and Wall Street had deeper pockets because their economy was now larger.

As a consequence Wall Street started funding political candidates and asking for legislation that benefited their interests.

When Main Street was purchasing the legislative influence the outcomes were -generally speaking- beneficial to Main Street, and by direct attachment those outcomes also benefited the average American inside the real economy.

When Wall Street began purchasing the legislative influence, the outcomes therein became beneficial to Wall Street. Those benefits are detached from improving the livelihoods of main street Americans because the benefits are “global”. Global financial interests, multinational investment interests -and corporations therein- became the primary filter through which the DC legislative outcomes were considered.

There is a natural disconnect. (more)

As an outcome of national financial policy blending commercial banking with institutional investment banking something happened on Wall Street that few understand. If we take the time to understand what happened we can understand why the Stock Market grew and what risks exist today as the monetary policy is reversed to benefit Main Street.

President Trump and Treasury Secretary Mnuchin have already begun assembling and delivering a new banking system.

Instead of attempting to put Glass-Stegal regulations back into massive banking systems, the Trump administration is creating a parallel financial system of less-regulated small commercial banks, credit unions and traditional lenders who can operate to the benefit of Main Street without the burdensome regulation of the mega-banks and multinationals. This really is one of the more brilliant solutions to work around a uniquely American economic problem.

♦ When U.S. banks were allowed to merge their investment divisions with their commercial banking operations (the removal of Glass Stegal) something changed on Wall Street.

Companies who are evaluated based on their financial results, profits and losses, remained in their traditional role as traded stocks on the U.S. Stock Market and were evaluated accordingly. However, over time investment instruments -which are secondary to actual company results- created a sub-set within Wall Street that detached from actual bottom line company results.

The resulting secondary financial market system was essentially ‘investment markets’. Both ordinary company stocks and the investment market stocks operate on the same stock exchanges. But the underlying valuation is tied to entirely different metrics.

Financial products were developed (as investment instruments) that are essentially wagers or bets on the outcomes of actual companies traded on Wall Street. Those bets/wagers form the hedge markets and are [essentially] people trading on expectations of performance. The “derivatives market” is the ‘betting system’.

♦Ford Motor Company (only chosen as a commonly known entity) has a stock valuation based on their actual company performance in the market of manufacturing and consumer purchasing of their product. However, there can be thousands of financial instruments wagering on the actual outcome of their performance.

There are two initial bets on these outcomes that form the basis for Hedge-fund activity. Bet ‘A’ that Ford hits a profit number, or bet ‘B’ that they don’t. There are financial instruments created to place each wager. [The wagers form the derivatives] But it doesn’t stop there.

Additionally, more financial products are created that bet on the outcomes of the A/B bets. A secondary financial product might find two sides betting on both A outcome and B outcome.

Party C bets the “A” bet is accurate, and party D bets against the A bet. Party E bets the “B” bet is accurate, and party F bets against the B. If it stopped there we would only have six total participants. But it doesn’t stop there, it goes on and on and on…

The outcome of the bets forms the basis for the tenuous investment markets. The important part to understand is that the investment funds are not necessarily attached to the original company stock, they are now attached to the outcome of bet(s). Hence an inherent disconnect is created.

Subsequently, if the actual stock doesn’t meet it’s expected P-n-L outcome (if the company actually doesn’t do well), and if the financial investment was betting against the outcome, the value of the investment actually goes up. The company performance and the investment bets on the outcome of that performance are two entirely different aspects of the stock market. [Hence two metrics.]

♦Understanding the disconnect between an actual company on the stock market, and the bets for and against that company stock, helps to understand what can happen when fiscal policy is geared toward the underlying company (Main Street MAGAnomics), and not toward the bets therein (Investment Class).

The U.S. stock markets’ overall value can increase with Main Street policy, and yet the investment class can simultaneously decrease in value even though the company(ies) in the stock market is/are doing better. This detachment is critical to understand because the ‘real economy’ is based on the company, the ‘paper economy’ is based on the financial investment instruments betting on the company.

Trillions can be lost in investment instruments, and yet the overall stock market -as valued by company operations/profits- can increase.

Conversely, there are now classes of companies on the U.S. stock exchange that never make a dime in profit, yet the value of the company increases. This dynamic is possible because the financial investment bets are not connected to the bottom line profit. (Examples include Tesla Motors, Amazon and a host of internet stocks like Facebook and Twitter.) It is this investment group of companies that stands to lose the most if/when the underlying system of betting on them stops or slows.

Specifically due to most recent U.S. monetary policy, modern multinational banks, including all of the investment products therein, are more closely attached to this investment system on Wall Street. It stands to reason they are at greater risk of financial losses overall with a shift in monetary/fiscal policy.

That financial and economic risk is the basic reason behind Trump and Mnuchin putting a protective, secondary and parallel, banking system in place for Main Street.

Big multinational banks can suffer big losses from their investments, and yet the Main Street economy can continue growing, and have access to capital, uninterrupted.

Bottom Line: U.S. companies who have actual connection to a growing U.S. economy can succeed; based on the advantages of the new economic environment and MAGA policy, specifically in the areas of manufacturing, trade and the ancillary consumer benefactors.

Meanwhile U.S. investment assets (multinational investment portfolios) that are disconnected from the actual results of those benefiting U.S. companies, and as a consequence also disconnected from the U.S. economic expansion, can simultaneously drop in value even though the U.S. economy is thriving.

Advertisements

President Trump and First Lady Melania Deliver a White House Christmas Message…


U.S. President Donald Trump and First Lady Melania Trump deliver their Christmas holiday message from the White House.

.

Advertisements

President Trump Participates in Christmas Call To Military….


Earlier today President Donald Trump participated in a Christmas call to service members stationed at remote sites worldwide thanking them for their service to our Nation.

The participants were units from all five branches of the Armed Forces: •Army – Task Force Talon, Anderson Air Force Base, Guam; •Marine Corps – Marine Attack Squadron 223, Sheik Isa Airbase, Bahrain; •Navy – Naval Forces Central Command, Manama, Bahrain; •Air Force – 379th Air Expeditionary Wing, Al Udied Air Base, Qatar; •Coast Guard – Coast Guard District 7, Juneau, Alaska.

German Hyperinflation & the Dawes Plan


The German Hyperinflation was by NO MEANS about inflation created by an increase in the money supply under the Quantity Theory of Money (QTM). Today, Angela Merkel has forcefully imposed Austerity upon the whole of Europe because she really does not understand what even caused the hyperinflation. It was at the Palace of Versailles outside Paris when Germany signed the Treaty of Versailles on June 28th, 1919 with the Allies, officially ending World War I. AT that time, the English economist John Maynard Keynes attended the peace conference. However, Keynes left in protest of the treaty becoming the first outspoken critic of what would prove to be the most punitive agreement that only set the stage for World War II and the rise of Adolf Hitler in 1933.

John Maynard Keynes wrote in his The Economic Consequences of the Peace, which he published in December 1919, that the harsh war reparation payments and other harsh terms that they were to impose on Germany by the treaty would lead to the financial collapse of the country. Keynes further warned that this Treaty would result in serious economic and political repercussions on Europe and the world as a whole. The political trend at the time refused to listen. This was all about punishing Germany.

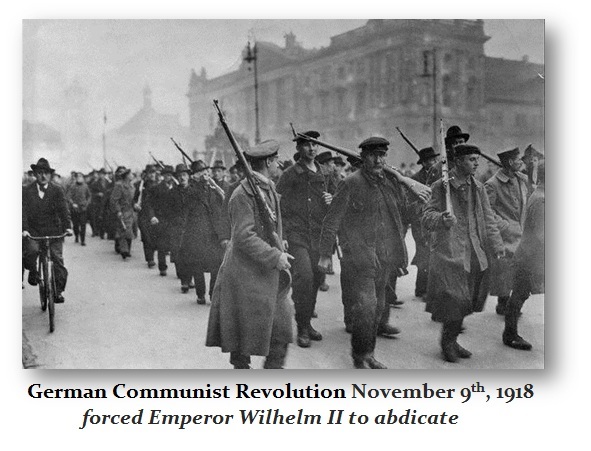
We must also understand that wars are created by politicians – not the people. Prior to the Treaty of Versailles signed in June 1919there was the German Communist Revolution which began the Weimar Republic. It was this 1918 German Communist Revolution which was inspired by the 1917 Russian Revolution that resulted in the overthrown of the monarchy in Germany ending the Emperors and the king of Prussia. The revolutionary period lasted from November 1918 until the adoption in August 1919. But what also seems to be omitted from many accounts taught in school, is the simple fact that the German government interfered in the Russian Revolution and was instrumental in creating the Russian Revolution.

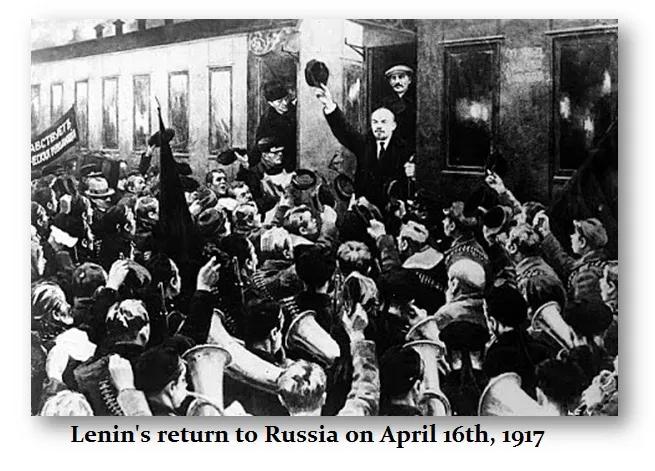
The German Emperor Wilhelm II Imperial Government actually feared that Russia would enter World War I. The rising communist movement in Russia was anti-war. Germany saw a chance for victory in Europe if it kept Russia out of the war. Hence, Germany supported the Communist anti-war sentiment of the Bolsheviks in Russia. Germany permitted Vladimir Lenin (1870-1924) to travel in a sealed train wagon from his place of exile in Switzerland through Germany, Sweden, and Finland to Petrograd. Since the start of the February Revolution in Russia, Lenin was trying to figure out a way to get back into Russia. Germany aided his return assuming he was anti-war and would thus keep Russia out of World War I. Lenin returned to Russian on April 16th, 1917. Within months of arriving, Lenin led the October Revolution in Russia and the Bolsheviks seized power and indeed Russia withdrew from the world war. According to Leon Trotsky, the October Revolution would not have succeeded without Lenin.

With the success of the October Revolution in Russia and the Dream of a new Marxist Utopia, the Germans entered into a civil war and invited Lenin to please take Germany. Clearly, the scheme of the Imperial German government had backfired. It not only was instrumental in creating the Soviet Union by turning over Russia’s socialist transformation decisively into the hands of the Bolsheviks, its plan led to the overthrow of its own hold on power. This is all recorded in contemporary newspapers (see New York Times Nov 11, 1918).

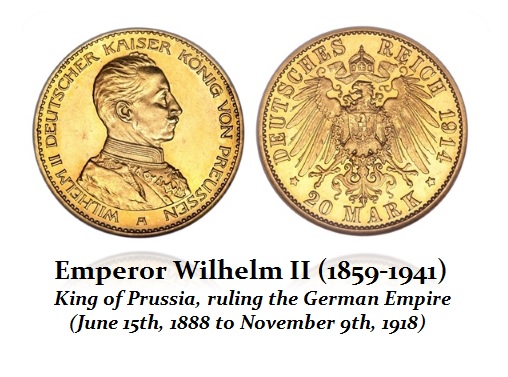
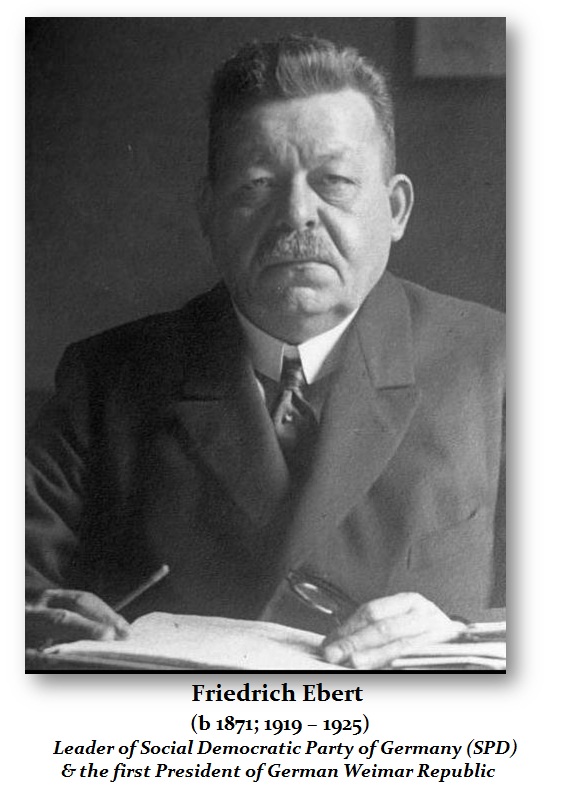
The Prussian Emperor Wilhelm II (1859-1941) found himself in the midst of troubling economic and social disorder. A series of mutinies by German sailors and soldiers undermined Wilhelm II’s government and he lost the support of his military which enabled the German people to revolt. Wilhelm II was forced to abdicate on November 9th, 1918. The very following day, a provisional government was announced composed of the Social Democratic Party (SDP) and the Independent Social Democratic Party of Germany (USDP). To this day, the SDP has remained as a major part against all opposition. Then in December 1918, German elections were held for a National Assembly with the goal of creating a new parliamentary constitution. On February 6th, 1919, the National Assembly met in the town of Weimar and formed the Weimar Coalition. They also elected SDP leader Friedrich Ebert (1871-1925) as President of the Weimar Republic who served from 1919 until 1925.

It was Friedrich Ebert who had to deal with the Treaty of Versailles. When the terms became known on May 7th, 1919, the German people rose in protest. Ebert himself did denounce the treaty as “unrealizable and unbearable” yet he understood that Germany was not allowed to negotiate nor reject the treaty. Ebert even asked Hindenburg if the army could put up a defense if the Allies renewed hostilities. Hindenburg said that the army was not capable of resuming the war even on a limited scale. Ebert then advised the National Assembly to approve the treaty, which it did by a large majority on July 9th, 1919.

The Treaty of Versailles commanded Germany to reduce its military, take responsibility for the World War I, relinquish some of its territories and pay exorbitant reparations to the Allies. It also prevented Germany from joining the League of Nations at that time. Thus, the treaty punished the German people for the sins of its government. Indeed, the military created World War I for it is generally accepted that Wilhelm II was largely just a ceremonial figurehead. During the Sarajevo crisis with the assassination of the Archduke Franz Ferdinand of Austria on June 28th, 1914, he was Wilhelm’s friend and he offered to support Austria-Hungary in crushing the opposition who assassinated the Archduke. Wilhelm went on his annual cruise of the North Sea July 6th, 1914. Wilhelm returned to Berlin on the 28th of July that year and eagerly read a copy of the Serbian reply. Wilhelm wrote his comment on it:

“A brilliant solution—and in barely 48 hours! This is more than could have been expected. A great moral victory for Vienna; but with it every pretext for war falls to the ground, and [the Ambassador] Giesl had better have stayed quietly at Belgrade. On this document, I should never have given orders for mobilization.”

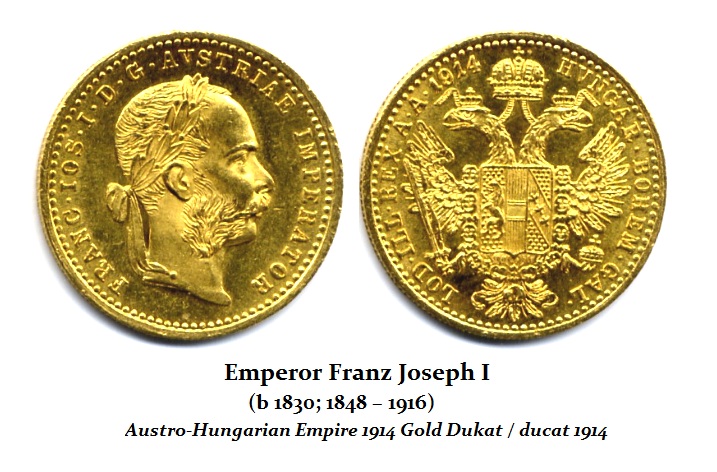
Wilhelm did not know at the time that the military had convinced the Emperor of the Austro-Hungarian Empire, Franz Joseph I (b 1830; 1848 – 1916), to sign a declaration of war against Serbia. As a direct consequence, Russia began a general mobilization to attack Austria in defense of Serbia. Wilhelm wrote a lengthy commentary containing his observations:

“… For I no longer have any doubt that England, Russia and France have agreed among themselves—knowing that our treaty obligations compel us to support Austria—to use the Austro-Serb conflict as a pretext for waging a war of annihilation against us … Our dilemma over keeping faith with the old and honourable Emperor has been exploited to create a situation which gives England the excuse she has been seeking to annihilate us with a spurious appearance of justice on the pretext that she is helping France and maintaining the well-known Balance of Power in Europe.”

In school, I remember being taught that World War I was the result of treaties among governments which then force one to come to the aid of another. Clearly, the Treaty of Versailles set the stage for World War II by its very crushing terms that nobody would be able to meet. The Treaty of Versailles set out a plan for reparations to be paid by Germany requiring to them to pay 20 billion gold marks, as an interim measure, with the final amount to be decided upon at later date. In 1921, the London Schedule of Payments set the German reparation figure at 132 billion gold marks divided into various classes, of which only 50 billion gold marks were required to be paid.

Meanwhile, the industrialists of Germany’s Ruhr Valley lost their factories in Lorraine. Germany had seized Lorraine back in 1870 and now this was to also part of the demands be returned to France. There was also an occupation of the Ruhr industrial area by France and Belgium. The Germans affected by the Treaty and the seizure of their property by France and Belgium now demanded hundreds of millions of marks as compensation from the German government and they paid the Ruhr Valley industrialists for their losses. This also contributed to the German Hyperinflation crisis and it effectively reduced the ability of the German economy to recover.

While the narrow neo-classical economic theory, hyperinflation is rooted in a deterioration of the monetary base, there is little attention paid to the collapse in public confidence that there is a store of value that the currency will be able to command later. Hence, people do not save and the velocity of money increases as people attempt to spend it as fast as they get it. There is a perceived risk of holding currency which rises dramatically at the core. Interest rates rise because they are the premiums people expect in the future when loans are repaid to make a profit. The hyperinflation that was set in motion by the Treaty of V was not limited to Germany. We also saw hyperinflations that I defined as a sharp and sudden doubling in prices (50% decline in the purchasing power of a currency) is less than three months in Austria and Hungary as well during this same period. In the case of Austria, hyperinflation began in October 1921 and continued into September 1922. In Hungary, the hyperinflation unfolded between March 1923 and February 1924. Philip Cagan’s (1956) The Monetary Dynamics of Hyperinflation widely accepted a definition which defines it as a price-level increase of at least 50% per month. However, even Cagan had to make exceptions because this cannot be defined precisely as some percent that is crossed will result definitively in hyperinflation. Therefore, the accepted definition remains rather vague and ill-defined.

In the case of Austria. here there was a separate treaty known as the Treaty of St. Germain which declared that the Austro-Hungarian Empire was to be dissolved. Under article 177 Austria, along with the other Central Powers, accepted responsibility for starting the war. The new Republic of Austria was to then consist of most of the German-speaking Danubian and Alpine provinces in former Cisleithania. Hungary was now split and Austria was commanded to recognize the independence of Hungary, Czechoslovakia, Poland, and the Kingdom of Slovenes, Croats, and Serbs. The Treaty of St. Germain also included ‘war reparations’ of vast sums of money that could also never economically be paid.

In the case of the Austrian Hyperinflation, the foreign-exchange value of the Austrian crown reflected the catastrophic depreciation of this event. In January 1919 one dollar could buy 16.1 crowns on the Vienna foreign-exchange market; by May 1923, a dollar traded for 70,800 crowns. According to the provisions of the Treaty of St. Germain, the newly created Republic of Austria had to overstamp the old paper money of the former Austro-Hungarian Empire still circulating in its territory, then had to replace the overstamped banknotes with new ones, and finally had to introduce an entirely new currency. To complete the first step, the circulating banknotes had to be overstamped with the inscription DEUTSCHÖSTERREICH, and new banknotes were also issued with this feature. Later, still under the name Oesterreichisch-ungarische Bank, banknotes were printed using the German-language clichés on both sides yet still displayed the DEUTSCHÖSTERREICH inscription. From 1920 onward, a new stamp appeared on banknotes: “Ausgegeben nach dem 4. Oktober 1920”. Next, in 1922 a new series of Krone banknotes was introduced with a completely new design to complete the second step. This series contained 1 Krone, 2, 10, 20, 100, 1000, 5000, 50 000, 100 000 and 500 000 Kronen, later 10 000 Kronen (1 000 000 Kronen was planned but not issued). Finally, in 1925, as the third step was to issue a new series of Austrian Schilling banknotes.

During this period, the printing presses worked night and day churning out the currency. At the meeting of the Verein für Sozialpolitik (Society for Social Policy) in 1925, Austrian economist Ludwig von Mises told the audience:

During the first five years after World War I, coal was scarce in Europe. France sought coal for its steelmakers from Germany. But the Germans needed coal for home heating and for their own steel industry, having lost many of their steel plants in Lorraine to the French. As a means of protecting their own growing German steel industry, the German coal producers—whose directors also sat on the boards of the German state railways and German steel companies—began to leverage high costs though shipping rates on coal exports to France.[3]

In early 1923, Germany defaulted on its war reparations payments and German coal producers refused to ship any more coal across the border. In response to this, French and Belgian troops occupied the Ruhr River valley inside the borders of Germany in order to compel the German government to continue to ship coal and coke in the quantities demanded by the Versailles Treaty, which, Germany which characterized as onerous under its post war condition (60% of what Germany had been shipping into the same area before the war began).[4]

This occupation by the French military of the Ruhr, the centre of the German coal and steel industries outraged the German people. They passively resisted the occupation, and the economy suffered, contributing further to the German hyperinflation.

Hyperinflation thus unfolded in Germany because those with money saw what Lenin had done in Russia and sent whatever wealth they had to other places, particularly the United States.  They got their wealth out through using foreign coins, but also collectibles such as stamps and coins in particular. By the end of World War II, most German rare stamps and coins were actually in the United States and were slowly making their way back to Germany during the 1960s and 1970s.

The Weimar Republic then just printed money to pay reparation payments and the entire system collapsed.

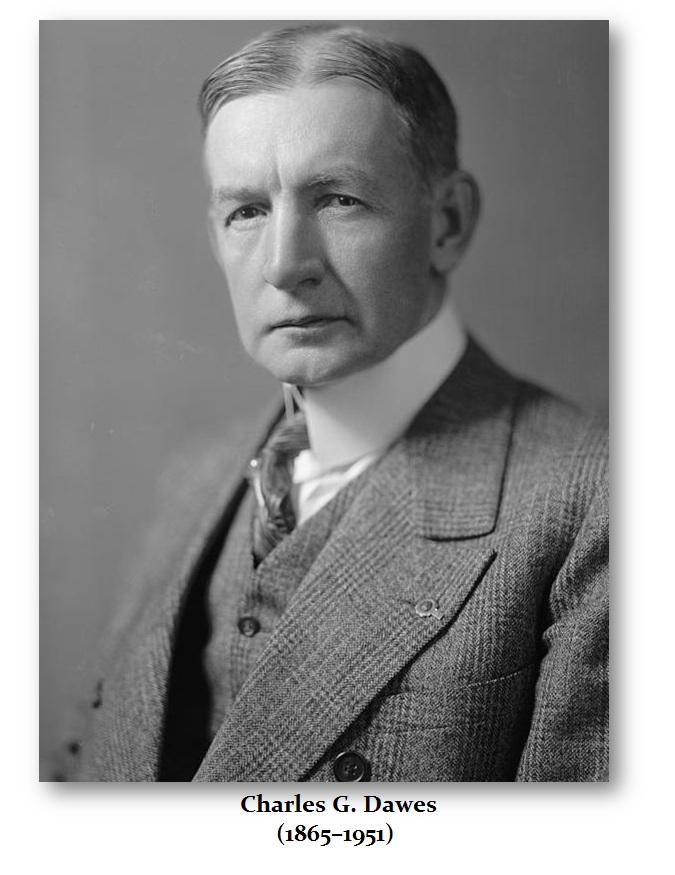
The Dawes Plan (as proposed by the Dawes Committee, chaired by Charles G. Dawes) was an initial plan in 1924 to resolve the World War I reparations that Germany had to pay, which had strained diplomacy following World War I and the Treaty of Versailles.

The Dawes plan provided for an end to the Allied occupation, and a staggered payment plan for Germany’s payment of war reparations. Because the Plan resolved a serious international crisis, Dawes shared the Nobel Peace Prize in 1925 for his work.

It was an interim measure and proved unworkable. The Young Plan was adopted in 1929 to replace it.

President Trump and Turkish President Recep Erdogan – This Should Be Interesting…


The announcement of The United States drawing down troop deployment from Northern Syria – with the United Arab Emirates, and Saudi Arabia sending in replacements to bolster the region, highlights a much larger backstory.

President Obama’s February ’09 Cairo speech began a sequence of events that led to what was called the “Arab Spring“; factually an extremist uprising.  Bolstered by the resulting chaos the Muslim Brotherhood rose to power in Egypt behind Mohammed Morsi.

However, a majority of the Egyptian people rejected President Morsi’s sharia governance, and asked a well respected General Fattah al-Sisi to step in.  Accepting the request of a desperate people Sisi removed Morsi, disbanded the Muslim Brotherhood and went on to win a landslide election in 2014.   The leadership of the Brotherhood fled to Qatar.

President Obama and his policy team was not happy with this outcome.  Obama supported Morsi, not al-Sisi.  Another person who was not happy, was Turkish President Recep Erdogan, who also supported Morsi and the Muslim Brotherhood.

Undeterred, and understanding the need for urgency, Egyptian President al-Sisi then began a long process of confronting extremism.  Sisi destroyed the Hamas terror tunnels on the border between Egypt and Israel; and, despite the anxiety expressed by U.S. Secretary of State John Kerry, Sisi brokered an interim peace agreement between the Palestinian Authority and Israelis.

Destroying the Hamas tunnels removed the physical terror influence of Iran.  President al-Sisi then returned his focus back to Qatar and their support for the exiled leadership of the Brotherhood.

President al-Sisi formed a coalition against Qatar. This coalition included the UAE and Saudi Arabia who withdrew their ambassadors and isolated Qatar in the region.  This was the beginning of what we now call more broadly the Arab coalition.  The coalition initiated sanctions against Qatar until they stopped financing and harboring terror.  Remember this is late in 2014 and a lot is happening really fast.

Against growing pressure from Arab states, including the Gulf Cooperation Council, Qatar agreed to expel seven leaders of the Muslim Brotherhood.  Again reflecting his alignment with the Brotherhood, and with much more grand ambitions of a new Ottoman empire as his unspoken motive, Recep Erdogan provided the terror leaders a home in Turkey.

It is important to note timing (’13, ’14, ’15,) and the political alignments:

  • President Obama, Turkey (Erdogan), Qatar, the Palestinian Authority, and Iran, were aligned with favorable outlook toward the Muslim Brotherhood.
  • Egypt, Israel, Jordan, Saudi Arabia, UAE and the Gulf Arab states were not favorable toward the Muslim Brotherhood.

In the background of this ideological conflict, Syria is in a state of civil war as a result of U.S. Obama policy carried out by Secretary Clinton/Leon Panetta and Secretary Kerry/John Brennan. Obama is aligned with Turkey, again Erodgan, who wants greater influence and has a vision of his new Ottoman empire.  As gatekeeper between Europe and the Middle East, Erdogan knows the value of his geography and the influence it provides him.

Erdogan also wants to absorb Northern Syria and is willing to enlist his Muslim Brotherhood allies toward his goals.  However, Egypt, Israel, Saudi Arabia and the UAE (team anti-Brotherhood) are against the expansion of Turkish influence.

Despite President Obama’s ongoing opposition, Egyptian President al-Sisi faced down Turkey over a U.N. Security Council seat and quietly defeated them.  [In a secret ballot, Erdogan lost.]  At the same time this was happening, expansive energy reserves via natural gas, were discovered to be much larger than initially thought off the coast of Israel.

♦Fast forward to the 2016 presidential election and outcome of a Donald Trump victory.  With President Trump the power dynamic shifts.  Hillary Clinton, recognizing the value of the financial benefit from Qatar, would have supported the Muslim Brotherhood; Donald Trump does not.

The Anti-Brotherhood, anti-extremism team now have an ally.  The key voices are Egyptian President Fattah al-Sisi, Saudi Arabia King Salman, and Crown Prince Mohammed Bin Salman.

President Trump supports the disposition and view of the Arab coalition (Egypt, Jordan, UAE, Saudi Arabia, GCC and ultimately Israel); President Trump is not supportive of the Pro-Brotherhood more extremist team (Turkey, Qatar, Palestinian Authority) and that becomes brutally obvious during the historic U.S.-Gulf summit when President Trump tells the audience to “drive out” the extremist voices.

Back to Syria.  The Brotherhood is the political branch of multiple extremist groups. The bottom line is the Brotherhood supports radical Sunni extremism regardless of faction or fighting force.  President Recep Erdogan of Turkey also favors the Brotherhood; and unfortunately he leverages his position inside NATO with that favorability in mind.

Recep Erdogan wants Northern Syria; and wants to eliminate any resistance toward his gaining Northern Syria; specifically the Kurdish resistance.  Concerns over this key point are what’s driving a wedge between government policy advisers. Differences of opinion over this key point are what’s driving opposition to Trump’s withdrawal position.

The Arab coalition, and Israel, oppose Erdogan.  President Trump has been undergoing a transition period for quite some time.  Trump’s plan is essentially to draw-down U.S. troops in Syria and replace them with regional Arab coalition allies to bolster the Kurds.  Many U.S. voices are concerned that Turkey (Erdogan) will attack this coalition and the Kurds, without the presence of U.S. troops.

Ultimately this is where President Trump becomes important.  President Trump is aware of the duplicitous and untrustworthy nature of President Erdogan; simultaneously Erdogan is in the NATO alliance.  President Trump will obviously not allow fear of a NATO ally to drive U.S. policy; and he’s right.

If you think about it, either: (A) Turkey needs to comply with group regional security and stability measures; or (B) Turkey needs to be kicked out of NATO, confronted and crushed.

Which option do you think President Trump is working on?

Yesterday, December 23rd:

Today, December 24th:

Knowing the economic approach that President Trump brings to solving these challenges, I have a hunch the president is positioning for option “A”, but in the background hoping for the opportunity to use option “B”, which will really get to the root of the problem.

This geopolitical dynamic also provides a more clear understanding of what motives Erdogan held when he was so aggressively antagonizing over the Kashoggi matter and trying to create a fracture in the relationship between President Trump and Crown Prince Mohammed Bin Salman (MbS).

[…]  We now know that Jamal Khashoggi was never a journalist—at least, not in the usual sense of the word; he was a highly-partisan operative who worked with a handler to publish propaganda at the behest of the Emirate of Qatar. He was, in other words, an agent of influence. (read more)

Yes, that’s correct.  Even the New York Times now admits, Jamal Khashoggi was actually receiving his articles from the Qatar government explicitly to push an agenda favorable to their pro-Muslim Brotherhood views.

Now think about this.  In the U.S. we know The Washington Post is essentially the print propaganda for the U.S. intelligence apparatus, and more specifically the CIA.  Khashoggi was working at the Washington Post, to write stories, approved by Qatar, favorable to the Muslim Brotherhood.   The CIA Director was John Brennan; the former head of U.S. CIA Saudi office.

Notice how the pro-Brotherhood ideological gang is all connected around Khashoggi?  Turkey, Qatar, CIA (Obama, Brennan) etc.

Oh, and one last thing…..  Remember that 2014/2015 massive natural gas reserve discovery off the coast of Israel?

Remember that?

Well, there was a recent development:

JERUSALEM (AP) — Prime Minister Benjamin Netanyahu on Thursday said that Israel, Greece and Cyprus will sign an agreement early next year to build a pipeline to carry natural gas from the eastern Mediterranean to Europe, while the United States pledged its support for the ambitious project.

The $7 billion project, expected to take six or seven years to complete, promises to reshape the region as an energy provider and dent Russia’s dominance over the European energy market. It also could curtail Iranian ambitions to use Syria as a gateway to the eastern Mediterranean.

Speaking at a summit with the Greek and Cypriot leaders in southern Israel, Netanyahu said the three nations reaffirmed their commitment to the pipeline and discussed “important aspects” of the project. Italy is also a partner in the pipeline’s planning. Cyprus President Nicos Anastasiades said the project is waiting for a green light from the European Union to move forward.

“We’re going to sign formally, officially, this agreement in a few months,” he said.

In another boost for the project, U.S. Ambassador David Friedman hailed the pipeline as integral to the “stability and prosperity of the Middle East and Europe,” and urged all countries in the region to ensure its success.

Washington is eyeing the east Mediterranean with renewed interest. In a meeting with the Greek foreign minister earlier this month, U.S. Secretary of State Mike Pompeo called the region “an important strategic frontier” for Washington, which is working to strengthen its relations with “democratic allies there like Greece and Cyprus and Israel.”  (read more)

Do you know who was the original energy policy consultant; the person who constructed the obscure -at the time- policy paper plan to avoid an EU pipeline through Turkey; and who put all of these regional heads together; that ultimately ended with this announced deal?

That would be the little known, generally invisible young energy adviser, who would eventually become the central figure in the “spygate” targeting, George Papadopoulos.

Yes, for those following the granules as they expose, that energy extraction strategy alone would have put Papadopoulos in opposition to the interests of President Obama, candidate Clinton, Turkey, Qatar and ultimately Iran and Russia.

Huh… Funny that.

It’s almost as if…..