
It’s obvious to anyone with military training that in today’s world, if there was a war, the wind would be the one that dominated in space. Take out your opponents satellites and GPS and you are finished.
Tag Archives: socialism
The Plight of Mall REITs Linked to Poor Retail Market

Major retailers now have to compete on two fronts — the online world, and the traditional brick-and-mortars. The former is growing by leaps and bounds at the expense of the latter. Because of this dramatic shift in consumer shopping behavior, multiple companies are forced to close their doors. Why have them open and incur steep overhead costs when you can make better sales online?

From a business perspective, it makes perfect sense. But as more companies wake up to this trend, the retail market risks fracturing. That’s because when the big shops close for good, they eliminate the foot traffic that was once there. This siphoning inevitably spells trouble for already embattled retail real estate investment trusts, or REITs.
Mall REITs control the vast properties occupied by major shopping centers and strip malls. For decades, business was good. Anybody that wanted anything in the pre-internet era had to go to a retail establishment, and retailers were willing to pay top dollar for prime real estate. Mall REITs were making money hand over fist.
But all that changed with e-commerce. Physical location no longer carried the magnitude of advantage it once did. As consumers began buying discretionary items through their computers, the brick-and-mortars fell below their break-even point. When they closed, they took the cash flow of mall REITs with them.
The initial closures were the mom-and-pops. But when the majors started collapsing, mall REITs suddenly found themselves in a sea of red ink. And that’s exactly why so many publicly-traded variants have fallen underwater. There’s no one to pick up the slack. Worse yet, in the retail market, nobody wants to.
Shell’s New Permian Play Profitable At $20 A Barrel

by Tyler Durden
Authored by Rakesh Upadhyay via OilPrice.com,

OPEC’s worries about the booming U.S. oil production have increased significantly with the big three oil companies’ interest in shale. Exxon Mobil Corp., Royal Dutch Shell Plc, and Chevron Corp., are planning $10 billion of investments in shale in 2017, a quantum jump compared to previous years. All the naysayers who doubted the longevity of the shale oil industry may have to modify their forecasts.
OPEC lost when they pumped at will as lower oil prices destroyed their finances, and now they are losing their hard-earned market share as a result of cutting production. Shell’s declaration that they can “make money in the Permian with oil at $40 a barrel, with new wells profitable at about $20 a barrel” is an indication that Shell is here to stay, whatever the price of oil.
The arrival of the big three oil companies with their loaded balance sheets is good news for the longevity of the shale industry.
The oil crash, which started in 2014, pushed more than 100 shale oil companies into bankruptcy, causing default on at least $70 billion of debt, according to The Economist. Even the ones that survived haven’t been very profitable, according to Bloomberg, which said that the top 60 listed E&P firms have “burned up cash for 34 of the last 40 quarters”.
Therefore, during the downturn, the smaller players had to slow down their operations, but this will not be the case with the big three.
“Big Oil is cash-flow positive, so they can take a longer-term view,’’ said Bryan Sheffield, the billionaire third-generation oilman who heads Parsley Energy Inc. “You’re going to see them investing more in shale,” reports Bloomberg.
The majors are attempting to further improve the economics of operation. Shell said that its cost per well has been reduced to $5.5 million, a 60 percent drop from 2013. Instead of drilling a single well per pad, which was the norm, Shell is now drilling five wells per pad, 20 feet apart, which saves money previously spent on moving rigs from site to site.
Shell is not the only one—Chevron expects its shale production to increase 30% every year for the next decade. Similarly, Exxon plans to allocate one-third of its drilling budget this year to shale, and it expects to quadruple its shale output by 2025.
“The arrival of Big Oil is very significant for shale,” said Deborah Byers, U.S. energy leader at consultant Ernst & Young in Houston. “It marries a great geological resource with a very strong balance sheet.”
$30 billion has been spent on land acquisitions in the Permian basin since mid-2016, which is a favorite among oil companies.
Considering the new projects and the resurgent shale boom, Goldman Sachs expects oil output to increase by 1 million barrels a day year-on-year. The outcome is an oversupply in the next couple of years.
“2017-19 is likely to see the largest increase in mega projects’ production in history, as the record 2011-13 capex commitment yields fruit,” the U.S. investment bank said in a research note on Tuesday, reports Reuters.
The U.S. Energy Information Administration expects the U.S. oil production to top 10 million barrels by December 2018, a level only surpassed in October and November 1970.
OPEC is running out of options.
Modern Day Snake Oil – Is 2% Growth As Good As It Gets?
by Tyler Durden
Authored by Mike Shedlock via MishTalk.com,
There have been 11 recessions and 11 recoveries since 1949.
The current recovery is the slowest recovery since 1949 and closing in on the becoming longest.
Growth since the 2nd quarter of 2009 is a mere 2.1%. The Wall Street Journal asks Is Two Percent as Good as It Gets?

“The growth seen during the recovery might, for a while, be as good as it gets,” the Federal Reserve Bank of San Francisco’s John Fernald, Stanford University’s Robert Hall, Harvard University’s James Stock, and Princeton University’s Mark Watson said in a study to be presented among Brookings Papers on Economic Activity.
Inquiring minds may wish to download the Brookings’ report entitled Disappointing Recovery of Output After 2009 but I found it a waste of time.
Okun’s Law
The report was mostly mathematical gibberish based on Okun’s Law.
Okun’s law (named after Arthur Melvin Okun, who proposed the relationship in 1962) is an empirically observed relationship between unemployment and losses in a country’s production. The “gap version” states that for every 1% increase in the unemployment rate, a country’s GDP will be roughly an additional 2% lower than its potential GDP. The “difference version” describes the relationship between quarterly changes in unemployment and quarterly changes in real GDP. The stability and usefulness of the law has been disputed.
Clearly, Okun’s Law is at least as useless as any widely believed economic law, which is to say totally useless.
The supporting paper consists of 90 pages of largely unintelligible garbage such as the following.

Commendable Effort
The Wall Street Journal managed to condense 90 pages of nonsense down to 2 pages of nonsense. That’s a highly commendable effort, and the best one could reasonably expect.
Here’s the conclusion: “The causes aren’t entirely clear.”
I searched the 90-page report for the word “debt“. Care to guess the number of hits? I bet you can: zero.
Modern Day Snake Oil
I was discussing economic indicators with Pater Tenebrarum at the Acting Man Blog a couple of days ago. He pinged me with the correct takeaway.
Economic forecasting is not a science, and it is actually not the task of economic science to make forecasts (contrary to what is commonly asserted). Forecasting is akin to the task of the historian. Mises called speculators “historians of the future”.
Economic laws only play a role insofar as they can be used as constraints for a forecast. The problem is that all these models simply look at the data of economic history, at statistical series that always turn tail “unexpectedly”, driven by human action.
All these mathematical models are complete humbug. It is modern-day snake oil.
Still, it’s pretty clear that the market cares nothing for top-down or bottom-up forecasts of economic activity…

Dollar Collapse Continues – Over 80% Of Post-Trump Gains Gone
by Tyler Durden
Re-Posted From ZERO HEDGE Mar 27, 2017 8:48 AM
When the dollar was soaring, it was ‘unequivocally’ a reflection of the strength (or potential strength) of the US economy and its safe-haven, cleanest-dirty-short status. Since The Fed hiked rates for the 3rd time in 11 years, however, the dollar has done nothing but decline…
Erasing over 80% of post-Trump gains…

The Dollar Index has also plunged back to a 98 handle…

So is this “good” news? All those multi-national S&P companies benefit? We are sure Wall Street chattering heads will find a positive narrative any second now.
Tax Revolt in Belarus Turning to Mass Arrests
Armstrong Economics Blog/Civil Unrest
Re-Posted Mar 27, 2017 by Martin Armstrong

 For weeks now, thousands of people have gone public in Belarus to protest against a special tax for “little workers” and demanded the resignation of Aleksandr Grigoryevich Lukashenko who has been the autocratic President of Belarus, in office since July 20th, 1994. Lukashenko had issued a decree that people who work less than six months a year have to pay a tax of 189 euros. This was to prevent “social parasitism”, which he explained was the justification. In view of the protests, he temporarily suspended the decree, but the crisis is getting worse.
Lukashenko is seen by many as really a dictator. His police arrests those who were going to speak at the protest and they stormed the human rights office arresting people there in advance. The instability building in Belarus is really serious. Additionally, Lukashenko has lashed out at Russia and accused Moscow of violating their 20-year old border agreement, in a escalating dispute that has become a source of tension with his country’s neighbor and strongest ally. It appears that we will see the collapse of the current government by 2020.
Russia and Belarus share a border under a 1996 deal that set up a commonwealth known as the Union State. However, in February 2017, Russia set-up checkpoints at crossings into Belarus in response to Mr Lukashenko’s decision to introduce five-day visa waivers for citizens of 79 countries, including the US and EU member states. This has provoked tensions with Russia which is concerned that Belarus will move towards the west.
Everywhere we look around the global, tensions are building in conflicts both domestic and international. This is on schedule for building in intensity going into the peak of the next wave of the Economic Confidence Model hitting in 2022-2023. We must keep this in mind relative to markets moving forward.
NATO Troops moved from Germany to Poland on Weekend
Armstrong Economics Blog/Russia
Re-Posted Mar 27, 2017 by Martin Armstrong

Soldiers were moved on the weekend from the garrison at Vilseck and were restationed at Orzysz in Poland close to the border with Belarus. This was a NATO unit consisting of units from the USA, Great Britain and Romania. With tensions building between Belarus and Russia, this particular troop reassignment is interesting to say the least.
Macedonia Reject Soros & the EU Socialism
Armstrong Economics Blog/Eastern Europe
Re-Posted Mar 27, 2017 by Martin Armstrong
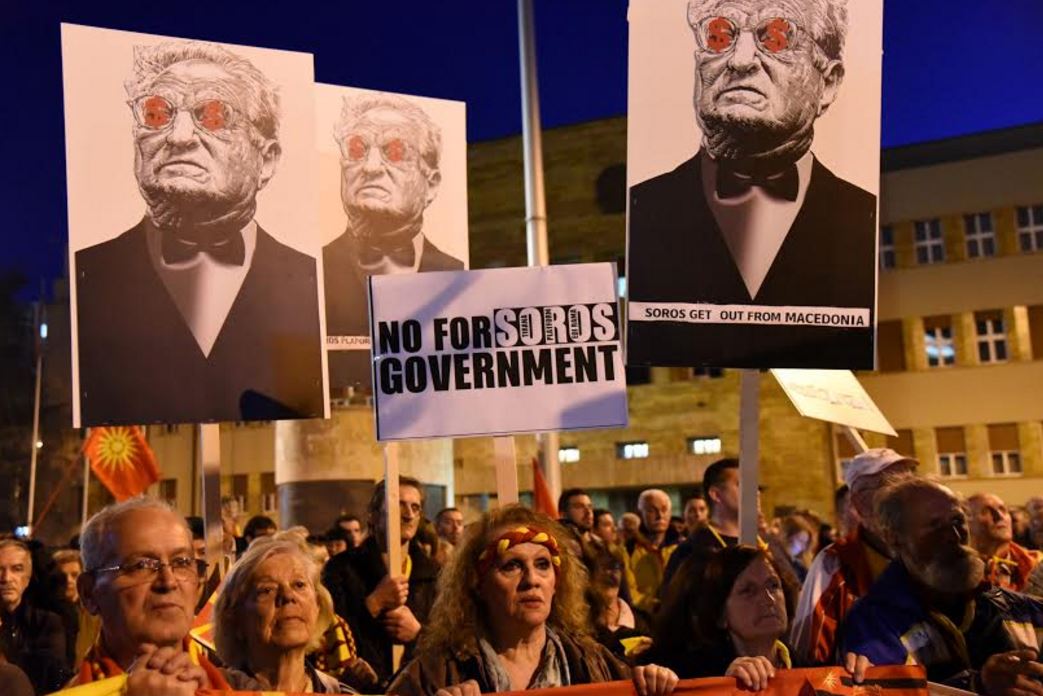
 For 26-days straight, thousands of people have taken to the streets in order to send the message to Soros and European leaders that the people of Macedonia are a sovereign nation who utterly reject the left-wing agenda to divide the nation and bring a socialist-Muslim coalition to power. Johannes Hahn is an Austrian politician, who since November 2014 is Commissioner for European Neighbourhood Policy & Enlargement. He went to earlier last week to Skopje, in Macedonia, where he held talks with political representatives in a bid to contribute to a solution to the political deadlock there to get Macedonia to join the EU.
There was considerable corruption where the Prime Minister Nikola Gruevski was forced to resign in December 2015. The EU brokered elections in December 2016 to end the protests against the government of Gruevski. The December 2016 elections have left a transitional government was installed including from 20 October 20th, 2015 with the two main parties, VMRO-DPMNE and the Social Democratic Union (SDSM).
Then in late December, the Albanian Prime Minister Edi Rama invited the leaders of four Albanian parties in Macedonia to Tirana for a meeting at which they formulated a so-called “Tirana Platform,” which was really under the auspices of the Albanian government. This called for the Albanian language to be granted official status in Macedonia, judicial reform, EU membership and NATO membership. This was the first straw that broke the back where the people were protesting about the status of the Albanian language in Macedonia. According to the census from 2002, there were 1.3 million Macedonians of which there were 509,000 Albanians in the country.

What is clear is there has been a concerted effort to take over Macedonia by the European Commission. This seems to be part of their need to sure up the EU following BREXIT and to create a NATO buffer against Russia. However, Johannes Hahn’s attempt to win over the politicians in Macedonia prompted protests of more than 200,000 people coming to the streets – a huge number for Macedonia. It was reported:
“Hahn, instead of meeting with us, wrote on his Twitter account that the road to the EU remains open for Skopje. He did not mention the name of our country, but wrote Skopje instead. Well, Commissioner Hahn, Macedonia is not just Skopje. Macedonia is Bitola, Ohrid, Prilep, Kumanovo, as well, and all the other 43 cities and towns where tonight 200,000 people took to the streets,” Protest organizer Bogdan Ilijevski said, according to Independent.mk.
In turn, Macedonian President Gjorge Ivanov was forced to refuse to meet with Hahn. The crisis that has been brewing was made worse by Hahn who had criticized Ivanov’s decision to refuse to meet with the Social Democratic Union of Macedonia (SDSM) leader Zoran Zaev, who gained Albanian support in return for concessions including the institution of Albanian as a second official language.
Soros’s Open Society is the attempt to force political change rather than allow laissez-faire capitalism to even exit. We do not live in a democracy when politicians reject the will of the people and we do not live under capitalism when governments are corrupt, take bribes to regulate benefits for special interests. That is simply an oligarchy – not capitalism as in Adam Smiths Invisible Hand.
Stocks, Dollar Tumble As Gold Tops $1250; Dead Bill Bounce Dies
by Tyler Durden
Re-Posted From ZERO HEDGE Mar 26, 2017 8:13 PM
It appears the false narrative of the failed healthcare reform bill being somehow great news for stocks has been eviscerated in early Asia trading. The dollar has tumbled to its lowest since Nov 10th, Gold has ripped back above $1250, and S&P futures have plunged to 6 week lows.

The Bloomberg Dollar Index has almost erased the entire post-Trump-election gains…

Need A Strategy For Income? Find Out About The Three Rs of Dividends
ClearBridge Dividend Strategy Portfolios target total return, risk management and dividend potential. Discover the strength of Legg Mason – A Leader In Separately Managed Accounts.
US equity futures are tumbling – Dow is down over 700 points from its highs…

And gold is back above $1250…

It appears faith is fading fast in Trump trades.
- 8,918
- 26
On The Edge Of An “Uncontrollable Liquidity Event”: The Definitive Guide To China’s Financial System
by Tyler Durden
Re-Posted From ZERO HEDGE Mar 26, 2017 8:26 PM
While most traders over the past month have been obsessing over developments in Washington, the real action – most of it under the radar – has played out in China, where as discussed over the past few weeks, domestic liquidity has tightened notably, culminating with an unexpected bailout by the PBOC of various smaller banks who defaulted on their interbank loans as interested rates particularly on Certificates of Deposit (CD) – which have become a preferred funding conduit for many Chinese banks – soared. Ironically, these mini PBOC bailouts took place only after the PBOC itself decided to tighten conditions sufficient to choke off much of the shadow debt funding China’s traditional banks.
As a result, the interbank CD rate rallied strongly, leaving a narrower or negative spread for some smaller banks, whose legacy carry trades (see below for details) suddenly became unprofitable. Also, as reported last Tuesday, several small banks failed to meet overnight repo obligations. This liquidity tightness has been mainly due to escalating financial deleveraging, as the PBOC has lifted market rates and rolled out stricter macroprudential policy rules.
But all those events in isolation seem as merely noise against what otherwise appears to be a relatively benign, even boring, backdrop: after all, neither China’s stock, nor bond markets, has seen even remote volatility in recent months, and certainly nothing compared to what was experienced one year ago, when the Chinese turmoil nearly led to a bear market across developed markets. Then again, maybe the markets are simply once again behind the curve due to all the inherent complexity of China’s unprecedented, financialized and extremely complex pre-Minsky moment ponzi scheme.
Last last week, Deutsche Bank analysts led by Hans Fan released what is the definitive research report summarizing all the latest troubling trends facing China, which judging by capital markets, nobody is paying any attention to. They should, because as Deutsche Bank puts it, if taken too far, they threaten an “uncontrollable liquidity event“, i.e., the financial cataclysm that Kyle Bass and other perma-china-bears have been waiting for.
And, as usual, it all started with rising interest rates, which in turn is leading to increasing funding pressure, which if left unchecked, could lead to dire consequences for China’s underfunded banking system.
Here is a fantastic explanation of everything that has happened in China in recent weeks, and more importantly, what may happen next, courtesy of Deutsche Bank. We urge readers to familiarize themselves with the content as we will refer back to this article in future posts.
* * *
Only in early stage of financial deleveraging
China’s monetary policy has been shifting gradually towards a tightening stance since 2H16. Targeting the liabilities side of the banking sector, the PBOC hiked rates of monetary tools, such as MLF, SLF and OMO (Figure 1), and withdrew liquidity on a net basis after the Chinese New Year (Figure 2). At the same time, it targeted the asset side of the banking sector when it rolled out stricter MPA rules by including off-BS WMP credit in broader credit assessment and imposing stricter-than-expected penalties on banks that fail to comply.

As a result, the key indicators in the money market, including repo and CD rates, all suggest stretched domestic liquidity. For example, the 7-day repo rate, which is the most representative liquidity indicator, has exceeded the interest rate corridor ceiling of 3.45% several times this year (Figure 3). Moreover, the interbank CD rate spiked to 4.6% on 20 Mar 2017, up c.180bps from last year’s low (Figure 4).

We summarize in the below diagram recent financial deleveraging efforts by regulators.

Why push forward financial deleveraging?
We believe the PBOC aims mainly to contain the fast-growing leverage in China’s financial sector. In our view, the country’s financial leverage basically relates to speculators borrowing excessive wholesale funding to grow assets and chase yield, rather than relying on vanilla deposits. To measure this, we believe one of the good indicators of financial leverage is the credit-to-deposit ratio, calculated as total banking credit as a percentage of total deposits. The higher the ratio, the more fragile the financial sector, and the more likely the banking system will run into difficulties to finance unexpected funding requirements. Traditionally the loan-to-deposit ratio was widely used to measure system liquidity risk, but has become increasingly irrelevant in China, as banks are growing their bond investments and shadow banking books to extend credit.
As shown in Figure 6, the credit-to-deposit ratio in China’s banking system has risen sharply by 27ppts since 2011 to reach 116% as of February 2017. We see the rising credit-to-deposit ratio basically is a function of increasing reliance on wholesale funding to support strong credit growth. As of end 2016, borrowing from banks and NBFIs accounted for 17% of total liabilities, against 8% 10 years ago (Figure 7).

Which banks are more leveraged? Joint-stock banks and city/rural banks
As we have long argued, the risks are not evenly distributed in China’s banking system; there are notable differences in the balance sheet structures of different types of banks. As shown in Figure 8, medium-sized banks, which mainly include joint-stock banks, recorded the highest credit-to-deposit ratios and hence are most reliant on wholesale funding. At the same time, small banks, which mainly include city/rural commercial banks, also delivered notable increases in credit-to-deposit ratios, despite a lower absolute level. The credit-to-deposit ratio for small banks has increased by 30ppts since 2010, vs. 14ppts for the big-four banks in the same period.
On the liabilities side, medium-sized and small banks mainly rely on wholesale funding, i.e. borrowing from banks and NBFIs. As of 1H16, wholesale funding made up 31% and 23% for medium-sized and small banks, respectively, against only 13% for big-four banks, as shown in Figure 9.

A closer look into interbank CDs – funding pressure ahead
Wholesale funding for smaller banks has been obtained mainly by issuing CDs in the interbank market. Interbank CDs have supported 20% of smaller banks’ assets expansion over the past 12 months. Since the introduction of interbank CDs in 2014, CD issuance recorded strong growth and the balance jumped 89% yoy to Rmb7.3tr in Feb 2017 (Figure 10), or 3.4% of total banking liabilities.

Joint-stock and city/rural banks account for 99% of issuance (Figure 12). In the coming months these banks have ambitious CD pipelines. More than 400 banks announced plans to issue CDs worth Rmb14.6tr in 2017. This represents 60% yoy growth from the issuance plan in 2016. Investor-wise, WMPs, various asset management plans and commercial banks themselves are the major buyers, which combined make up 79% of the total balance (Figure 13).

However, we view banks that are more reliant on CDs as more vulnerable to rising rates and tighter regulations.
Reflecting tighter liquidity, the interbank CD rate has rallied strongly, with the 6-month CD pricing at 4.6% on average. Some CDs issued by smaller rural commercial banks have been priced close to 5% recently. This would have pushed up the funding cost and notably for smaller banks. If banks invest in low-risk assets such as mortgages, discounted bills and treasury bonds, this would lead to a negative spread. Alternatively, banks can lengthen asset duration, increase the risk appetite, add leverage or slow down asset growth. Among these alternatives, we believe a slowdown in asset growth is the most likely.

Caixin previously reported CDs are likely to be reclassified as interbank liabilities, capped at 33% of total liabilities. This potential regulation could add funding pressure for banks with a heavy reliance on interbank liabilities. With Rmb4tr interbank CDs to mature during Mar- Jun 2017 (Figure 16) and interbank liabilities exposure approaching the limit (Figure 17), joint-stock and city/rural banks are subject to notable funding pressure.

We show the listed banks’ issuances in the chart below. INDB, SPDB and PAB are among the most exposed to interbank CDs.

* * *
What are the implications?
Are we close to a “tipping point”?
For now, probably not, especially in a year of leadership transition. In our view, the risk of an uncontrollable liquidity event is low, as the PBOC will do whatever it takes to inject liquidity if needed. In the domestic liquidity market, the PBOC exerts strong influence in both the volume and pricing of liquidity. With 90%+ of financial institutions directly or indirectly controlled by the government, PBOC will likely continue to give liquidity support. In 2H15, the central bank established an interest rate corridor to contain interbank rates within a narrow range and pledged to inject unlimited liquidity to support banks with funding needs.
However, continuing liquidity injections do not come without a cost. A bigger asset bubble, persistent capital outflow pressure and a lower yield curve over the longer term are side effects that China will have to bear. At the same time, the execution risk of PBOC itself is rising.

Implications on system credit growth
We expect system credit growth to moderate from 16.4% yoy in 2016 (16.1% in Feb’17) to approximately 14-15% yoy in 2017 (Figure 23). As a result, the credit impulse is likely to trend lower from the current high level (Figure 24). The slower credit growth is mainly attributable to several factors: 1) a tighter liquidity stance to push up the funding cost of smaller banks and to force them to slow down asset growth; 2) further curbs on shadow banking; 3) a higher bond yield to defer bond issuance; and 4) slower mortgage loan growth.

Appendix A – Liquidity flows in China’s interbank market
New deposits supported 55% of asset growth in China’s banking system in 2016. The remaining 45% of new assets were mainly funded by borrowing from PBOC (19%) and borrowing from each other (19%, including bond issuance). While borrowing from NBFIs remained flat for the entire system, it was the main funding source for medium-sized and small banks. We summarize the liquidity flows in China’s interbank market in Appendix A.

Liquidity injection from PBOC. Over the past 12 months, to offset the liquidity drain from falling FX reserves, the PBOC has injected a huge amount of liquidity worth Rmb5.8tr into the banking system, which is equivalent to 400bps of RRR cuts (Figure 29). Of this injection, 30% and 24% have been made to support joint-stock banks and policy banks, respectively (Figure 30). For details, please see our report, PBOC liquidity facilities: Doing whatever it takes, 23 January 2017.

Borrowing from interbank market. Policy banks and big-four banks are net interbank lenders, while joint-stock and city/rural commercial banks are net borrowers. Joint-stock and city/rural banks not only borrow from policy/big banks, but also from each other. This could potentially lead to stronger contagion effects if some of them run into liquidity stress.

Lending/borrowing between banks and NBFIs. There has been a sharp rise in net claims to NBFIs from banks (Figure 33). We believe this is due to rising shadow banking transactions and also arbitrage activities with funds self-circulating within the financial sector. Clearly as shown in Figure 34, small banks are key lenders to NBFIs

Appendix B – What is driving the financial leverage?
From the accounting perspective, we believe the rising credit-to-deposit ratio is mainly due to bank credit circulating back into the banking system as non-deposit liabilities. In normal cases, when a bank makes a $100 corporate loan or purchases a $100 corporate bond, the bank books the credit to a corporate on the asset side while it also books a deposit on the liability side. We show a normal case in Figure 35. However, if a bank’s money circulates back into the banking system, just like in the two cases we illustrate in the diagram below, the $100 deposit is removed but interbank borrowing or borrowing from NBFIs would increase by $100. While there are likely to be many variants of bank credit circulation, we elaborate on two cases in detail.

Case #1: Bank credit circling via NBFIs
It is well known that NBFIs have been serving as SPVs to channel shadow banking credit from banks to corporates in past years. What is insufficiently addressed though is that NBFIs also have been acting as channels for bank credit circling. Let us show a simple example below:
- First, Bank A invests in an asset management plan packaged by an NBFI. This is booked as a receivable investment on Bank A’s balance sheet.
- Second, the NBFI invests further in a CD issued by Bank B. Bank B books the CD under interbank borrowing. The money circulates back into the banking system and no deposit is generated.
- In some cases, if the yield of the CD does not cover the cost of issuing the asset management plan, the NBFI will leverage up in the bond market by pledging the CD through repo transactions. The leverage could be built up by two transactions: 1) entrusted bond investment (“Daichi” in Chinese); or 2) entrusted investment (“Weiwai” in Chinese), which we discuss in detail in our 2017 outlook report.
- In this case we use the investment in a bank’s CD as an example. In reality it applies to investment in interbank CDs, interbank negotiated deposits and financial bonds issued by banks, which are all circulating money back into the banking system.
The bank credit circling through NBFIs is growing rapidly. This is evidenced by strong growth in banks’ receivable investments, which reached Rmb21tr as of end-2016 to account for 10% of commercial banking assets, as shown in Figure 36. This represents 80% CAGR in balance since 2013. The majority of these investments was made by medium-sized and small banks. Note that not all receivable investments are credit circling, but we believe it should make up a notable portion. We summarize the structure of banks’ receivable investments in Figure 38.
The NBFI here could be any trust company, broker, fund subsidiary or insurance company. We believe brokers and fund subsidiaries should be the key players, as their bond trading leverage in the interbank bond market is much higher than other participants (Figure 37).


Case #2: Bank credit circling via corporates
Corporate loans may circle back into the banking system as well. This is because many corporates use borrowed but idle cash to buy bank WMPs. Below is a simple example:
- Firstly, Bank A makes a loan to a corporate.
- Secondly, the corporate uses the loan proceeds to buy a wealth management product issued by Bank A.
- Thirdly, Bank A invests the WMP fund in a financial bond issued by Bank B. This corporate deposit would circle back to the banking system as a non-core liability.
- To make this process economic, in many cases it would require leverage. The corporate borrowing cost may be at 4%, but the financial bond issued by Bank B may only yield 3.5%. To compensate the yield shortage, Bank A has to entrust the WMP fund to a third party and to leverage up by pledging the bonds through repo transactions. This process is called entrusted investment (“Weiwai” in Chinese, or entrusting to an external party).
This type of transaction is not an individual case. As shown in Figure 39, corporates purchased Rmb7.7tr WMPs in 1H16. This accounted for 7% of total corporate debt in China, or 29% of total WMP AUM in the system. SOEs, large private corporate and listed companies enjoy ample bank lending resources with low interest cost. However, the lack of attractive investment projects in their own business prompts them to invest in the financial market (i.e. bank WMPs).


